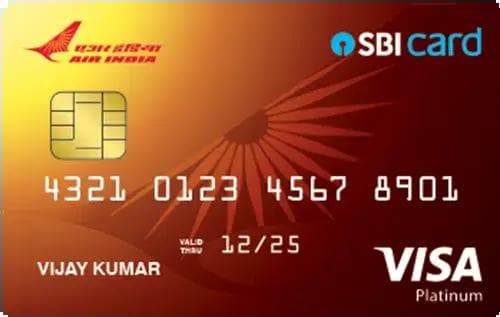
Quick Verdict
- The Air India SBI Platinum Credit Cardⓘ wins for everyday spend with a higher base reward rate of 1% compared to SBI Prime’s 0.5%.
- For travel and lounge access, SBI Prime Credit Cardⓘ offers more value with international lounge access and Priority Pass membership.
- Air India SBI Platinum is cheaper to hold with an annual fee of Rs 1,499 versus Rs 2,999 for SBI Prime, but SBI Prime’s fee can be waived on Rs 3 lakh annual spend.
- Choose Air India SBI Platinum if you prioritize travel rewards on Air India and lower fees; pick SBI Prime if you want broader rewards on dining, grocery, utilities, and premium lounge benefits.
Side by Side
| Detail | Air India SBI Platinum Credit Cardⓘ | SBI Prime Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 1,499 | Rs 2,999 |
| Joining fee | Rs 1,499 | Rs 2,999 |
| Fee waiver on spend | Rs 3.00 lakh | |
| Reward rate | 1% base, 7.5% travel | 0.5% base, 2.5% dining/grocery/utilities |
| Reward type | miles | points |
| Domestic lounge | 8 per year | 8 per year |
| International lounge | None | 4 per year |
| Forex markup | 3.5% | 3.5% |
| Best suited for | travel, rewards, lounge | rewards, dining, lounge, grocery, travel, shopping |
Rewards Compared
Spending Rs 10,000 on the Air India SBI Platinum Credit Cardⓘ earns Rs 100 back at the base rate of 1%. This card shines in the travel category, offering an effective return of Rs 750 per Rs 10,000 spent on travel, which is significantly higher than its base rate. The rewards are issued as miles, which can be converted to Maharaja Points with the complimentary Air India Maharaja Club membership, enhancing value for frequent Air India flyers.
On the other hand, the SBI Prime Credit Cardⓘ yields Rs 50 per Rs 10,000 spent at the base rate of 0.5%. However, it provides elevated returns of Rs 250 per Rs 10,000 in dining, grocery, and utilities categories, making it more rewarding for everyday lifestyle spends. Rewards are points, which can be redeemed across a variety of partners. While the base rate is lower than Air India SBI Platinum, SBI Prime’s category bonuses cover more common spend categories.
Fees Compared
The Air India SBI Platinum Credit Cardⓘ charges Rs 1,499 as both joining and annual fees, with no fee waiver on spend. To cover the annual fee purely through base rewards, you would need to spend about Rs 1.5 lakh annually. This makes it a cost-effective card for moderate spenders who focus on travel rewards.
The SBI Prime Credit Cardⓘ has a higher joining and annual fee of Rs 2,999 each. However, this fee is waived if you spend Rs 3 lakh annually, which breaks down to Rs 25,000 per month. To cover the fee at the base reward rate alone, you would need to spend about Rs 6 lakh annually, which is quite high. Therefore, the fee waiver threshold is crucial to consider for SBI Prime to be cost-effective.
Which One Should You Pick
Choose the Air India SBI Platinum Credit Cardⓘ if you are a frequent Air India traveler or someone who seeks a straightforward travel rewards card with a lower annual fee. It suits those who want to earn miles and enjoy domestic lounge access without the burden of a high fee waiver spend. However, if you rarely fly Air India or want international lounge access, this card might not meet all your needs.
The SBI Prime Credit Cardⓘ is ideal for high spenders who can meet the Rs 3 lakh annual fee waiver threshold and want a versatile card that rewards dining, grocery, utilities, and travel. Its Priority Pass membership and international lounge access add premium value for frequent travelers. Skip this card if you do not spend enough to waive the fee or if you prefer miles over points.
Overall, if your priority is travel on Air India and lower fees, go for the Air India SBI Platinum Credit Cardⓘ. If you want broader rewards and premium lounge access and can meet the spend requirement, SBI Prime Credit Cardⓘ is the better choice.
What to Check Before You Apply
- Confirm if your typical spend aligns with the fee waiver threshold on SBI Prime to avoid paying the annual fee unnecessarily.
- Understand the redemption value and flexibility of miles versus points for your travel and shopping preferences.
- Be aware of the forex markup of 3.5% on both cards for foreign currency transactions, which can add significant cost.
- Check the number and locations of domestic and international lounges accessible, especially if you travel frequently abroad.

Comments
No comments yet
Be the first to share your experience with this card.