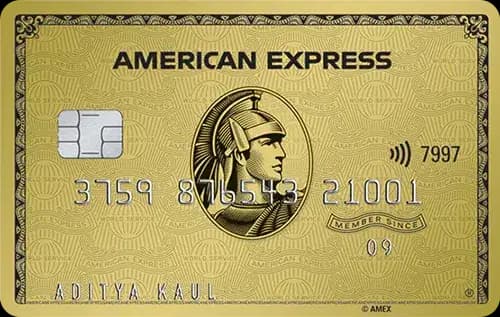
Quick Verdict
- For everyday spend, the RBL Bank Icon Credit Card ⓘ wins with a higher base reward rate and strong category bonuses.
- For travel and lounge access, the RBL Bank Icon Credit Card ⓘ also leads, offering both domestic and international lounges plus golf and concierge benefits.
- The American Express Gold Credit Card ⓘ is cheaper to hold if you do not meet the higher waiver threshold of the RBL card.
- Choose the Amex Gold ⓘ if you want moderate rewards and premium dining discounts; pick the RBL Icon ⓘ if you spend heavily on travel and dining and value lounge access.
Side by Side
| Detail | American Express Gold Credit Card ⓘ | RBL Bank Icon Credit Card ⓘ |
|---|---|---|
| Annual fee | Rs 4,500 | Rs 5,000 |
| Joining fee | Rs 1,000 | Rs 5,000 |
| Fee waiver on spend | None | Rs 3.00 lakh annually (Rs 25,000 monthly) |
| Reward rate | 0.5% base | 0.8% base, 4% dining & travel |
| Reward type | Points | Points |
| Domestic lounge | 8 per year | 8 per year |
| International lounge | None | 4 per year |
| Forex markup | 3.5% | 2% |
| Best suited for | Rewards, travel, shopping | Travel, dining, lounge, rewards, shopping |
Rewards Compared
The American Express Gold Credit Card ⓘ offers a base reward rate of 0.5%, which means for every Rs 10,000 spent, you earn Rs 50 worth of points. This card focuses on broad rewards with additional perks like dining discounts and hotel offers, but the base rate is modest. There are no elevated category rates, so the Rs 50 return on Rs 10,000 spend remains consistent across spends.
In contrast, the RBL Bank Icon Credit Card ⓘ delivers a higher base reward rate of 0.8%, translating to Rs 80 per Rs 10,000 spent. More importantly, it offers 4% returns on dining and travel categories, which means Rs 400 back on Rs 10,000 spent in these categories. This makes it a strong contender for those who spend heavily on dining and travel. The presence of milestone rewards further enhances its value for high spenders.
Fees Compared
The American Express Gold Credit Card ⓘ charges a joining fee of Rs 1,000 and an annual fee of Rs 4,500, with no fee waiver available regardless of spend. To cover the Rs 4,500 annual fee purely through base rewards, you would need to spend approximately Rs 9,00,000 annually.
The RBL Bank Icon Credit Card ⓘ has a higher joining fee of Rs 5,000 and an annual fee of Rs 5,000. However, the annual fee is waived if you spend Rs 3,00,000 or more annually (about Rs 25,000 per month). To cover the Rs 5,000 fee through base rewards alone, you need to spend about Rs 6,25,000 annually. The RBL card’s higher base rate and fee waiver make it more cost-effective for moderate to high spenders, despite the higher upfront fees.
The head-to-head difference in annual fee is Rs 500 more for the RBL card, but the higher reward rate means you only need to spend an additional Rs 1,66,667 annually to justify this extra fee.
Which One Should You Pick
The American Express Gold Credit Card ⓘ suits those who want a reliable rewards card with premium dining and hotel discounts and do not want to worry about meeting a high spend threshold for fee waivers. It is ideal for moderate spenders who value lifestyle benefits like Apple Store cashback and skin clinic discounts. Skip this card if you spend heavily on travel or dining and want better lounge access.
The RBL Bank Icon Credit Card ⓘ is best for frequent travelers and dining enthusiasts who can meet the Rs 3,00,000 annual spend to waive the fee and maximize category rewards. Its international lounge access, golf privileges, and concierge services add premium value. Avoid this card if your spend is low or irregular, as the fees and spend gates could outweigh the benefits.
Overall, the RBL Bank Icon Credit Card ⓘ wins for those seeking maximum rewards and travel perks, while the American Express Gold Credit Card ⓘ is a solid choice for moderate spenders wanting lifestyle benefits without a spend commitment.
What to Check Before You Apply
- Confirm the quarterly Rs 35,000 spend requirement for domestic lounge access on the RBL Icon ⓘ.
- Understand the redemption value of points for both cards to ensure rewards translate into real savings.
- Calculate if your monthly spend meets the Rs 25,000 threshold to waive the RBL Icon’s ⓘ annual fee.
- Be aware of the 3.5% forex markup on the Amex Gold ⓘ versus 2% on the RBL Icon ⓘ, especially if you travel internationally.

Comments
No comments yet
Be the first to share your experience with this card.