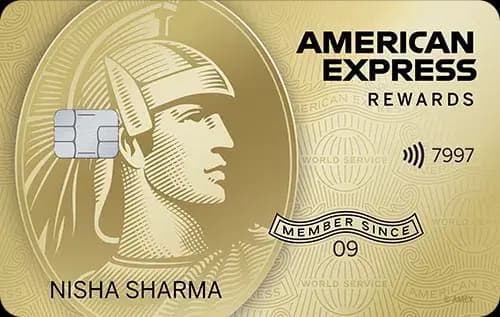
Quick Verdict
- The American Express Membership Rewards Credit Cardⓘ wins for everyday spend with a higher base reward rate of 0.5%, giving Rs 50 back on Rs 10,000 spent.
- The RBL World Safari Credit Cardⓘ is the better choice for travel and forex, offering 2% rewards on travel spends and zero forex markup.
- RBL World Safari has a lower annual fee of Rs 3,000 plus a higher joining fee of Rs 3,000, compared to Amex’s Rs 4,500 annual and Rs 1,000 joining fee.
- Pick the Amex cardⓘ if you want straightforward rewards on shopping and dining without the need for travel benefits. Choose the RBL World Safariⓘ if you travel frequently, want lounge access, and want to avoid forex charges.
Side by Side
| Detail | American Express Membership Rewards Credit Cardⓘ | RBL World Safari Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 4,500 | Rs 3,000 |
| Joining fee | Rs 1,000 | Rs 3,000 |
| Fee waiver on spend | None | Rs 35,000 quarterly domestic lounge spend |
| Reward rate | 0.5% base | 0.4% base, 2% travel category |
| Reward type | Points | Points |
| Domestic lounge | None | 8 per year |
| International lounge | None | 4 per year |
| Forex markup | 3.5% | 0% |
| Best suited for | rewards, first-card, shopping | travel, forex, lounge |
Rewards Compared
The American Express Membership Rewards Credit Cardⓘ offers a consistent base reward rate of 0.5%, which translates to Rs 50 back for every Rs 10,000 spent across all categories. This straightforward return is supplemented by welcome bonuses and dining discounts that can boost value for regular shoppers and casual spenders. Its reward points can be multiplied up to 5X at select partner brands, although this depends on usage patterns.
In contrast, the RBL World Safari Credit Cardⓘ delivers Rs 40 back per Rs 10,000 spent as a base rate, slightly lower than the Amex cardⓘ. However, it significantly excels in travel categories with a 2% return, amounting to Rs 200 per Rs 10,000 spent on travel. This makes it very attractive for frequent travelers who spend heavily on flights and hotels. The card’s points earn structure is more category-sensitive, rewarding travel much more generously but offering less on everyday spends.
Fees Compared
The Amex cardⓘ charges an annual fee of Rs 4,500 and a joining fee of Rs 1,000. There is no fee waiver threshold based on spend, so the fees are fixed regardless of usage. To cover the Rs 4,500 annual fee through rewards alone at the base rate, a cardholder would need to spend Rs 9,00,000 annually.
The RBL World Safariⓘ card has a lower annual fee of Rs 3,000 but a higher joining fee of Rs 3,000. Fee waiver is linked to lounge usage and spending Rs 35,000 quarterly on domestic lounges, which may be difficult for non-frequent travelers. The break-even spend to cover the base fee in rewards is Rs 7,50,000 annually. Given the better travel rewards and zero forex markup, the card’s fees can be justified more easily by travel-focused users.
In head-to-head terms, the Amexⓘ card demands Rs 1,500 more annually in fees. To justify this by its higher base reward rate alone, a cardholder would need to spend an additional Rs 15,00,000, a sum that most users will not reach. Thus, fee differences are significant and should influence the choice.
Which One Should You Pick
Choose the American Express Membership Rewards Credit Cardⓘ if you are a shopper or first-time credit card user who prefers simple and steady rewards on everyday spending, such as shopping and dining. Its moderate fees are offset by dining discounts and partner multipliers, making it a rewarding choice for lifestyle benefits. Avoid this card if you travel frequently or want lounge access and forex cost savings.
Opt for the RBL World Safari Credit Cardⓘ if you are a frequent traveler or someone who makes substantial foreign currency transactions. Its zero forex markup and travel category rewards make it the more cost-effective card for travel spends. The complimentary lounge access and travel insurance are valuable perks. However, if you rarely travel or spend below the quarterly lounge spend gate, the higher joining fee and conditional fee waiver may reduce its appeal.
Overall, travelers and forex users should pick the RBL World Safariⓘ card, while everyday shoppers and lifestyle spenders should go for the Amexⓘ card. Those who want a no-fuss rewards card with decent return on casual spends will find the Amexⓘ more straightforward, while travel enthusiasts will find RBL World Safariⓘ more rewarding despite the fee structure.
What to Check Before You Apply
- Check the quarterly Rs 35,000 lounge spend requirement on the RBL World Safariⓘ card to ensure you can meet it for fee waivers.
- Understand the redemption value of each card’s points, as point value can vary widely and impact real rewards.
- Calculate if your spend justifies the higher Rs 4,500 annual fee of the Amexⓘ card or the Rs 3,000 joining fee of the RBL World Safariⓘ.
- Consider the forex markup: 3.5% on Amexⓘ can be costly if you spend a lot abroad, whereas RBL World Safariⓘ charges no forex fees.
- Verify which lounges are accessible with the RBL World Safariⓘ card and if they are convenient for your travel routes.

Comments
No comments yet
Be the first to share your experience with this card.