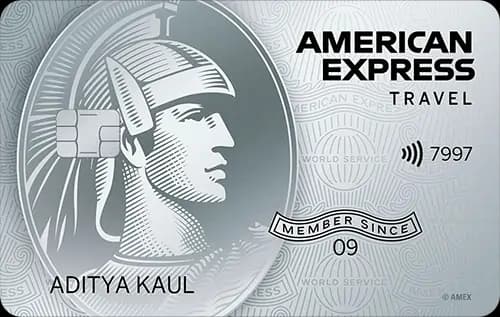
Quick Verdict
- The Zenith Credit Cardⓘ wins for everyday spending due to its higher base reward rate and strong category bonuses.
- For travel and lounge access, Zenith Credit Cardⓘ also leads with international lounge visits and a lower forex markup.
- The American Express Platinum Travel Credit Cardⓘ is cheaper to hold with a lower annual fee of Rs 5,000 versus Rs 7,999 for Zenith.
- Choose American Express Platinum Travel Credit Cardⓘ if you want a simpler travel-focused card with domestic lounges and concierge. Pick Zenith Credit Cardⓘ if you want premium rewards, better forex rates, and international lounge access.
Side by Side
| Detail | American Express Platinum Travel Credit Cardⓘ | Zenith Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 5,000 | Rs 7,999 |
| Joining fee | Rs 5,000 | Rs 7,999 |
| Fee waiver on spend | None | None |
| Reward rate | 0.5% | 1% |
| Reward type | points | points |
| Domestic lounge | 8 per year | 8 per year |
| International lounge | None | 6 per year |
| Forex markup | 3.5% | 1.99% |
| Best suited for | travel, rewards, shopping | premium, travel, lounge, rewards, dining, shopping |
Rewards Compared
Spending Rs 10,000 on the American Express Platinum Travel Credit Cardⓘ earns Rs 50 in rewards at the base rate of 0.5%. This card does not specify category multipliers, so the reward rate is uniform. The welcome benefit offers 10,000 Membership Rewards Points but no direct cash value is given here. The reward type is points, which may be redeemable for travel or shopping.
In contrast, the Zenith Credit Cardⓘ provides Rs 100 back per Rs 10,000 spent at the base rate of 1%. It also offers 5% returns in dining and travel categories, translating to Rs 500 per Rs 10,000 spent in those categories. This makes it very lucrative for premium spenders focused on travel and dining. The welcome benefit includes Rs 1,000 worth of vouchers and 10,000 bonus reward points after Rs 1 lakh spend, enhancing early value.
Fees Compared
The American Express Platinum Travel Credit Cardⓘ charges Rs 5,000 each for joining and annual fees, with no fee waiver threshold. This means you pay these fees regardless of spend. To cover the Rs 5,000 annual fee purely through base rewards, you would need to spend about Rs 10 lakh annually.
The Zenith Credit Cardⓘ is more expensive with Rs 7,999 joining and annual fees, also without fee waivers. However, its higher reward rate means you only need to spend about Rs 8 lakh annually at base rates to cover the fee. The extra Rs 2,999 fee compared to Amex is offset by the higher returns if you spend heavily, with a break-even spend difference of approximately Rs 6 lakh.
Which One Should You Pick
Choose the American Express Platinum Travel Credit Cardⓘ if you want a straightforward travel card with domestic lounge access and concierge service at a lower annual fee. It suits moderate spenders who value the Amex brand and simpler rewards. Skip this card if you spend heavily on dining or international travel and want better forex rates.
The Zenith Credit Cardⓘ is ideal for premium users who spend significantly on dining and travel categories and want international lounge access plus a lower forex markup of 1.99%. It suits those who can meet the higher fee threshold and want maximum rewards. Skip Zenith if you prefer to avoid a high annual fee or do not spend enough to justify it.
Overall, Zenith Credit Cardⓘ wins for rewards and travel perks but costs more. American Express Platinum Travel Credit Cardⓘ is cheaper and simpler. Your choice depends on your spend pattern and lounge needs.
What to Check Before You Apply
- Verify if the domestic lounge visits require quarterly spend thresholds (Rs 1 lakh for Amex, Rs 20,000 for Zenith).
- Confirm the redemption value of points to ensure rewards deliver expected value.
- Understand the fee waiver math carefully, as neither card offers fee waivers on spend.
- Consider the forex markup rates and how often you travel internationally.
- Check which airports support the domestic and international lounges offered.

Comments
No comments yet
Be the first to share your experience with this card.