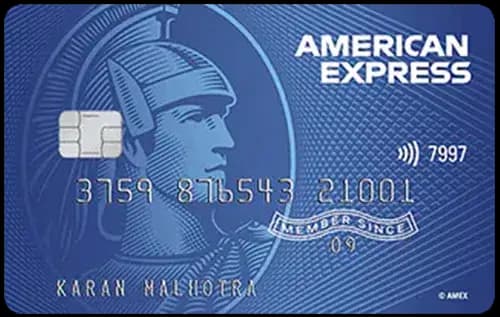
Quick Verdict
- For everyday spending, the IDFC HPCL First Power Plus Credit Cardⓘ wins with a higher base reward rate and strong category bonuses on fuel, groceries, and utilities.
- The IDFC HPCL First Power Plusⓘ also offers domestic lounge access, making it better for occasional lounge users, while the American Express Smartearn Credit Cardⓘ does not provide any lounge benefits.
- Both cards have nearly identical joining and annual fees, with the IDFC card requiring a higher spend for fee waiver but offering a slightly better break-even on rewards.
- Choose the Amex Smartearn card if you prefer online shopping rewards and a straightforward fee structure; pick the IDFC HPCL First Power Plus if you want higher rewards on fuel and groceries plus lounge access.
Side by Side
| Detail | American Express Smartearn Credit Cardⓘ | IDFC HPCL First Power Plus Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 495 | Rs 499 |
| Joining fee | Rs 495 | Rs 499 |
| Fee waiver on spend | Rs 1.50 lakh | |
| Reward rate | 0.5% base, 2.5% online | 0.75% base, 6.5% fuel, 5% grocery, 5% utilities |
| Reward type | Points | Points |
| Domestic lounge | None | 4 visits per year (Rs 20,000 monthly spend gate) |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | Shopping, first-card, rewards | Fuel, UPI-RuPay, grocery, lounge |
Rewards Compared
With a Rs 10,000 spend, the American Express Smartearn Credit Cardⓘ delivers Rs 50 back at its base rate, increasing to Rs 250 if the spend is online, reflecting its focus on e-commerce rewards. This makes it ideal for users who primarily shop online and want decent cashback in that category. By contrast, the IDFC HPCL First Power Plus Credit Cardⓘ earns Rs 75 at the base rate on general spending, a modest but meaningful bump over the Amex card. Its standout rewards are for fuel, groceries, and utilities, where it returns between Rs 500 and Rs 650 per Rs 10,000 spent, significantly higher than the Amex Smartearn’s general or category rates. This makes the IDFC card a much stronger option if your spend is concentrated in these everyday essentials.
Fees Compared
Both cards have very similar joining and annual fees: Rs 495 for the Amex Smartearn and Rs 499 for the IDFC HPCL First Power Plus. The IDFC card offers a fee waiver if you spend Rs 1.50 lakh annually, which translates to about Rs 12,500 per month. The Amex card does not offer a fee waiver on spend. While the IDFC card’s base reward rate is 0.75% versus 0.5% for Amex, the slight Rs 4 fee difference means you need to spend Rs 1,600 more annually on the IDFC card to cover that extra fee, which is a low threshold. For users spending above Rs 1.50 lakh a year, the IDFC card’s fee waiver makes it cheaper to hold with better rewards, while the Amex card is simpler but charges fees regardless of spend.
Which One Should You Pick
Choose the American Express Smartearn Credit Cardⓘ if you are a first-time credit card user or someone who spends mostly on online shopping. Its straightforward cashback on e-commerce and a modest joining fee make it an easy-to-understand option without complex fee waiver conditions. However, skip this if you want lounge access or higher rewards on everyday categories like fuel or groceries.
The IDFC HPCL First Power Plus Credit Cardⓘ is best suited for fuel buyers, grocery shoppers, and utility bill payers who want to maximize rewards in these categories and enjoy domestic lounge access. It also suits users comfortable with meeting a Rs 12,500 monthly spend to waive the annual fee. Avoid it if your spend is irregular or mostly outside fuel and groceries, or if you do not value lounge access.
Overall, if you want a rewards card with better category benefits and lounge access and expect to meet the fee waiver spend, the IDFC HPCL First Power Plus card is the better pick. If you want a simple, low-fee online shopping card and do not mind the annual fee, the American Express Smartearn card is a solid alternative.
What to Check Before You Apply
- Confirm if the Rs 1.50 lakh spend for fee waiver on the IDFC card fits your typical annual expenditure.
- Understand that the Amex card’s online category rewards require you to shop online to maximize returns.
- Check the redemption options and whether points convert efficiently to cash or vouchers for both cards.
- Be mindful that both cards charge a 3.5% forex markup on foreign transactions, which can add up on international spends.
- Verify the domestic lounge access on the IDFC card, including the Rs 20,000 monthly spend gate to unlock the visits.

Comments
No comments yet
Be the first to share your experience with this card.