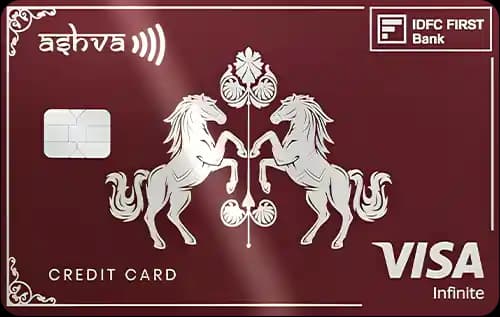
Quick Verdict
- The Standard Chartered Ultimate Credit Cardⓘ wins for everyday spend with a higher base reward rate of 3.33% compared to Ashva Credit Card’s 1.25%.
- Both cards offer similar domestic and international lounge access, but the Ultimate card’s quarterly and monthly lounge access structure and additional premium benefits give it a slight edge for travel and lounges.
- Ashva Credit Card is cheaper to hold with Rs 2,999 annual and joining fees versus Rs 5,000 each for the Ultimate card.
- Choose Ashva Credit Cardⓘ if you want a lower fee card with good travel perks and dining rewards. Pick Standard Chartered Ultimate Credit Cardⓘ if you prioritize higher rewards on all spends and premium insurance benefits despite the higher fees.
Side by Side
| Detail | Ashva Credit Cardⓘ | Standard Chartered Ultimate Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 2,999 | Rs 5,000 |
| Joining fee | Rs 2,999 | Rs 5,000 |
| Fee waiver on spend | None specified | None specified |
| Reward rate | 1.25% base; 2.5% dining, travel | 3.33% base |
| Reward type | points | points |
| Domestic lounge | 8 per year | 8 per year |
| International lounge | 4 per year | 4 per year |
| Forex markup | 1.5% | 2% |
| Best suited for | premium, travel, lounge, rewards, shopping | rewards, travel, lounge, premium, shopping |
Rewards Compared
The Ashva Credit Cardⓘ offers a base reward return of Rs 125 on Rs 10,000 spent, rising to Rs 250 for dining and travel categories. This makes it attractive for users who spend heavily in these segments, as the effective reward rate doubles to 2.5%. The card’s rewards are points-based, and the welcome benefit of up to 7,500 points can add value if fully utilized.
In contrast, the Standard Chartered Ultimate Credit Cardⓘ delivers a strong flat base reward of Rs 333 on Rs 10,000 spent, which is more than double Ashva’s base return. It does not specify category bonuses but compensates with a high base rate and additional benefits like 5% cashback on duty-free spends. The welcome benefit includes 6,000 rewards redeemable for shopping vouchers or charity, which may appeal to socially conscious spenders.
Fees Compared
Ashva Credit Cardⓘ charges Rs 2,999 each for joining and annual fees, with no stated fee waiver on spend. The card requires about Rs 2.40 lakh in annual spend to cover its fee through base rewards alone. Its forex markup is a modest 1.5%, making it cheaper for foreign currency transactions.
The Standard Chartered Ultimate Credit Cardⓘ demands higher fees at Rs 5,000 for both joining and annual, with no fee waiver threshold mentioned. However, its superior reward rate means the break-even spend to cover fees is approximately Rs 1.50 lakh, significantly lower than Ashva’s. The forex markup is 2%, slightly higher but offset by the card’s insurance and lounge benefits.
The head-to-head comparison shows the Ultimate card’s extra Rs 2,001 fee is justified if you can spend an additional Rs 96,202 annually to benefit from the higher reward rate.
Which One Should You Pick
Choose the Ashva Credit Cardⓘ if you prefer a card with lower fees, good travel and dining rewards, and premium benefits like free stays at ITC Hotels and concierge services. It suits premium spenders who value lounge access and luxury hotel perks but have moderate overall spend.
Opt for the Standard Chartered Ultimate Credit Cardⓘ if you are a high spender looking for maximum rewards on all purchases, comprehensive travel insurance, and family benefits like lifetime free supplementary cards. It is ideal for those who can comfortably meet the higher fee and spend thresholds to unlock its full value.
Skip Ashva Credit Cardⓘ if you want the highest possible rewards on everyday spend or if you spend heavily abroad and want extensive insurance coverage. Avoid the Ultimate cardⓘ if you are fee-sensitive or have lower monthly spends that won’t justify the higher fees.
What to Check Before You Apply
- Verify if the lounge access caps (8 domestic, 4 international per year) meet your travel frequency.
- Confirm the redemption value of points and any restrictions on converting or using them.
- Calculate the monthly spend needed to justify the annual fee, especially if no fee waiver is offered.
- Consider the forex markup if you travel internationally frequently and how it impacts overall costs.

Comments
No comments yet
Be the first to share your experience with this card.