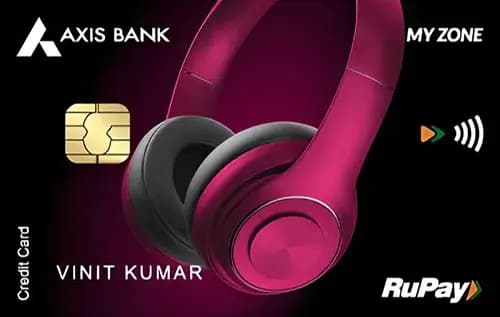
Quick Verdict
- For everyday spend, the Axis Bank My Zone Credit Cardⓘ wins with a higher base reward rate and exceptional dining rewards.
- For travel or lounge access, the My Zone card also leads, offering four domestic lounge visits per year, unlike the Neo card which has none.
- The Axis Bank Neo Credit Cardⓘ is cheaper to hold with no joining or annual fees, making it ideal for budget-conscious users.
- Choose the My Zone card if you spend heavily on dining and value lounge access; pick the Neo card if you want a free card with decent rewards on utilities and online spend.
Side by Side
| Detail | Axis Bank My Zone Credit Cardⓘ | Axis Bank Neo Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 500 | Nil (lifetime free) |
| Joining fee | Rs 500 | Nil (lifetime free) |
| Fee waiver on spend | None specified | None specified |
| Reward rate | 0.4% base | 0.2% base |
| Reward type | Points | Points |
| Domestic lounge | 4 per year | None |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | Dining, first-card, cashback, shopping | First-card, shopping, cashback, dining |
Rewards Compared
The Axis Bank My Zone Credit Cardⓘ offers a base reward of Rs 40 on Rs 10,000 spent, which means it returns 0.4% in points. Its standout feature is the 15% reward rate on dining, translating to Rs 1,500 back on Rs 10,000 spent in that category. Online spend earns 5% back, or Rs 500 per Rs 10,000. This makes it highly attractive for frequent diners and online shoppers who want a significant boost in reward value.
The Axis Bank Neo Credit Cardⓘ has a lower base reward rate of 0.2%, giving Rs 20 per Rs 10,000 spent. However, it competes well in specific categories such as online and utilities, both offering 5% rewards or Rs 500 per Rs 10,000. This card suits those who want solid returns on everyday utility and online bill payments without paying any fees.
Fees Compared
The My Zone card comes with a joining fee and an annual fee of Rs 500 each. There is no explicit fee waiver based on spend, meaning these fees are effectively fixed costs. To cover the Rs 500 annual fee purely through base rewards, a cardholder must spend Rs 1,25,000 annually at the base rate. However, the head-to-head analysis shows that because the My Zone card’s base rate is double that of the Neo card, you would need to spend about Rs 2,50,000 more on the My Zone card's base rate to justify the fee difference of Rs 500 compared to the Neo card.
The Neo card is completely free for life with no joining or annual fees, making it a risk-free option for users unwilling to pay fees upfront. This fee advantage makes it easier to maintain without worrying about break-even thresholds.
Which One Should You Pick
Pick the Axis Bank My Zone Credit Cardⓘ if you regularly spend on dining and online shopping and value domestic lounge access. The 15% dining rewards and four annual domestic lounge visits provide strong perks for food lovers and occasional travelers. It is also suitable for first-time credit card users who want a mid-tier card with some premium features. Avoid this card if you spend less than Rs 1,25,000 annually or dislike paying fees.
The Axis Bank Neo Credit Cardⓘ is best for those who want a free, simple card with decent cashback on utilities and online spend. It suits budget-conscious consumers or those new to credit cards who want to avoid fees entirely while earning moderate rewards. It is less ideal for frequent diners or travelers seeking lounge access or higher rewards.
In final analysis, if you want fee-free convenience and a decent reward on utilities and online spend, go for the Neo card. But if you can justify the Rs 500 fees with your dining and online spend, the My Zone card offers stronger rewards and lounge benefits.
What to Check Before You Apply
- Confirm whether the Rs 50,000 quarterly spend gate for domestic lounge access on the My Zone card fits your spend pattern.
- Check the value and expiry of your reward points, especially since the My Zone card uses points and the Neo card’s cashback benefits may differ.
- Evaluate the fee waiver calculations carefully if you consider the My Zone card, as no explicit waivers are specified.
- Both cards charge a 3.5% forex markup on foreign currency transactions, which is standard but high for frequent international travelers.
- Verify the locations and availability of domestic lounges offered by the My Zone card to ensure they match your travel routes.

Comments
No comments yet
Be the first to share your experience with this card.