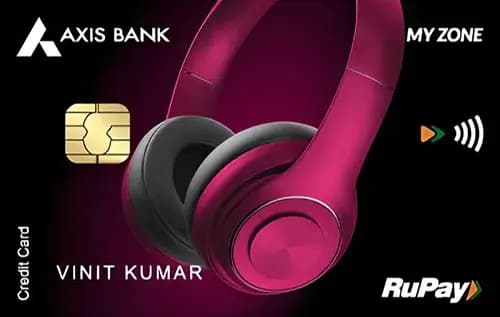
Quick Verdict
- For everyday spend, the Axis Bank Privilege Credit Cardⓘ wins with a higher base reward rate of 0.8% versus 0.4% on the My Zone.
- When it comes to travel and lounges, Privilege again leads with 8 domestic lounge visits per year compared to 4 for My Zone.
- The Axis Bank My Zone Credit Cardⓘ is cheaper to hold, with both joining and annual fees at Rs 500, versus Rs 1,500 each for Privilege.
- Choose My Zoneⓘ if you want a low-fee card with strong dining rewards; pick Privilegeⓘ if you prioritize higher overall rewards and lounge access despite higher fees.
Side by Side
| Detail | Axis Bank My Zone Credit Cardⓘ | Axis Bank Privilege Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 500 | Rs 1,500 |
| Joining fee | Rs 500 | Rs 1,500 |
| Fee waiver on spend | Rs 2.50 lakh | |
| Reward rate | 0.4% (base), 15% dining, 5% online | 0.8% (base), 2% online |
| Reward type | points | points |
| Domestic lounge | 4 per year | 8 per year |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | dining, first-card, cashback, shopping | rewards, lounge, first-card, travel, shopping |
Rewards Compared
The Axis Bank My Zone Credit Cardⓘ offers Rs 40 back per Rs 10,000 spent at the base level, which is modest but bolstered heavily in categories like dining where it returns Rs 1,500 on Rs 10,000 spent, and online shopping with Rs 500 back. This makes My Zoneⓘ attractive for users who spend significantly on dining and online purchases, translating to substantial rewards in those categories.
In contrast, the Axis Bank Privilege Credit Cardⓘ doubles the base reward rate to Rs 80 per Rs 10,000 spent, making it a better choice for general spenders who want a consistent return across categories. However, its category-specific rewards are less generous, offering just Rs 200 per Rs 10,000 on online spends. Privilegeⓘ thus suits users looking for a higher flat rate and enhanced lounge benefits rather than category-heavy rewards.
Fees Compared
The Axis Bank My Zone Credit Cardⓘ charges a joining and annual fee of Rs 500 each, with no fee waiver on spend. Its break-even spend to cover the annual fee at base rates is approximately Rs 1.25 lakh annually. This low fee structure is ideal for moderate spenders or those who prioritize dining rewards over fee savings.
The Axis Bank Privilege Credit Cardⓘ imposes Rs 1,500 for both joining and annual fees, but offers a fee waiver on Rs 2.50 lakh annual spend (around Rs 20,833 monthly). The break-even spend for its base rate to offset fees is about Rs 1.88 lakh annually. The extra Rs 1,000 fee compared to My Zoneⓘ requires Rs 2.50 lakh in additional spend to justify, making it more suitable for high spenders who can leverage the waiver and premium benefits.
Which One Should You Pick
If you primarily spend on dining and online shopping and want a low-cost card with good category rewards, the Axis Bank My Zone Credit Cardⓘ will serve you well. It is also suited for first-time credit card users looking for straightforward cashback benefits without hefty fees. However, skip this card if you want broader rewards or lounge access.
The Axis Bank Privilege Credit Cardⓘ is tailored for users who spend heavily across various categories, desire superior base rewards, and value lounge access. Its higher fees are justifiable if you can meet the waiver threshold and make use of its premium benefits. Avoid this card if your spend is low or you do not utilize lounges, as the fees may outweigh the benefits.
Overall, pick My Zoneⓘ for affordable, category-heavy rewards and Privilegeⓘ for upscale rewards and lounge privileges.
What to Check Before You Apply
- Confirm quarterly spend gates for domestic lounges of Rs 50,000 to avoid surprises on access.
- Verify redemption options and values for points, especially since both cards use points but may differ in third-party rules.
- Understand the fee waiver math: Privilege requires Rs 2.50 lakh annual spend to waive fees, whereas My Zone has no waiver.
- Remember the forex markup of 3.5% on both cards can be expensive for foreign transactions.
- Check which airports the domestic lounges cover to ensure they match your travel patterns.

Comments
No comments yet
Be the first to share your experience with this card.