Quick Verdict
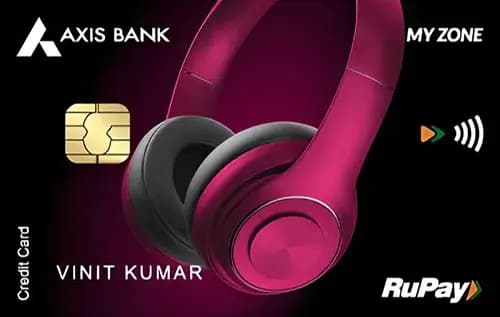
- Axis Bank My Zone Credit Cardⓘ wins for everyday spend thanks to a higher base reward rate and standout dining rewards.
- Neither card offers international lounge access, but Axis Bank My Zone Credit Cardⓘ provides limited domestic lounge visits.
- Both cards have equal joining and annual fees, though HDFC Bank Freedom Credit Cardⓘ offers an annual fee waiver on a lower spend.
- Choose Axis Bank My Zone Credit Cardⓘ if you prioritize dining rewards and occasional lounge access; pick HDFC Bank Freedom Credit Cardⓘ if you want a straightforward cashback card with a lower waiver threshold.
Side by Side
| Detail | Axis Bank My Zone Credit Card | HDFC Bank Freedom Credit Card |
|---|---|---|
| Annual fee | Rs 500 | Rs 500 |
| Joining fee | Rs 500 | Rs 500 |
| Fee waiver on spend | None | Rs 50,000 (Rs 4,167 per month) |
| Reward rate | 0.4% base, 15% dining, 5% online | 0.33% base, 3.33% online |
| Reward type | points | points |
| Domestic lounge | 4 per year (Rs 50,000 quarterly spend gate) | None |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | dining, first-card, cashback, shopping | first-card, cashback, shopping |
Rewards Compared
The Axis Bank My Zone Credit Cardⓘ delivers Rs 40 back on Rs 10,000 spent at its base rate of 0.4%. This card significantly shines in dining, offering Rs 1,500 back per Rs 10,000 spent, a massive jump compared to its base rate. Online shopping also benefits from a 5% category rate translating to Rs 500 back per Rs 10,000, making this card very rewarding for lifestyle spends. The heavy skew towards dining rewards makes it ideal for users who frequently eat out or order food.
The HDFC Bank Freedom Credit Cardⓘ offers Rs 33 per Rs 10,000 at its base rate of 0.33%, slightly lower overall compared to Axis Bank My Zone Credit Cardⓘ. Its category boost is focused solely on online spends at 3.33%, providing Rs 333 back per Rs 10,000. This is a modest improvement over the base rate and much less generous than Axis Bank My Zone Credit Cardⓘ’s category rewards. The Freedom card suits users who want steady cashback on everyday purchases without specific category dependence.
Fees Compared
Both cards have identical joining and annual fees of Rs 500 each. However, the HDFC Bank Freedom Credit Cardⓘ offers an annual fee waiver on a spend of Rs 50,000 per year, which breaks down to Rs 4,167 monthly. This makes the Freedom card cheaper to hold if you can meet this relatively low waiver threshold. Axis Bank My Zone Credit Cardⓘ does not provide a fee waiver, meaning you must pay the Rs 500 annual fee regardless of spend.
Looking at break-even spends, the Axis Bank My Zone Credit Cardⓘ requires about Rs 1,25,000 annual spend at base rates to cover the fee, whereas HDFC Freedom demands Rs 1,51,515 at base rates. This difference reflects the My Zone’s higher base reward rate. However, factoring in the fee waiver, Freedom becomes more economical for moderate spenders.
Which One Should You Pick
Choose the Axis Bank My Zone Credit Cardⓘ if you are a frequent diner or enjoy shopping and online purchases with a taste for better rewards in these categories. Its domestic lounge access perk adds value for occasional travelers within India. This card fits well as a first credit card for those who want strong category rewards and are comfortable with an annual fee that is not waived.
The HDFC Bank Freedom Credit Cardⓘ suits users looking for a simple, no-fuss cashback card with a lower fee waiver threshold. If you prefer to avoid annual fees by spending Rs 50,000 annually or more and want straightforward rewards primarily on online spends, this is a sound choice. It is ideal for beginners or those who want to keep costs low.
In conclusion, Axis Bank My Zone Credit Cardⓘ is the winner for category rewards and lounge benefits, while HDFC Bank Freedom Credit Cardⓘ wins on fee waiver terms and simplicity. Skip My Zone if you want fee waivers or international lounges, and skip Freedom if you prioritize dining rewards or domestic lounges.
What to Check Before You Apply
- Confirm if your dining or online spend habits match the category rates to maximize rewards.
- Understand redemption rules and point expiry to avoid losing earned rewards.
- Carefully evaluate the fee waiver math, especially for HDFC Freedom’s Rs 50,000 annual spend requirement.
- Both cards charge 3.5% forex markup; consider alternatives if you do significant foreign currency transactions.
- For Axis Bank My Zone Credit Cardⓘ, track your Rs 50,000 quarterly spend gate to use the 4 free domestic lounges.

Comments
No comments yet
Be the first to share your experience with this card.