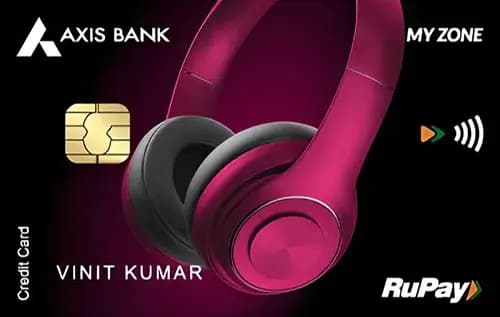
Quick Verdict
- For everyday spend, the HDFC Bank Rupay IRCTC Credit Cardⓘ offers a slightly better base reward rate of 0.5% compared to 0.4% on the Axis Bank My Zone Credit Cardⓘ.
- When it comes to travel benefits and lounge access, the Rupay IRCTC card leads with 8 domestic lounge visits annually versus 4 on the Axis My Zone card, and a higher quarterly spend gate for lounges.
- The Axis Bank My Zone card is cheaper to hold with a flat Rs 500 annual fee and joining fee, while the Rupay IRCTC card has no annual fee but requires Rs 1.5 lakh annual spend to waive the joining fee effectively.
- Pick the Axis Bank My Zone card if you prioritize dining rewards and a simple fee structure. Choose the HDFC Rupay IRCTC card if you want better base rewards and more domestic lounge access, especially for travel-centric spending.
Side by Side
| Detail | Axis Bank My Zone Credit Cardⓘ | HDFC Bank Rupay IRCTC Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 500 | Nil (lifetime free) |
| Joining fee | Rs 500 | Rs 500 |
| Fee waiver on spend | None | Rs 1.5 lakh annually |
| Reward rate | 0.4% base | 0.5% base |
| Reward type | points | points |
| Domestic lounge | 4 per year | 8 per year |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | dining, first-card, cashback, shopping | travel, upi-rupay, first-card |
Rewards Compared
The Axis Bank My Zone Credit Cardⓘ delivers Rs 40 in rewards per Rs 10,000 spent at the base 0.4% rate, which can jump notably to Rs 1,500 for dining and Rs 500 for online shopping categories. This makes it an excellent choice for users who spend heavily on dining and online purchases. The card also offers a free SonyLiv subscription worth Rs 1,499 as a welcome benefit adding to its value proposition.
On the other hand, the HDFC Bank Rupay IRCTC Credit Cardⓘ yields Rs 50 per Rs 10,000 spent at the base 0.5% rate, a modest but clear advantage over the Axis card’s base rewards. Its category bonuses are travel at Rs 500 per Rs 10,000 and UPI payments at Rs 100 per Rs 10,000, reflecting its travel and digital payments orientation. The Rupay IRCTC card also offers a welcome Amazon voucher worth Rs 500, which is lower than Axis’s welcome benefit.
Fees Compared
The Axis Bank My Zone card asks for Rs 500 as both joining and annual fees with no waiver conditions, making it straightforward for users who want to know their cost upfront. To cover the Rs 500 annual fee just by base rewards, a spend of about Rs 1.25 lakh is needed. There is no fee waiver on spend, so this cost is fixed each year regardless of usage.
The HDFC Rupay IRCTC card has a Rs 500 joining fee but no annual fee, effectively making it "lifetime free" after payment of the joining fee. The joining fee can be waived if you spend Rs 1.5 lakh annually (or Rs 12,500 per month), which means active users who meet this threshold never pay any fees. This spend gate may be burdensome for moderate spenders but attractive for frequent travelers or heavy digital payers.
Which One Should You Pick
Choose the Axis Bank My Zone Credit Cardⓘ if you are a casual spender who enjoys dining and online shopping perks, want a simple fixed fee, and value the substantial welcome benefit like the SonyLiv subscription. It is also suited for first-time credit card users who want basic cashback rewards and some lounge access without complex spend conditions.
Pick the HDFC Bank Rupay IRCTC Credit Cardⓘ if you are a traveler or someone who heavily uses UPI payments and can comfortably spend Rs 12,500 monthly to waive fees. The higher base reward and doubled domestic lounge access make it ideal for frequent travelers. It also suits those looking for a no-annual-fee card after the joining fee is managed.
In conclusion, skip the Axis card if your spending is mostly travel-related or you want more lounge access. Avoid the Rupay IRCTC card if you cannot meet the Rs 1.5 lakh annual spend waiver threshold or if you prefer a guaranteed low annual fee.
What to Check Before You Apply
- Lounge access is capped quarterly with spend gates: Rs 50,000 per quarter for Axis and Rs 75,000 for HDFC Rupay IRCTC.
- Redemption value is fixed as points with no issuer-verified third-party sources; check specific usage terms for rewards.
- Fee waiver on the Rupay IRCTC card is based on a high annual spend of Rs 1.5 lakh, which might be hard for some to reach.
- Both cards charge a 3.5% forex markup, standard for Indian credit cards, so not ideal for frequent foreign currency use.
- Domestic lounge access is limited and international lounge benefits are absent on both cards.

Comments
No comments yet
Be the first to share your experience with this card.