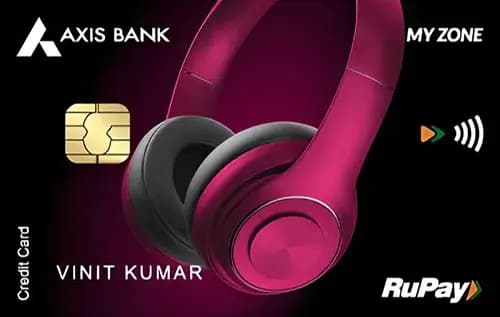
Quick Verdict
- For everyday spend, the IDFC HPCL First Power Plus Credit Cardⓘ wins with a higher base reward rate of 0.75% compared to 0.4% on the Axis Bank My Zone Credit Cardⓘ.
- For travel and lounge access, both cards offer 4 domestic lounge visits per year, but the Axis Bank My Zone has a higher quarterly spend gate of Rs 50,000 versus Rs 20,000 monthly on the IDFC HPCL card.
- The cheaper card to hold depends on your spend: the IDFC HPCL card offers an annual fee waiver with Rs 1.5 lakh annual spend, while Axis Bank’s fees are low but have no waiver.
- Pick the Axis Bank My Zone Credit Cardⓘ if you prioritize dining rewards and welcome benefits like a free SonyLiv subscription, and the IDFC HPCL First Power Plus Credit Cardⓘ if you are a fuel or grocery spender looking for better base rewards and fee waiver flexibility.
Side by Side
| Detail | Axis Bank My Zone Credit Cardⓘ | IDFC HPCL First Power Plus Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 500 | Rs 499 |
| Joining fee | Rs 500 | Rs 499 |
| Fee waiver on spend | Rs 1.50 lakh | |
| Reward rate | 0.4% | 0.75% |
| Reward type | points | points |
| Domestic lounge | 4 per year | 4 per year |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | dining, first-card, cashback, shopping | fuel, upi-rupay, grocery, lounge |
Rewards Compared
The Axis Bank My Zone Credit Cardⓘ offers Rs 40 back on Rs 10,000 spent at the base rate of 0.4%. However, it shines in dining with an effective 15% return, translating to Rs 1,500 back on a Rs 10,000 dining spend. The online category also earns a competitive 5%, or Rs 500 per Rs 10,000 spent. This card is clearly tailored for users who spend heavily on dining and online shopping.
In contrast, the IDFC HPCL First Power Plus Credit Cardⓘ delivers Rs 75 back on a general Rs 10,000 spend at 0.75% base rewards, nearly double that of the Axis Bank card. Its categories focus on fuel (6.5%, Rs 650 per Rs 10,000), grocery (5%, Rs 500), and utilities (5%, Rs 500), making it more attractive for essential and regular spends. The broader category coverage for everyday expenses gives it an edge in consistent rewards accumulation.
Fees Compared
Both cards charge similar annual and joining fees: Rs 500 on Axis Bank My Zone and Rs 499 on the IDFC HPCL First Power Plus. The IDFC HPCL card offers a fee waiver on annual spend of Rs 1.5 lakh, equating to Rs 12,500 per month, making it ideal for higher spenders who want to avoid fees. Axis Bank My Zone has no fee waiver, so the Rs 1,000 combined first-year fee applies regardless of spend.
The break-even spend for the Axis Bank card to cover fees at its base rate is Rs 1.25 lakh, whereas the IDFC HPCL card requires only about Rs 66,533 due to its higher base rewards. This means the IDFC HPCL card is more cost-effective for mid-range spenders looking to offset fees with rewards.
Which One Should You Pick
Choose the Axis Bank My Zone Credit Cardⓘ if you prioritize dining rewards, enjoy online shopping, and want a card with a modest fee and a welcome benefit like a free SonyLiv subscription. It suits first-time cardholders or those focused on lifestyle spends who do not meet high fee waiver thresholds.
Pick the IDFC HPCL First Power Plus Credit Cardⓘ if you spend regularly on fuel, groceries, and utilities, and can maintain Rs 1.5 lakh annual spend for fee waivers. Its higher base reward rate and flexible category coverage make it ideal for essential and repeat spends, especially for frequent HPCL fuel users.
In conclusion, if you want a higher reward rate and fee waiver potential, go for the IDFC HPCL First Power Plus Credit Cardⓘ. Skip the Axis Bank My Zone Credit Cardⓘ if you do not spend enough on dining or online shopping. Conversely, skip the IDFC card if you do not meet the fee waiver spend and want a simpler fee structure.
What to Check Before You Apply
- Confirm the quarterly and monthly spend gates for lounge access to ensure your usage will qualify.
- Understand the redemption value of points for both cards, especially since reward types are points and values may vary.
- Check the monthly spend needed to waive fees on the IDFC HPCL card and whether that matches your budget.
- Be aware of the 3.5% forex markup on foreign transactions and factor that into your international usage plans.
- Verify the list of domestic lounges accessible to avoid disappointment at your preferred airports.

Comments
No comments yet
Be the first to share your experience with this card.