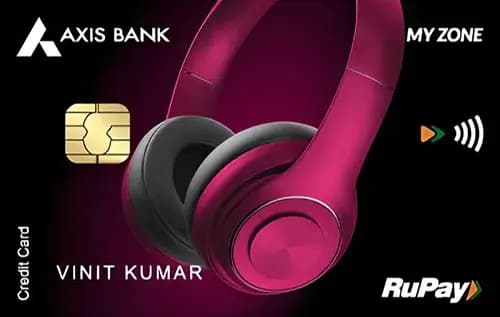
Quick Verdict
- For everyday spend, the IndusInd Bank Tiger Credit Cardⓘ wins with a higher base reward rate of 1%, returning Rs 100 on Rs 10,000 spent.
- For dining and online shopping, the Axis Bank My Zone Credit Cardⓘ offers superior category rewards, especially 15% on dining.
- The IndusInd Tiger card is cheaper to hold with no joining or annual fees, while the Axis Bank My Zone card charges Rs 500 for both.
- Choose the Axis Bank My Zone cardⓘ if you prioritize dining rewards and a welcome SonyLiv subscription; pick the IndusInd Tiger cardⓘ if you want a lifetime free card with decent rewards and some travel perks like golf access.
Side by Side
| Detail | Axis Bank My Zone Credit Cardⓘ | IndusInd Bank Tiger Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 500 | Nil (lifetime free) |
| Joining fee | Rs 500 | Nil (lifetime free) |
| Fee waiver on spend | Not recorded | Not recorded |
| Reward rate | 0.4% base | 1% base |
| Reward type | points | points |
| Domestic lounge | 4 per year | 4 per year |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | dining, first-card, cashback, shopping | lifetime-free, upi-rupay, rewards, lounge, travel |
Rewards Compared
The Axis Bank My Zone Credit Cardⓘ offers a base reward rate of 0.4%, which means Rs 40 back on Rs 10,000 spent. However, it shines in specific categories such as dining, where it offers an effective return of 15%, translating to Rs 1,500 on Rs 10,000 spent, and 5% on online purchases, or Rs 500 on Rs 10,000. This makes it a strong contender for users who spend heavily in these categories and want to maximize rewards on dining and online shopping.
In contrast, the IndusInd Bank Tiger Credit Cardⓘ provides a straightforward 1% base reward rate, giving Rs 100 back on Rs 10,000 spent. Its category rewards are more modest, with 2.5% on online spending (Rs 250 on Rs 10,000) and 1% on UPI transactions (Rs 100 on Rs 10,000). This card suits users who prefer consistent rewards across all spends without focusing on specific categories.
Fees Compared
The Axis Bank My Zone cardⓘ charges Rs 500 as both joining and annual fees. There is no explicit fee waiver threshold mentioned, so these fees are payable upfront and annually. The card’s derived spend to cover the annual fee at base rate is Rs 1,25,000, meaning you need to spend about Rs 1.25 lakh annually at the base rate to offset the Rs 500 fee through rewards alone.
The IndusInd Tiger cardⓘ is lifetime free with no joining or annual fees, making it a cost-effective option for users who want to avoid fees altogether. This no-fee structure makes it attractive for low to moderate spenders or those who dislike fee-based cards.
Which One Should You Pick
Choose the Axis Bank My Zone Credit Cardⓘ if you are a first-time credit card user or someone who spends heavily on dining and online shopping. The high category reward rates and the welcome benefit of a free SonyLiv subscription worth Rs 1,499 add value for lifestyle-focused users. However, be prepared to pay the joining and annual fees and meet the quarterly Rs 50,000 spend gate to access domestic lounges.
The IndusInd Bank Tiger Credit Cardⓘ is ideal for users who want a no-fee, straightforward rewards card with a higher base reward rate. It suits those who use UPI frequently, value lounge access with a lower Rs 40,000 quarterly spend gate, and appreciate additional perks like golf access. It is also a good choice for travelers who want a simple card without worrying about fees.
In conclusion, if you prioritize category rewards and don’t mind fees, the Axis Bank My Zone cardⓘ is the better pick. If you want a fee-free card with a solid base reward rate and some travel perks, the IndusInd Tiger cardⓘ wins. Fee-sensitive users should skip the Axis Bank My Zone cardⓘ, while those seeking premium dining rewards may skip the IndusInd Tiger cardⓘ.
What to Check Before You Apply
- Confirm the quarterly spend gates for lounge access: Rs 50,000 for Axis Bank My Zone and Rs 40,000 for IndusInd Tiger.
- Understand the redemption value of points as both cards use points but with different reward structures.
- Verify the fee waiver conditions if any, as only the Axis Bank My Zone cardⓘ mentions fees explicitly.
- Be aware of the 3.5% forex markup on both cards for foreign currency transactions.
- Check the availability and locations of domestic lounges accessible with each card.

Comments
No comments yet
Be the first to share your experience with this card.