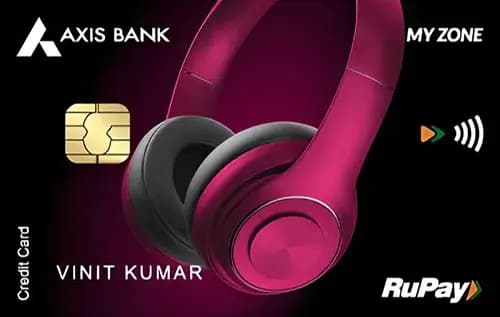
Quick Verdict
- For everyday spend, the Standard Chartered Rewards Credit Cardⓘ wins with a higher base reward rate of 1% compared to 0.4% on the Axis Bank My Zone Credit Cardⓘ.
- The Axis Bank My Zone Credit Cardⓘ offers superior rewards for dining spends, making it a better choice for food lovers.
- The Axis Bank card is cheaper to hold with a total initial cost of Rs 1,000 (joining plus annual fee), while Standard Chartered charges Rs 1,000 annually but no joining fee.
- Choose the Axis Bank My Zone if you want strong dining rewards and a low-cost card with some domestic lounge access. Opt for Standard Chartered Rewards if you want higher rewards on all spends and a fee waiver on Rs 1 lakh annual spend.
Side by Side
| Detail | Axis Bank My Zone Credit Cardⓘ | Standard Chartered Rewards Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 500 | Rs 1,000 |
| Joining fee | Rs 500 | Nil (lifetime free) |
| Fee waiver on spend | None | Rs 1.00 lakh |
| Reward rate | 0.4% base | 1% base |
| Reward type | Points | Points |
| Domestic lounge | 4 per year | 4 per year |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | Dining, first-card, cashback, shopping | Rewards, dining, first-card, shopping, lounge |
Rewards Compared
The Axis Bank My Zone Credit Cardⓘ offers Rs 40 back per Rs 10,000 spent at the base rate. However, for dining spends, it shines with an effective return of Rs 1,500 per Rs 10,000, which is exceptional. Online spends earn Rs 500 per Rs 10,000, also above the base rate. This card is ideal if your spending is concentrated in dining or online categories where the rewards multiply significantly.
On the other hand, the Standard Chartered Rewards Credit Cardⓘ delivers a more consistent reward rate of Rs 100 per Rs 10,000 spent across all categories, including dining and online, both at 4%. Although its category rates are lower than Axis Bank My Zone’s dining and online rates, the higher base rate means you earn more on general spends. This card suits those who want straightforward rewards without category restrictions.
Fees Compared
The Axis Bank My Zone Credit Cardⓘ charges a joining fee of Rs 500 and an annual fee of Rs 500, totaling Rs 1,000 upfront. There is no fee waiver available regardless of spend. To cover the Rs 1,000 fee purely through base rewards at 0.4%, you would need to spend about Rs 1.25 lakh annually.
In contrast, the Standard Chartered Rewards Credit Cardⓘ has no joining fee but an annual fee of Rs 1,000. This fee is waived if you spend Rs 1 lakh in a year, which breaks down to about Rs 8,333 per month. Since its base reward rate is 1%, spending Rs 1 lakh yields Rs 1,000 in rewards, just enough to offset the fee. The break-even point for the extra Rs 500 fee charged by Axis Bank to match Standard Chartered’s higher base rate is Rs 83,333 additional spend.
Which One Should You Pick
Choose the Axis Bank My Zone Credit Cardⓘ if you are a casual spender focused on dining and online shopping and want a low-cost card with some domestic lounge access. It is also suitable for first-time credit card users who appreciate category-specific rewards and a welcome benefit like a free SonyLiv subscription.
Pick the Standard Chartered Rewards Credit Cardⓘ if you want higher rewards on every rupee spent, prefer a no-joining-fee card, and can meet the Rs 1 lakh annual spend threshold to waive the annual fee. It is ideal for shoppers who want simple, consistent rewards and lounge access.
Overall, if you spend heavily in dining and online categories and want to maximize rewards there, Axis Bank My Zone wins. For broader rewards and fee flexibility, Standard Chartered Rewards is the better pick. Skip Axis Bank My Zone if you want more universal rewards or fee waivers. Skip Standard Chartered Rewards if you spend less than Rs 8,333 per month or want dining rewards that stand out.
What to Check Before You Apply
- Confirm the quarterly Rs 50,000 spend gate for domestic lounge access on both cards.
- Check the actual redemption value of points as it varies and affects your effective reward rate.
- Understand fee waiver conditions clearly, especially the monthly spend needed on Standard Chartered Rewards.
- Beware of the 3.5% forex markup on foreign currency spends with both cards.
- Verify which airports and lounges are accessible under the domestic lounge benefit.

Comments
No comments yet
Be the first to share your experience with this card.