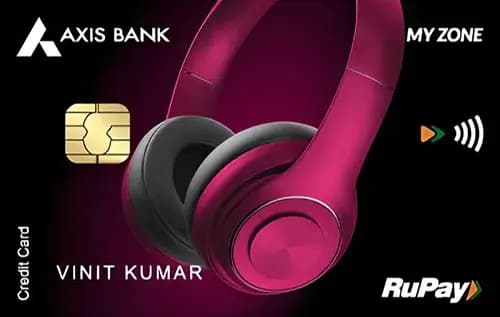
Quick Verdict
- For everyday spend, the Yes Bank Rupay Credit Cardⓘ offers a higher base reward rate, making it the better choice.
- The Axis Bank My Zone Credit Cardⓘ excels in dining and online categories, offering superior rewards in those specific spends.
- In terms of cost, Yes Bank Rupay is cheaper to hold with no joining or annual fees, while Axis Bank My Zone charges Rs 500 for both.
- Choose Axis Bank My Zone if you want strong dining rewards and a welcome SonyLiv subscription; pick Yes Bank Rupay if you prefer no fees and solid rewards on groceries and UPI spends.
Side by Side
| Detail | Axis Bank My Zone Credit Cardⓘ | Yes Bank Rupay Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 500 | Nil (lifetime free) |
| Joining fee | Rs 500 | Nil (lifetime free) |
| Fee waiver on spend | None | Rs 75,000 annually |
| Reward rate | 0.4% base | 1% base |
| Reward type | points | points |
| Dining category rate | 15% (Rs 1,500 per Rs 10,000) | 3% (Rs 300 per Rs 10,000) |
| Online category rate | 5% (Rs 500 per Rs 10,000) | Not recorded |
| Grocery category rate | Not recorded | 3% (Rs 300 per Rs 10,000) |
| UPI category rate | Not recorded | 1% (Rs 100 per Rs 10,000) |
| Domestic lounge access | 4 per year (Rs 50,000 quarterly spend gate) | 4 per year (Rs 50,000 quarterly spend gate) |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | dining, first-card, cashback, shopping | upi-rupay, rewards, grocery, first-card, shopping |
Rewards Compared
The Axis Bank My Zone Credit Cardⓘ returns Rs 40 on a Rs 10,000 generic spend at its base rate of 0.4%, but it shines in dining where it offers Rs 1,500 back for the same spend. This 15% effective return is outstanding for food lovers. Online shopping also benefits from a 5% return, or Rs 500 per Rs 10,000 spent.
Conversely, the Yes Bank Rupay Credit Cardⓘ provides a more generous 1% base reward, equating to Rs 100 per Rs 10,000, making it better for everyday spend without category restrictions. Its category rewards include 3% on groceries and dining (Rs 300 each per Rs 10,000), and 1% on UPI transactions. While it does not match Axis Bank My Zone’s dining rate, its overall base return is higher and more evenly spread across categories.
Fees Compared
The Axis Bank My Zone card demands Rs 500 as both joining and annual fees, with no waiver on spending. It requires an annual spend of about Rs 1,25,000 at the base rate to offset the fee cost. The Yes Bank Rupay card is lifetime free with zero joining and annual fees, though it has a fee waiver threshold of Rs 75,000 annual spend which applies only if fees were levied, but in this case, fees are nil.
Therefore, in pure fee terms, Yes Bank Rupay is cheaper to hold indefinitely, giving it an edge for cost-conscious users. Axis Bank My Zone’s fees are justified only if the user can maximize dining rewards sufficiently to cover the Rs 500 fee.
Which One Should You Pick
Choose the Axis Bank My Zone Credit Cardⓘ if dining and online shopping form a significant part of your monthly expenditure and you want to enjoy a free SonyLiv subscription. It suits users looking for category-specific high rewards and do not mind paying a modest fee.
Opt for the Yes Bank Rupay Credit Cardⓘ if you want a fee-free card with a higher base reward rate and decent returns on groceries and UPI payments. This card is ideal for budget-conscious shoppers and first-time credit card users who want straightforward rewards without fee worries.
In conclusion, skip Axis Bank My Zone if your dining and online spend is low or irregular and you want to avoid fees. Skip Yes Bank Rupay if you are primarily focused on premium dining rewards and are comfortable with paying an annual fee for better category benefits.
What to Check Before You Apply
- Confirm the Rs 50,000 quarterly spend gate needed to access the four domestic lounge visits on both cards.
- Check the quality and redemption options of points, as both cards use points but with different reward structures.
- Understand the fee waiver math, especially for Axis Bank My Zone which has no waiver and Yes Bank Rupay which is fee-free but mentions waiver on Rs 75,000 spend.
- Consider the 3.5% forex markup on both cards if you plan to spend abroad, as this adds to foreign transaction costs.

Comments
No comments yet
Be the first to share your experience with this card.