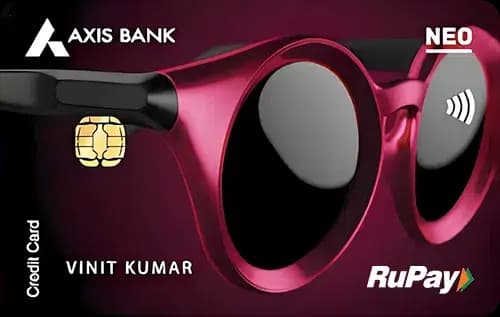
Quick Verdict
- For everyday online and utilities spend, the Axis Bank Neo Credit Cardⓘ wins with a 5% cashback category rate and zero fees.
- For fuel spend, the BPCL SBI Credit Cardⓘ offers a strong 4.25% return, better suited for drivers.
- The Axis Bank Neo is cheaper to hold with no joining or annual fees, while the BPCL SBI card charges Rs 499 annual fee, waived only on Rs 1 lakh annual spend.
- Choose Axis Bank Neo if you want a fee-free card with excellent cashback on online and utilities. Pick BPCL SBI if you frequently spend on fuel and can meet fee waiver thresholds.
Side by Side
| Detail | Axis Bank Neo Credit Cardⓘ | BPCL SBI Credit Cardⓘ |
|---|---|---|
| Annual fee | Nil (lifetime free) | Rs 499 |
| Joining fee | Nil (lifetime free) | Rs 499 |
| Fee waiver on spend | Rs 1.00 lakh annually | |
| Reward rate | 0.2% base, 5% online & utilities | 0.25% base, 4.25% fuel, 1.25% online |
| Reward type | points | points |
| Domestic lounge | None | None |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | first-card, shopping, cashback, dining | fuel, first-card |
Rewards Compared
Spending Rs 10,000 on the Axis Bank Neo Credit Cardⓘ yields Rs 20 as base rewards. However, if that spend is directed to online purchases or utilities, the card returns Rs 500, a significant uplift reflecting its 5% category rate. This makes it highly attractive for digital shoppers and bill payers seeking maximum cashback without added fees.
The BPCL SBI Credit Cardⓘ offers a slightly higher base reward rate of 0.25%, translating to Rs 25 on Rs 10,000 spend. Its standout category is fuel, with a 4.25% reward rate returning Rs 425 on Rs 10,000 fuel spend. Online spends earn a modest 1.25% or Rs 125 per Rs 10,000. This card rewards fuel expenses well but lags behind Axis Bank Neo on online and utilities cashback.
Fees Compared
The Axis Bank Neo Credit Cardⓘ has zero joining and annual fees, making it a cost-effective choice for fee-averse users. There is no fee waiver threshold since no fees apply.
Conversely, the BPCL SBI Credit Cardⓘ charges Rs 499 as both joining and annual fees. The annual fee is waived if you spend Rs 1,00,000 annually, about Rs 8,333 monthly. The card needs nearly Rs 2,00,000 in annual spend at base reward rates to cover the fee cost, a high bar for many users. Thus, the fee structure favors frequent fuel spenders who can meet the waiver threshold.
Which One Should You Pick
Choose the Axis Bank Neo Credit Cardⓘ if you want a no-fee card that maximizes cashback on online shopping and utility bill payments. It suits first-time cardholders and those who prefer straightforward cashback rewards without worrying about fee waivers. Skip this card if your primary spend is on fuel or you seek travel and lounge benefits.
Opt for the BPCL SBI Credit Cardⓘ if you regularly buy fuel and can maintain a monthly spend of around Rs 8,333 to waive the annual fee. This card is ideal for drivers looking to earn higher rewards on petrol and diesel purchases. Avoid this card if you spend little on fuel, dislike annual fees, or prefer better rewards on online and utility spends.
In a direct comparison, the Axis Bank Neo Credit Cardⓘ is the better pick for most users due to its fee-free nature and superior online and utilities cashback. The BPCL SBI Credit Cardⓘ only gains an edge for heavy fuel spenders who can justify the fee with rewards.
What to Check Before You Apply
- Confirm if the 5% cashback on Axis Bank Neo applies to all online categories or specific merchants.
- Understand the redemption value for points on both cards to ensure rewards convert efficiently to cash or benefits.
- Calculate the monthly spend needed to waive the Rs 499 annual fee on the BPCL SBI card and ensure you can meet it comfortably.
- Note that both cards have a 3.5% forex markup, standard but costly for foreign currency spenders.
- Neither card offers domestic or international lounge access, so do not expect travel perks.

Comments
No comments yet
Be the first to share your experience with this card.