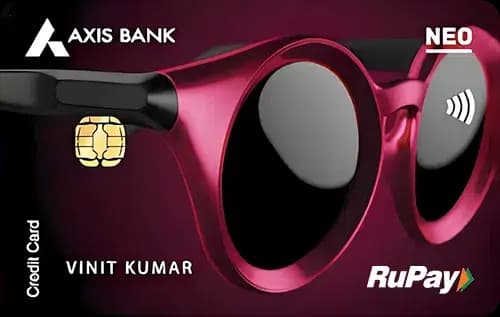
Quick Verdict
- For everyday spend, the HDFC Bank MoneyBack Plus Credit Cardⓘ wins with a higher base reward rate.
- For online and utility bill payments, the Axis Bank Neo Credit Cardⓘ offers superior category returns.
- The Axis Bank Neo Credit Card is cheaper to hold with no joining or annual fees.
- Pick Axis Bank Neo if you want a completely fee-free card with strong category rewards; choose HDFC MoneyBack Plus if you spend enough to justify the fee and want higher base rewards.
Side by Side
| Detail | Axis Bank Neo Credit Cardⓘ | HDFC Bank MoneyBack Plus Credit Cardⓘ |
|---|---|---|
| Annual fee | Nil (lifetime free) | Rs 500 |
| Joining fee | Nil (lifetime free) | Rs 500 |
| Fee waiver on spend | Rs 50,000 annually (Rs 4,167 monthly) | |
| Reward rate | 0.2% base, 5% online & utilities | 0.5% base, 3.33% online |
| Reward type | Points | Points |
| Domestic lounge | None | None |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | First card, shopping, cashback, dining | First card, cashback, shopping |
Rewards Compared
Spending Rs 10,000 on general purchases earns Rs 20 back on the Axis Bank Neo Credit Cardⓘ, reflecting its 0.2% base reward rate. However, spending Rs 10,000 on online or utility payments yields Rs 500 in rewards, thanks to the 5% category rates. This makes it a strong card for specific spending categories but less rewarding on general spends.
In contrast, the HDFC Bank MoneyBack Plus Credit Cardⓘ offers Rs 50 back on Rs 10,000 general spend, more than double the Neo’s base rate. Its online category rewards are Rs 333 on Rs 10,000 spent, which is lower than Neo’s Rs 500 in the same category. Thus, HDFC’s card is better for broad-based rewards, while Axis Neo excels in targeted categories like online shopping and utilities.
Fees Compared
The Axis Bank Neo Credit Cardⓘ has a clear advantage with no joining or annual fees, making it attractive for those wary of recurring charges. The HDFC Bank MoneyBack Plus Credit Cardⓘ charges Rs 500 for both joining and annual fees, but these can be waived by spending Rs 50,000 annually, or about Rs 4,167 monthly.
To justify the Rs 500 annual fee, you need to spend about Rs 1,00,000 on the HDFC card to cover the fee difference through rewards, given its higher base rate. If you do not meet this threshold, the Axis Bank Neo card’s no-fee structure is more economical.
Which One Should You Pick
Choose the Axis Bank Neo Credit Cardⓘ if you prefer a no-fee card with strong rewards in online shopping and utility payments. It suits first-time cardholders who want to avoid fees and maximize cashback in specific categories such as dining and utilities. However, it offers a low base reward rate, so if your spending is not focused on those categories, its rewards may feel limited.
The HDFC Bank MoneyBack Plus Credit Cardⓘ is better for those who want consistent rewards on all spending and can comfortably meet the Rs 50,000 annual fee waiver threshold. Its higher base rate makes it a good choice if you plan to use the card frequently across diverse categories. However, skip this card if you do not spend enough to justify the fees or prefer a card with no joining cost.
In summary, pick Axis Bank Neo for a no-fee card with category-focused cashback and HDFC MoneyBack Plus for higher base rewards if you can meet the fee waiver. Those who want a simple, fee-free experience should skip HDFC MoneyBack Plus, while those who want broad rewards without constraints should avoid Axis Bank Neo.
What to Check Before You Apply
- Confirm caps on category rewards, especially for the 5% online and utilities rate on Axis Neo.
- Understand the redemption value and ease of converting points into cashback or other benefits.
- Calculate the monthly spend needed to waive fees on HDFC MoneyBack Plus to avoid surprise costs.
- Note the 3.5% forex markup on foreign transactions for both cards if you plan to use them abroad.
- Check which lounges each card grants access to, as neither offers any lounge benefits.

Comments
No comments yet
Be the first to share your experience with this card.