Quick Verdict
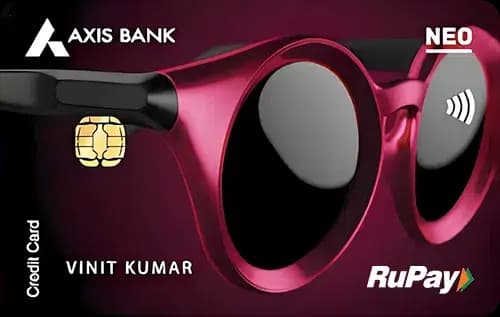
- For everyday spending, the Axis Bank Neo Credit Cardⓘ wins with its zero fees and strong rewards on online and utility spends.
- For travel and lounge benefits, the HDFC Bank Rupay IRCTC Credit Cardⓘ is the clear winner, offering domestic lounge access and better base rewards.
- The Axis Bank Neo card is cheaper to hold with no joining or annual fees, while the HDFC card charges a joining fee with an annual fee waiver on high spend.
- Choose Axis Bank Neoⓘ if you want a free, straightforward cashback card for shopping and utilities. Pick HDFC Rupay IRCTCⓘ if you prioritize travel rewards and domestic lounge access but can meet the fee waiver spend.
Side by Side
| Detail | Axis Bank Neo Credit Cardⓘ | HDFC Bank Rupay IRCTC Credit Cardⓘ |
|---|---|---|
| Annual fee | Nil (lifetime free) | Nil (lifetime free) |
| Joining fee | Nil (lifetime free) | Rs 500 |
| Fee waiver on spend | Rs 1.50 lakh annually | |
| Reward rate | 0.2% base | 0.5% base |
| Reward type | points | points |
| Domestic lounge | None | 8 per year |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | first-card, shopping, cashback, dining | travel, upi-rupay, first-card |
| Lounge spend gate | Rs 75,000 quarterly (for domestic lounges) |
Rewards Compared
With Rs 10,000 spent, the Axis Bank Neo Credit Cardⓘ returns Rs 20 at its base reward rate of 0.2%. However, if you spend in its strong categories like online shopping or utilities, the return increases substantially to Rs 500 per Rs 10,000 spent, which is an effective 5% rate. This makes it highly rewarding for users who pay bills or shop online frequently.
Meanwhile, the HDFC Bank Rupay IRCTC Credit Cardⓘ offers a better base reward rate at 0.5%, yielding Rs 50 for every Rs 10,000 spent across all categories. Its top category, travel, also pays 5%, returning Rs 500 per Rs 10,000. UPI transactions earn a lower 1% rate or Rs 100 per Rs 10,000. Overall, HDFC’s Rupay IRCTC card is more travel-focused but also rewards everyday spend better than Axis Neo at the base rate.
Fees Compared
The Axis Bank Neo Credit Cardⓘ is completely free to join and hold, with no annual fee or joining fee, making it the cheapest option for any user. The HDFC Bank Rupay IRCTC Credit Cardⓘ charges a Rs 500 joining fee but no annual fee thereafter. However, the annual fee is waived if you spend Rs 1.50 lakh annually, which translates to about Rs 12,500 monthly. The card also requires Rs 75,000 quarterly spending to enjoy the 8 domestic lounge visits. For users not meeting these spends, the card’s value diminishes due to fees and lounge restrictions.
Which One Should You Pick
If you are a first-time cardholder or a shopper who pays bills and prefers a simple, no-fee card with solid cashback on utilities and online spends, then the Axis Bank Neo Credit Cardⓘ is the ideal choice. It suits those who dislike complicated fee waivers and want to maximize online shopping rewards without worrying about charges.
On the other hand, if you are a frequent traveler who values domestic lounge access, can comfortably spend Rs 12,500 monthly to waive fees, and want higher base rewards on travel spends, then the HDFC Bank Rupay IRCTC Credit Cardⓘ should be your pick. It also suits users preferring Rupay acceptance and those who want a reasonable welcome benefit via an Amazon voucher.
In summary, skip the Axis Neoⓘ if you want travel perks or lounge access. Avoid the HDFC Rupay IRCTCⓘ if you cannot meet the fee waiver spends or dislike paying a joining fee upfront.
What to Check Before You Apply
- Confirm if your typical spend fits into the high-reward categories for each card to maximize returns.
- Check the redemption process and value of reward points since both cards earn points but differ in category applicability.
- For HDFC Rupay IRCTCⓘ, calculate if your monthly spends cover the Rs 12,500 fee waiver and Rs 75,000 lounge gate to justify the joining fee.
- Keep in mind both cards apply a 3.5% forex markup on foreign transactions, which is standard but costly for international spenders.
- Verify the domestic lounge network and access rules on the HDFC card, including visit limits and eligible airports.

Comments
No comments yet
Be the first to share your experience with this card.