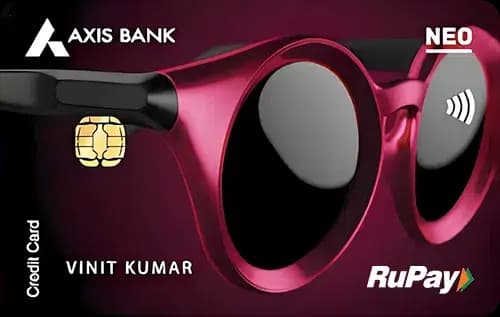
Quick Verdict
- The HSBC Visa Platinum Credit Cardⓘ offers a higher base reward rate, making it the better choice for everyday spend.
- Neither card offers domestic or international lounge access, so neither wins on travel or lounge benefits.
- Both cards have no joining or annual fees, making them equally cheap to hold.
- Choose the Axis Bank Neo Credit Cardⓘ if you prioritise online and utility spending with strong category rewards and a cashback welcome offer.
- Opt for the HSBC Visa Platinum Credit Cardⓘ if you want a solid lifetime-free card with better base rewards and a dining category bonus.
Side by Side
| Detail | Axis Bank Neo Credit Cardⓘ | HSBC Visa Platinum Credit Cardⓘ |
|---|---|---|
| Annual fee | Nil (lifetime free) | Nil (lifetime free) |
| Joining fee | Nil (lifetime free) | Nil (lifetime free) |
| Fee waiver on spend | Not applicable | Not applicable |
| Reward rate | 0.2% base; 5% online, utilities | 0.67% base; 2% dining |
| Reward type | Points | Points |
| Domestic lounge | None | None |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | First-card, shopping, cashback, dining | Lifetime-free, first-card, dining, shopping |
Rewards Compared
On a spend of Rs 10,000, the Axis Bank Neo Credit Cardⓘ returns Rs 20 as base rewards. However, for online and utilities spend categories, it offers a substantial 5% return, translating to Rs 500 back on Rs 10,000 spent in these categories. This makes it highly rewarding for users whose spending is concentrated in online shopping or utility bill payments. The welcome benefit of 100% cashback up to Rs 300 on the first utility bill payment further sweetens the deal for utility spenders.
In contrast, the HSBC Visa Platinum Credit Cardⓘ provides a higher base reward rate of 0.67%, which means Rs 67 back on Rs 10,000 spent overall. Its category bonus is more modest, offering 2% rewards on dining spend, equivalent to Rs 200 on Rs 10,000 spent in that category. This card suits users who prefer consistent rewards on all spend with extra benefits on dining. The Rs 250 Amazon voucher welcome benefit adds immediate value upon activation.
Fees Compared
Both the Axis Bank Neo Credit Cardⓘ and HSBC Visa Platinum Credit Cardⓘ are completely free to hold, with no joining fees and no annual fees for life. There are no fee waiver thresholds to meet, making them ideal for users who want a zero-cost credit card. Since neither card charges fees, there is no break-even spend point to consider. This price parity means the decision should rest on rewards and benefits rather than costs.
Which One Should You Pick
The Axis Bank Neo Credit Cardⓘ is best suited for first-time cardholders who mainly spend online or on utilities. Its high 5% cashback rate in these categories and a useful welcome cashback on utility bills make it a very attractive choice for shoppers and those wanting easy cashback rewards. However, if your spend is more varied or you prioritise dining rewards, this card might feel limited.
The HSBC Visa Platinum Credit Cardⓘ is ideal for users looking for a well-rounded, lifetime-free card with a decent base reward rate of 0.67% across all spend plus an additional 2% on dining. Its welcome Amazon voucher offers extra value, and it suits those who want a simple, no-fee card with steady rewards. It is less rewarding for online or utility spend compared to the Axis Neo.
If you do not spend much online or on utilities, skip the Axis Bank Neo Credit Cardⓘ. If you want the highest rewards on online and utility spends, the HSBC Visa Platinum Credit Cardⓘ is less attractive. Overall, for everyday use and dining, HSBC Visa Platinum Credit Cardⓘ wins, but for category-specific cashback, Axis Bank Neo Credit Cardⓘ shines.
What to Check Before You Apply
- Confirm the caps or maximum cashback limits for category rewards to avoid surprises.
- Check the redemption process and value for points to ensure your rewards convert efficiently.
- Understand the fee waiver requirements, though both cards have no fees, to avoid unexpected charges.
- Consider the 3.5% forex markup, which is standard but high, if you frequently spend abroad.
- Note that neither card offers lounge access, so frequent travellers seeking lounge privileges should look elsewhere.

Comments
No comments yet
Be the first to share your experience with this card.