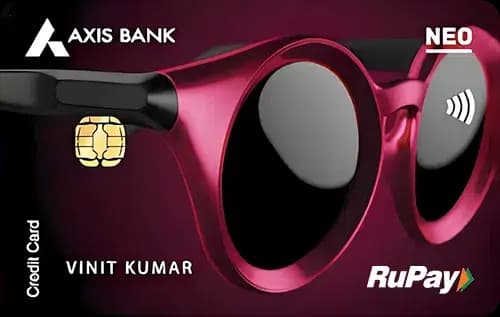
Quick Verdict
- For everyday spend, the ICICI HPCL Super Saver Credit Card ⓘ wins with a higher base reward rate of 1% versus 0.2% on the Axis Bank Neo Credit Card ⓘ.
- For fuel, grocery, and utilities categories, ICICI HPCL Super Saver also leads with 5% rewards, matching Axis Bank Neo only in utilities and online spend.
- The Axis Bank Neo Credit Card ⓘ is cheaper to hold with no joining or annual fees, while ICICI HPCL Super Saver charges Rs 500 for each but offers fee waiver on Rs 1.5 lakh annual spend.
- Choose Axis Bank Neo ⓘ if you want a no-fee card primarily for online shopping and utilities with simple cashback. Opt for ICICI HPCL Super Saver ⓘ if you spend heavily on fuel, groceries, and want domestic lounge access.
Side by Side
| Detail | Axis Bank Neo Credit Card ⓘ | ICICI HPCL Super Saver Credit Card ⓘ |
|---|---|---|
| Annual fee | Nil (lifetime free) | Rs 500 |
| Joining fee | Nil (lifetime free) | Rs 500 |
| Fee waiver on spend | Rs 1.50 lakh annually (Rs 12,500 monthly) | |
| Reward rate | 0.2% base | 1% base |
| Reward type | points | points |
| Domestic lounge | None | 4 per year (Rs 75,000 quarterly spend gate) |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | first-card, shopping, cashback, dining | fuel, grocery, cashback, shopping, lounge |
Rewards Compared
Spending Rs 10,000 on the Axis Bank Neo Credit Card ⓘ yields Rs 20 back at the base reward rate of 0.2%. However, if you spend in the online or utilities categories, the card offers an impressive 5% return, translating to Rs 500 on Rs 10,000 spent. This makes it attractive for users focused on these categories, especially online shoppers and those paying utility bills. The card also features a welcome benefit with 100% cashback up to Rs 300 on the first utility bill payment, adding value for new users.
In contrast, the ICICI HPCL Super Saver Credit Card ⓘ provides a base reward rate of 1%, giving Rs 100 per Rs 10,000 spent, which is five times higher than Axis Bank Neo’s base. For fuel, grocery, and utilities spends, it matches the 5% return, i.e., Rs 500 per Rs 10,000 spent, similar to Axis Bank Neo’s category rates but on a wider set of categories. This card also offers a welcome benefit of 2,000 bonus points on timely fee payment and minimum spend, plus Rs 100 cashback on the first fuel purchase via HP Pay app, enhancing its value for fuel buyers.
Fees Compared
The Axis Bank Neo Credit Card ⓘ stands out with no joining or annual fees, making it a cost-effective choice for those who want to avoid recurring charges. There is no fee waiver threshold since the fees are nil, which simplifies the cost structure.
The ICICI HPCL Super Saver Credit Card ⓘ charges Rs 500 as both joining and annual fees. However, these fees are waived if you spend Rs 1.5 lakh annually, which breaks down to Rs 12,500 monthly. The break-even spend for the higher base reward rate to cover the Rs 500 annual fee is Rs 50,000, meaning if you spend above this, the higher rewards justify the fee. The card also requires Rs 75,000 quarterly spend to access the four domestic lounges per year.
Which One Should You Pick
The Axis Bank Neo Credit Card ⓘ suits first-time credit card users and those who primarily shop online or pay utility bills, and want a completely fee-free card. It is ideal if you prefer simple cashback rewards without worrying about minimum spends or fee waivers. However, skip this card if you want strong rewards on fuel or grocery spends or lounge access.
The ICICI HPCL Super Saver Credit Card ⓘ is best for heavy spenders on fuel, groceries, and utilities who can meet the Rs 1.5 lakh annual spend to waive fees. It is also attractive for those who value domestic lounge access and want better base rewards on all spends. Avoid this card if you have low monthly spends below Rs 12,500 or do not want to pay upfront fees.
Overall, if you prioritize no-fee simplicity and online/utility rewards, pick Axis Bank Neo ⓘ. For broader category rewards, lounge access, and willing to meet fee waiver spends, ICICI HPCL Super Saver ⓘ is the better choice.
What to Check Before You Apply
- Confirm if the 5% category rewards on utilities or fuel have any monthly or annual caps.
- Check the redemption value of points on both cards to ensure you get the expected cashback or benefits.
- Understand the fee waiver spend requirement on ICICI HPCL Super Saver and whether you can comfortably meet it.
- If you travel abroad, note both cards charge 3.5% forex markup, which can add significant cost on foreign spends.
- Verify the domestic lounge access gates and conditions on ICICI HPCL Super Saver, including the Rs 75,000 quarterly spend requirement.

Comments
No comments yet
Be the first to share your experience with this card.