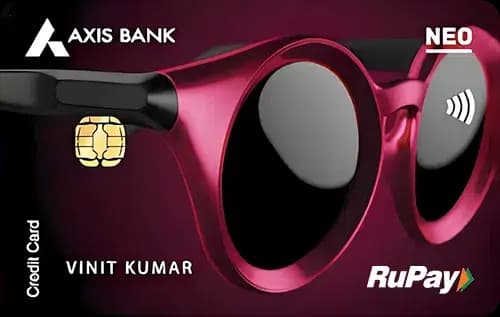
Quick Verdict
- For everyday spend, especially outside of online utilities, the IDFC First Wow Credit Cardⓘ wins with a higher base reward rate of 1% versus 0.2% on the Axis Bank Neo Credit Cardⓘ.
- For online and utility spend, the Axis Bank Neo Credit Cardⓘ offers superior rewards at 5%, making it the better pick for targeted category spend.
- Both cards have no joining or annual fees, making them equally cheap to hold.
- Choose the Axis Bank Neo for cashback on utilities and online shopping with a welcome cashback offer. Opt for the IDFC First Wow if you want better base rewards, zero forex markup for international transactions, and a card suited for students or forex spenders.
Side by Side
| Detail | Axis Bank Neo Credit Cardⓘ | IDFC First Wow Credit Cardⓘ |
|---|---|---|
| Annual fee | Nil (lifetime free) | Nil (lifetime free) |
| Joining fee | Nil (lifetime free) | Nil (lifetime free) |
| Fee waiver on spend | None | None |
| Reward rate | 0.2% base, 5% online & utilities | 1% base, 1% online |
| Reward type | Points | Points |
| Domestic lounge | None | None |
| International lounge | None | None |
| Forex markup | 3.5% | 0% |
| Best suited for | First-card, shopping, cashback, dining | Lifetime-free, first-card, student, forex, dining, shopping |
Rewards Compared
The Axis Bank Neo Credit Cardⓘ delivers Rs 20 back on every Rs 10,000 spent as a base reward. However, it shines in its category rates, offering Rs 500 back on Rs 10,000 spent on online purchases or utility bills, a substantial 5% effective return. This makes it highly attractive for users who frequently pay utility bills or shop online and want significant cashback in these segments. Outside these categories, the rewards are modest and may not justify heavy usage.
The IDFC First Wow Credit Cardⓘ provides a solid flat base reward of Rs 100 on Rs 10,000 spend, which is five times the base reward of the Neo card. Its online category rate remains at 1%, matching the base rate and thus providing consistent returns across all spends. While it does not offer high category-specific boosts like the Neo card, its straightforward reward structure benefits users who prefer simplicity and consistent cashback on all transactions.
Fees Compared
Both cards are lifetime free with no joining or annual fees, which is a major plus for cost-conscious users. There is no fee waiver threshold to meet since there are no fees to waive. This means users can freely use either card without worrying about minimum spends or fee triggers.
The absence of fees means there is no break-even consideration needed; the choice depends entirely on reward returns and features rather than cost.
Which One Should You Pick
The Axis Bank Neo Credit Cardⓘ is well suited for first-time cardholders who have significant online and utility bill payments. Its 5% cashback in those categories and a welcome benefit of 100% cashback up to Rs 300 on the first utility bill make it a compelling choice for shoppers focused on these spends. However, users who want rewards on all spend categories or who travel internationally should look elsewhere.
The IDFC First Wow Credit Cardⓘ suits those who prefer a simple, flat 1% reward rate on all spends and benefit from zero forex markup, making it ideal for students, frequent travelers, or forex spenders. Its broader category suitability and higher base rate make it a flexible everyday card. Users who do not have significant online or utility spend may find this card more rewarding overall.
In decisive terms, pick the Axis Bank Neoⓘ if your focus is on maximizing cashback on online and utility bills. Choose the IDFC First Wowⓘ if you want a versatile, no-annual-fee card with good base rewards and zero forex charges. Those who rarely spend online or pay utilities should skip the Neo, and those who do not travel or want category-specific rewards can skip the Wow.
What to Check Before You Apply
- Verify if the 5% category rate on the Axis Bank Neoⓘ has any monthly caps or exclusions.
- Confirm the redemption value and process for reward points on both cards to ensure ease of use.
- Understand that fee waiver is irrelevant here but check for any hidden fees or charges.
- Note the high 3.5% forex markup on the Neoⓘ, which can be costly for international spenders.
- Check which lounges, if any, are accessible despite the stated "None" to avoid surprises at airports.

Comments
No comments yet
Be the first to share your experience with this card.