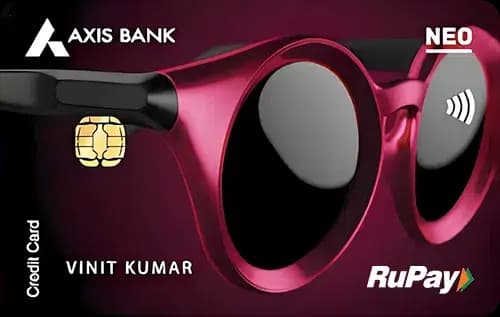
Quick Verdict
- The Indianoil HDFC Bank Credit Cardⓘ wins for everyday spend with a higher base reward rate of 1% compared to Axis Bank Neo’s 0.2%.
- For travel or lounges, neither card offers any lounge access, so neither has a clear advantage.
- The Axis Bank Neo Credit Cardⓘ is cheaper to hold as it has no joining or annual fee, while Indianoil HDFC charges Rs 500 annually with waiver conditions.
- Choose Axis Bank Neoⓘ if you want a free, no-strings card focused on online and utility spends; pick Indianoil HDFCⓘ if your primary spend is on fuel or grocery and you can meet the fee waiver.
Side by Side
| Detail | Axis Bank Neo Credit Cardⓘ | Indianoil HDFC Bank Credit Cardⓘ |
|---|---|---|
| Annual fee | Nil (lifetime free) | Rs 500 |
| Joining fee | Nil (lifetime free) | Rs 500 |
| Fee waiver on spend | Rs 50,000 annually | |
| Reward rate | 0.2% base | 1% base |
| Reward type | points | points |
| Domestic lounge | None | None |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | first-card, shopping, cashback, dining | fuel, first-card, upi-rupay |
Rewards Compared
The Axis Bank Neo Credit Cardⓘ returns Rs 20 on a Rs 10,000 spend at its base rate of 0.2%. However, it shines in specific categories like online and utilities where the reward rate jumps to 5%, translating to Rs 500 back on Rs 10,000 spent. This makes it attractive for users who frequently shop online or pay utility bills, especially with its welcome benefit of 100% cashback up to Rs 300 on the first utility bill payment.
In contrast, the Indianoil HDFC Bank Credit Cardⓘ offers a solid 1% base reward rate, giving Rs 100 back on Rs 10,000 spent across all categories. It further enhances rewards to 5% in fuel and grocery spends, again yielding Rs 500 for every Rs 10,000 spent in these categories. This card is well-suited for users whose major expenses are fuel or groceries, offering more consistent rewards across broader categories than Axis Bank Neo.
Fees Compared
Axis Bank Neo Credit Cardⓘ has no joining or annual fee, making it a truly free-to-hold card with no minimum spend requirements. On the other hand, the Indianoil HDFC Bank Credit Cardⓘ charges a Rs 500 joining fee and Rs 500 annual fee. The annual fee is waived if you spend Rs 50,000 per year, equivalent to about Rs 4,167 monthly. To justify paying the Rs 500 annual fee purely through the higher base reward rate, you would need to spend Rs 50,000 at the base rate to break even. This means if your spend is below this threshold, the Axis Neo is cheaper and better value.
Which One Should You Pick
Pick the Axis Bank Neo Credit Cardⓘ if you want a no-cost entry-level card that rewards you handsomely on online shopping and utility bill payments. It is ideal for first-time cardholders or those who want cashback without worrying about minimum spends or fees. However, if your spending is predominantly on fuel or groceries and you can comfortably spend Rs 4,167 monthly to get the fee waived, the Indianoil HDFC Bank Credit Cardⓘ is a better choice due to its higher base reward rate and category bonuses.
Skip Axis Neo if you want better overall rewards on everyday spends beyond online and utilities and are okay with paying fees. Avoid Indianoil HDFC if you do not spend enough monthly to waive the fee or if you want a card with no fees and simpler terms.
What to Check Before You Apply
- Confirm if category-specific caps limit the 5% reward on online, utility, fuel, or grocery spends.
- Understand the redemption process and if points have a fixed value or variable redemption rates.
- Check the monthly spend needed to waive the Indianoil HDFC annual fee to avoid surprise charges.
- Be aware that both cards have a 3.5% forex markup, which is high for international spends.
- Neither card offers domestic or international lounge access, so don’t expect travel perks here.

Comments
No comments yet
Be the first to share your experience with this card.