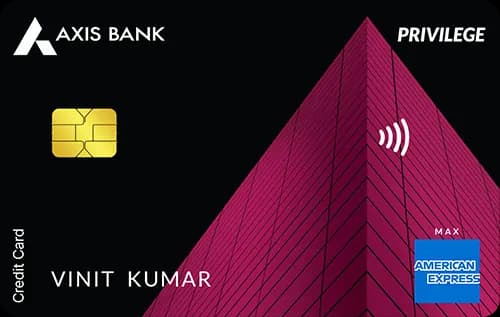
Quick Verdict
- The Marriott Bonvoy HDFC Bank Credit Cardⓘ wins for everyday spend with a higher base reward rate and better category returns on travel and dining.
- The Axis Bank Privilege Credit Cardⓘ offers more domestic lounge access flexibility and a lower annual fee, making it a better choice for moderate spenders focused on domestic travel and shopping.
- The Axis Bank card is cheaper to hold with a Rs 1,500 annual fee and a lower waiver threshold, while the Marriott Bonvoy card charges Rs 3,000 annually with a higher waiver spend requirement.
- Pick the Marriott Bonvoy HDFC cardⓘ if you are a premium traveler who values international lounge access and golf benefits. Choose the Axis Bank Privilege cardⓘ if you want a first credit card with solid rewards on online shopping and domestic lounges.
Side by Side
| Detail | Axis Bank Privilege Credit Cardⓘ | Marriott Bonvoy HDFC Bank Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 1,500 | Rs 3,000 |
| Joining fee | Rs 1,500 | Rs 3,000 |
| Fee waiver on spend | Rs 2.50 lakh | Not recorded |
| Reward rate | 0.8% base, 2% online | 1.3% base, 2.6% travel & dining |
| Reward type | points | points |
| Domestic lounge | 8 per year | 12 per year |
| International lounge | None | 12 per year |
| Forex markup | 3.5% | 3.5% |
| Best suited for | rewards, lounge, first-card, travel, shopping | travel, premium, lounge, rewards, shopping |
Rewards Compared
On a Rs 10,000 spend, the Axis Bank Privilege Credit Cardⓘ yields Rs 80 back at the base rate and Rs 200 when spent online, reflecting a 0.8% base reward and a boosted 2% return in the online category. This makes it suitable for shoppers who frequently buy online and want consistent rewards on everyday purchases.
In contrast, the Marriott Bonvoy HDFC Bank Credit Cardⓘ offers a stronger base return of Rs 130 per Rs 10,000 spent, or 1.3%. Its category rates are even more attractive for travel and dining expenses, giving Rs 260 back per Rs 10,000 spent in these categories, which is double the base rate. This card is clearly designed for premium users who spend heavily on travel and dining, maximizing rewards in those areas.
Fees Compared
The Axis Bank Privilege Credit Cardⓘ charges an annual and joining fee of Rs 1,500 each, with a fee waiver if you spend Rs 2.50 lakh annually, equating to about Rs 20,833 per month. This is a moderate threshold, making it easier for average users to avoid fees. The card breaks even on base rewards at around Rs 1.88 lakh spend annually.
The Marriott Bonvoy HDFC Bank Credit Cardⓘ has a higher joining and annual fee of Rs 3,000 each, with no explicit fee waiver threshold mentioned. The base reward rate requires a higher spend of about Rs 2.31 lakh annually to cover its fee. The head-to-head analysis shows that to justify the extra Rs 1,500 annual fee over the Axis card, you would need to spend about Rs 3 lakh more annually to make the higher rewards worthwhile.
Which One Should You Pick
Choose the Axis Bank Privilege Credit Cardⓘ if you are a first-time credit card user or a moderate spender who shops online frequently and values domestic lounge access. Its lower fees and easier waiver threshold make it a practical choice for everyday rewards and occasional travel perks. Skip this card if you travel internationally often or want premium benefits like golf access.
Opt for the Marriott Bonvoy HDFC Bank Credit Cardⓘ if you are a premium traveler who spends heavily on travel and dining, and you want international lounge access and exclusive benefits like golf lessons and concierge services. This card suits those who can comfortably meet a higher fee and spend threshold to unlock its full value. Avoid this card if your spend is moderate or if you do not utilize travel-related perks regularly.
Overall, the Marriott Bonvoy HDFC Bank Credit Cardⓘ is the better pick for frequent travelers and premium users, while the Axis Bank Privilege Credit Cardⓘ is ideal for budget-conscious users seeking value on online shopping and domestic lounge access.
What to Check Before You Apply
- Confirm any quarterly or monthly caps on lounge access usage, especially the Rs 50,000 quarterly spend gate for domestic lounges on the Axis card.
- Understand the redemption value of points, as both cards offer points but the actual value can vary depending on redemption options.
- Carefully calculate the fee waiver math: the Axis card requires Rs 2.50 lakh annual spend, while the Marriott card’s waiver details are not specified.
- Consider the 3.5% forex markup on foreign currency spends, which applies equally to both cards and can be costly for frequent international travelers.
- Check the availability and locations of lounges accessible with each card, including the 12 international lounges offered by the Marriott card versus none for the Axis card.

Comments
No comments yet
Be the first to share your experience with this card.