Quick Verdict
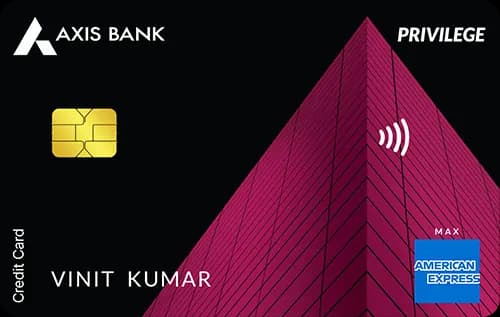
- The Axis Bank Privilege Credit Cardⓘ wins for everyday spend due to a higher base reward rate of 0.8% compared to SBI Prime’s 0.5%.
- For travel perks, especially international lounge access, the SBI Prime Credit Cardⓘ leads with 4 international lounges annually and Priority Pass membership.
- The Axis Bank Privilege Credit Cardⓘ is cheaper to hold with a lower joining and annual fee of Rs 1,500 versus Rs 2,999 on the SBI Prime.
- Choose Axis Bank Privilege if you want a cost-effective card with solid rewards and domestic lounge access; pick SBI Prime if you prioritize international travel benefits and enhanced dining and grocery rewards.
Side by Side
| Detail | Axis Bank Privilege Credit Card ⓘ | SBI Prime Credit Card ⓘ |
|---|---|---|
| Annual fee | Rs 1,500 | Rs 2,999 |
| Joining fee | Rs 1,500 | Rs 2,999 |
| Fee waiver on spend | Rs 2.50 lakh | Rs 3.00 lakh |
| Reward rate | 0.8% base, 2% online spend | 0.5% base, 2.5% on dining, grocery, utilities |
| Reward type | points | points |
| Domestic lounge | 8 per year (2x/quarter Mastercard) | 8 per year |
| International lounge | None | 4 per year (Priority Pass) |
| Forex markup | 3.5% | 3.5% |
| Best suited for | rewards, lounge, first-card, travel, shopping | rewards, dining, lounge, grocery, travel, shopping |
| Premium benefits | 2x/quarter Mastercard domestic lounges, ₹2,500 welcome voucher, annual fee waiver on ₹5 lakh spend | Priority Pass membership, 8 domestic lounges, Club ITC Silver Tier, birthday bonus points |
Rewards Compared
Spending Rs 10,000 on the Axis Bank Privilege Credit Cardⓘ earns Rs 80 back at the base rate of 0.8%. If your purchases fall under the online category, this rate jumps to 2%, yielding Rs 200 per Rs 10,000 spent, which is a strong incentive for digital shoppers. The card’s reward structure favors general and online spenders, making it suitable for day-to-day shopping and travel bookings.
In contrast, the SBI Prime Credit Cardⓘ offers a lower base reward rate of 0.5%, equating to Rs 50 per Rs 10,000 spent. However, it shines in specific categories like dining, grocery, and utilities, where the effective return rate is 2.5%, translating into Rs 250 per Rs 10,000 spent. This makes the SBI Prime the better option if your expenses are concentrated in these categories, especially if you value rewards on essential monthly spends.
Fees Compared
The Axis Bank Privilege Credit Cardⓘ charges Rs 1,500 as both joining and annual fees. You can waive the annual fee by spending Rs 2.50 lakh annually, which breaks down to approximately Rs 20,833 per month. The card’s break-even point for covering the annual fee at the base reward rate is around Rs 1.88 lakh in spend, which is relatively accessible for moderate spenders.
On the other hand, the SBI Prime Credit Cardⓘ demands a heftier Rs 2,999 for joining and annual fees. The fee waiver requires Rs 3 lakh of yearly spend or Rs 25,000 monthly, a higher threshold than Axis Privilege. Moreover, the base reward rate means you need to spend about Rs 6 lakh annually just to cover the fee through rewards alone, making it more suitable for higher spenders or those focused on premium benefits rather than pure reward returns.
Which One Should You Pick
If you want a credit card that offers a better base rewards rate, especially for online shopping, and have a moderate annual spend around Rs 2.5 lakh, the Axis Bank Privilege Credit Cardⓘ is your pick. It also suits first-time premium cardholders who want domestic lounge access without high fees. Skip this card if you primarily spend on dining or groceries, or travel internationally often.
The SBI Prime Credit Cardⓘ is ideal for users who spend heavily on dining, groceries, and utilities and want the added value of international lounge access and premium memberships like Club ITC Silver Tier. The welcome vouchers and birthday bonuses add to its appeal for lifestyle-focused spenders. However, avoid this card if your monthly spend is below Rs 25,000 or if you dislike paying a higher fee without maximizing category rewards.
Decisively, pick the Axis Bank Privilege Credit Cardⓘ for better everyday rewards and lower fees, and choose the SBI Prime Credit Cardⓘ if you prioritize premium travel perks and category-specific rewards on dining and groceries.
What to Check Before You Apply
- Confirm if your typical spend meets the fee waiver thresholds: Rs 20,833 per month for Axis Privilege and Rs 25,000 for SBI Prime.
- Review redemption options for points to ensure you can maximize value, especially since reward types are points with varying category rates.
- Understand that forex markup is 3.5% on both cards, which is standard but costly for frequent international spending.
- Check the domestic lounge access gate for Axis Privilege, which requires Rs 50,000 quarterly spend to unlock the 2x per quarter lounge visits.

Comments
No comments yet
Be the first to share your experience with this card.