Quick Verdict
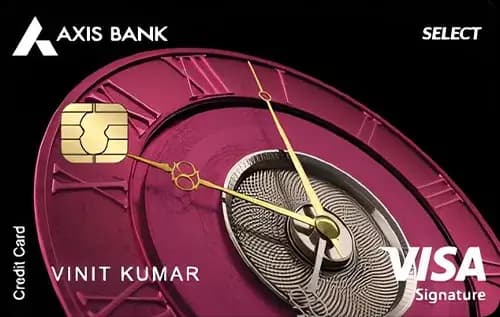
- For everyday spend, the Mayura Credit Cardⓘ wins with a higher base reward rate of 1.5% versus 1% on the Axis Bank Select Credit Cardⓘ.
- For travel and lounge access, Mayura Credit Cardⓘ offers unlimited domestic lounges and more international lounge visits, making it superior for frequent travellers.
- The Axis Bank Select Credit Cardⓘ is cheaper to hold, with a total annual fee of Rs 3,000 plus a joining fee of Rs 3,000, compared to Rs 5,999 each for the Mayura Credit Cardⓘ.
- Choose Axis Bank Select Credit Cardⓘ if you prioritise grocery rewards and a lower annual fee; pick Mayura Credit Cardⓘ if you want premium travel benefits and higher rewards on dining, travel, and online spends.
Side by Side
| Detail | Axis Bank Select Credit Cardⓘ | Mayura Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 3,000 | Rs 5,999 |
| Joining fee | Rs 3,000 | Rs 5,999 |
| Fee waiver on spend | Rs 10.00 lakh | Not recorded |
| Reward rate | 1% base | 1.5% base |
| Reward type | points | points |
| Domestic lounge | 8 per year | Unlimited |
| International lounge | 4 per year | 8 per year |
| Forex markup | 1.5% | 1.5% |
| Best suited for | rewards, grocery, lounge, travel, shopping | premium, travel, lounge, rewards, forex, shopping |
Rewards Compared
Spending Rs 10,000 on the Axis Bank Select Credit Cardⓘ earns Rs 100 back at the base rate of 1%. However, using the card for groceries yields 4% rewards, or Rs 400 on Rs 10,000 spent, and online spends earn 2%, or Rs 200. This makes it a strong choice for grocery shoppers who want to maximise returns in that category.
In contrast, the Mayura Credit Cardⓘ offers a higher flat base reward rate of 1.5%, translating to Rs 150 on Rs 10,000 spent. It also provides 3% rewards on dining, travel, and online categories, equivalent to Rs 300 on Rs 10,000 spent in these segments. This card suits users who spend across multiple premium categories and want consistent high rewards without category restrictions.
Fees Compared
The Axis Bank Select Credit Cardⓘ charges Rs 3,000 for both joining and annual fees, with a waiver if you spend Rs 10 lakh annually, which breaks down to Rs 83,333 per month. This high waiver threshold means only heavy spenders avoid fees. The card’s base reward rate covers the Rs 3,000 annual fee at around Rs 3 lakh spend.
The Mayura Credit Cardⓘ has a higher joining and annual fee of Rs 5,999 each. No fee waiver is specified, so the fee applies regardless of spend. Its higher base rate means you need to spend about Rs 4 lakh to cover the annual fee through rewards alone. The Mayura’s extra Rs 2,999 annual fee over the Axis card requires an additional Rs 6 lakh in spend to be justified purely by the reward rate difference, which is a steep hurdle.
Which One Should You Pick
Pick the Axis Bank Select Credit Cardⓘ if you are a grocery shopper or want a card with a lower annual fee that offers solid rewards in specific categories and decent lounge access. It is well suited for users who can meet the Rs 10 lakh waiver spend or who want to avoid the higher fees of premium cards.
Choose the Mayura Credit Cardⓘ if you want a premium card with unlimited domestic lounge access, better rewards on dining, travel, and online spends, and can justify the higher fees with your spending habits. It is ideal for frequent travellers and those who want a broad range of benefits including forex and lounge privileges.
In conclusion, heavy spenders focused on groceries and moderate travel should lean towards the Axis Bank Select Credit Cardⓘ. Premium users with diverse category spends and lounge needs will find the Mayura Credit Cardⓘ more rewarding. Avoid Axis Bank Selectⓘ if you spend little on groceries or want more lounge access; skip Mayuraⓘ if you cannot justify the high fees or do not travel often.
What to Check Before You Apply
- Confirm the Rs 10 lakh annual spend waiver threshold for the Axis Bank Select Credit Cardⓘ to avoid surprise fees.
- Understand the redemption value of points as both cards use points but no exact conversion rates are provided.
- Check if the joining and annual fees are charged upfront or billed later, and how the waiver applies monthly.
- For forex transactions, both cards charge 1.5% markup; consider this cost if you spend abroad frequently.
- Verify the lounge access locations and any spend gates, especially the Rs 50,000 annual domestic lounge spend gate on Axis Bank Selectⓘ.

Comments
No comments yet
Be the first to share your experience with this card.