Buying Supplements and Merchandise Inventory with a Credit Card
Published: 23 October 2026
Category: how-to-guides | cardbuzz
Tags: supplements, merchandise, inventory, stock purchase, protein
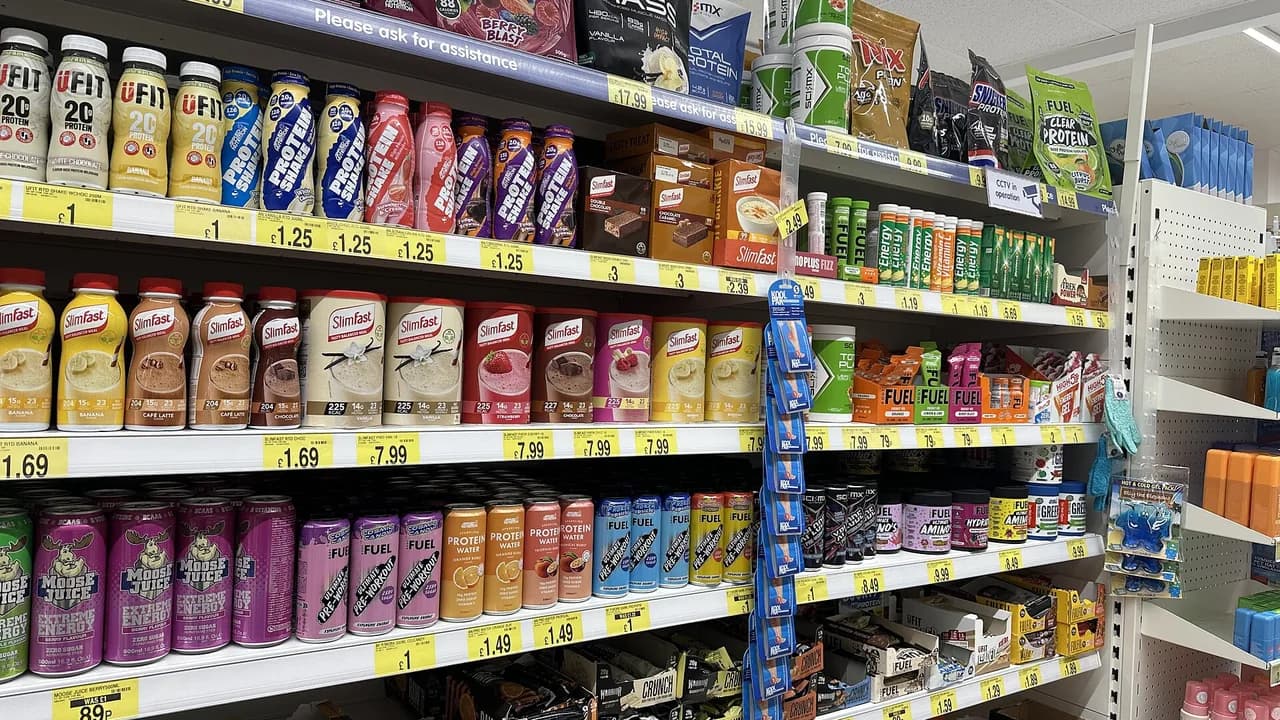
Gyms and trainers increasingly sell more than sessions. Protein, creatine, pre-workout, branded t-shirts, shakers and gym bags turn the front desk into a small retail counter — and retail means inventory. Inventory means buying stock before it sells, which means cash leaves weeks before it comes back. For a small fitness business, a credit card is often the most practical short-term inventory-financing tool available, provided it is used as a float rather than a loan.
This guide covers the mechanics: how to time stock purchases against the billing cycle, how supplier payment terms interact with card payments, what GST invoicing on inventory needs to look like, and how to keep the retail counter profitable instead of letting it become a cupboard of expired protein. No brand recommendations, no offer claims — just the operating logic.
Why the card suits inventory better than most business costs
Inventory has a natural repayment event: the stock sells. That makes it the cleanest use case for the interest-free period. You buy a month's protein stock on day one of the billing cycle, sell most of it over the next four to six weeks, and pay the statement in full from the proceeds. The supplier was paid on time, you never touched your cash reserve, and the float cost you nothing.
Contrast that with using the card for costs that have no linked inflow — rent, salaries — where the statement still has to be paid from general revenue. Inventory float is self-liquidating by design, which is exactly what short-term credit is for. The discipline is to buy only what the sales velocity justifies. A month's stock on the card is float; six months' stock on the card is speculation, and expired or slow-moving stock converts your zero-cost float into dead money plus interest.
Supplier terms, surcharges and the invoice
Before swiping, understand how your supplier bills. Distributors often offer their own credit terms — 15 or 30 days is common in the supplements trade. If the supplier gives you 30 days interest-free, paying by card on day one is usually worse than taking the supplier's terms, because the card statement comes due sooner. Use the card where the supplier demands upfront payment or cash-on-delivery, which is typical for smaller lots and new relationships.
Ask explicitly about card surcharges. B2B suppliers sometimes add a percentage for card payments to cover their own processing cost. A surcharge on a large stock order can exceed a month's retail margin on that stock — always compare the surcharged card price against the supplier's UPI or bank-transfer price before deciding. And insist on a proper tax invoice in the business's name with its GSTIN for every stock purchase. This is non-negotiable: without it you cannot claim input tax credit on the purchase, and your cost records for the retail counter will be fiction.
Timing purchases to the billing cycle
The interest-free period is longest for purchases made at the start of your billing cycle. For a business that restocks monthly, aligning the stock order to the first week of the cycle is a free extension of the float — you can be looking at six to seven weeks before the statement is due, depending on your issuer's terms, which comfortably covers a month's sales cycle.
This works best as a routine, not a trick. Fix a restock day each month, order to a par level (more on that below), and pay the statement in full when it falls due. The routine also gives you a monthly checkpoint: if this month's statement is consistently larger than last month's retail revenue, you are over-ordering, and the numbers will show it before the stockroom does.
One caution: do not confuse the billing cycle with permission to delay. The due date is the due date. Set up the statement payment as an automatic full-balance debit if your issuer and bank support it — a single missed due date on a large inventory statement generates interest and late fees that erase months of retail margin.
Par levels: buying what sells, not what looks good
The biggest inventory mistake in fitness retail is buying for the shelf, not the customer. A wall of flavours looks impressive; a wall of slow-moving stock is cash in jars. Set a par level for each SKU — the quantity that covers expected sales until the next restock, plus a small buffer — and order only to par.
Track velocity simply: units sold per month, per SKU. After two or three cycles you will know that whey sells steadily, that the exotic pre-workout sells one tub a quarter, and that the branded hoodies move only in winter. Buy to those numbers. Dead SKUs should be cleared (bundle them, discount them, move them) rather than reordered "because the shelf looks empty". Every rupee trapped in a SKU that sells four units a year is a rupee not available for the protein that turns over monthly.
Seasonality applies: January and post-Diwali fitness resolutions spike supplement sales; summer dips them. Adjust par levels quarterly rather than ordering flat all year.
Merchandise: lower velocity, higher margin thinking
Branded merchandise — tees, shakers, gym bags — behaves differently from consumables. It sells slower but carries better margins and doubles as marketing: every member wearing your tee is a walking advertisement. The card mechanics are the same (buy to par, pay in full), but the buying logic differs.
Order merchandise in smaller, more frequent lots even if the per-unit cost is slightly higher. A box of 50 tees that sells through in two months beats a box of 200 that takes a year, because the cash turns faster and you can iterate on designs. New design drops also create re-engagement moments — "new merch is in" is a legitimate reason to message your member list. And keep merchandise accounting separate from supplements: one is consumable retail with steady velocity, the other is episodic. Blending them hides which counter is actually earning.
Rewards and the honest maths of stock spends
Inventory purchases are often among a fitness business's largest card transactions, so the rewards question comes up naturally. Two reality checks. First, check how your issuer codes B2B supplier transactions — some merchant categories that distributors bill under may earn at base rates or be excluded from accelerated rewards entirely. Second, never let the pursuit of points inflate the order: buying an extra month of stock "for the points" is paying interest-free float on goods that may expire before they sell.
The correct frame is that rewards are a discount on the purchase price, realised later. If the stock was going to be bought anyway, in the right quantity, at the right time, and paid in full — then whatever points accrue are a genuine bonus. If any of those conditions fails, the points are subsidising a mistake. Run the retail counter like a retailer first: right SKU, right quantity, right price, paid on time. The card is the float that makes the timing work, nothing more and nothing less.
Negotiating with distributors: terms that beat the card
Before reaching for the card at all, negotiate the commercial terms — they are often more valuable than any float. Distributors routinely offer slab discounts (better per-unit pricing at higher quantities), introductory terms for new retail counters, and extended credit for reliable payers with a few months of history. A distributor who moves you from cash-on-delivery to 21-day terms has given you something no card can: free credit with no limit consumption and no statement to manage.
Negotiate on facts, not charm. Bring your sales-velocity numbers — "we move this SKU at forty units a month" is a stronger argument for better terms than any promise. Ask about damaged-or-expired goods policy before you need it: reputable distributors credit or replace stock that arrives damaged, and some take back slow-moving lines within a window. Get the returns understanding in writing, even informally over email. And once you have terms, honour them exactly — the distributor who trusts your payment rhythm is the one who extends terms when you need them most, such as ahead of a January demand spike. The card remains your backup for the orders that fall outside negotiated terms, not the default for all of them.


Comments
No comments yet
Be the first to share your experience with this card.