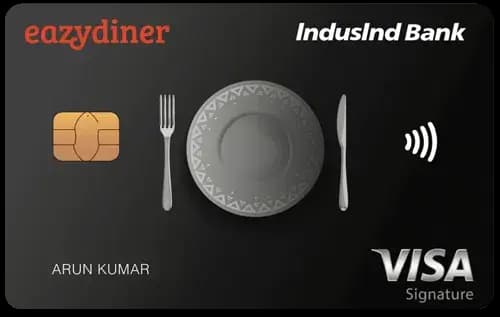
Quick Verdict
- For everyday spend, the Standard Chartered Ultimate Credit Card ⓘ delivers a much higher base reward rate, making it the superior choice.
- When it comes to travel and lounge access, the Standard Chartered Ultimate ⓘ again leads with more domestic and international lounges and additional travel insurance benefits.
- The Eazydiner Indusind Bank Credit Card ⓘ is cheaper to hold if you can meet its higher fee waiver threshold, but it has a significantly lower base reward rate.
- Pick the Eazydiner card ⓘ if you are a heavy diner wanting discounts and premium dining benefits; go for the Standard Chartered Ultimate ⓘ if you want better rewards on general spend and more extensive travel perks.
Side by Side
| Detail | Eazydiner Indusind Bank Credit Card ⓘ | Standard Chartered Ultimate Credit Card ⓘ |
|---|---|---|
| Annual fee | Rs 2,999 | Rs 5,000 |
| Joining fee | Rs 2,999 | Rs 5,000 |
| Fee waiver on spend | Rs 2.00 lakh | Not recorded |
| Reward rate | 0.7% base, 10% dining | 3.33% base |
| Reward type | points | points |
| Domestic lounge | 4 per year | 8 per year |
| International lounge | None | 4 per year |
| Forex markup | 3.5% | 2% |
| Best suited for | dining, rewards, lounge, travel | rewards, travel, lounge, premium, shopping |
Rewards Compared
On a standard spend of Rs 10,000, the Eazydiner Indusind Bank Credit Card ⓘ rewards you with Rs 70 in points at its base rate. However, if your spend is dining-related, the return jumps significantly to Rs 1,000 for the same Rs 10,000, thanks to its exclusive 10% category rate on dining. This makes it a compelling choice for food lovers who frequent premium restaurants where the card’s PayEazy discounts and EazyDiner Prime membership add to savings.
In contrast, the Standard Chartered Ultimate Credit Card ⓘ offers a flat base reward rate of 3.33%, translating to Rs 333 per Rs 10,000 spent regardless of category. This consistent rate makes it highly rewarding for general expenses including travel, shopping, and dining. The lack of category restrictions combined with a higher base rate positions the Ultimate card as a more versatile rewards option for diverse spenders.
Fees Compared
The Eazydiner Indusind Bank Credit Card ⓘ comes with an annual and joining fee of Rs 2,999 each, but offers a waiver if you spend Rs 2.00 lakh annually, which breaks down to about Rs 16,667 per month. Meeting this waiver threshold effectively reduces the cost of holding the card to zero, making it affordable for regular diners who can leverage its benefits.
The Standard Chartered Ultimate Credit Card ⓘ charges Rs 5,000 for both joining and annual fees with no explicit fee waiver on spend mentioned. This higher fee needs to be justified by higher rewards earnings or premium perks. The break-even spend to cover the fee difference compared to the Eazydiner card ⓘ is Rs 76,084. If your annual spend exceeds this, the Ultimate card’s rewards and benefits outweigh its higher cost.
Which One Should You Pick
Choose the Eazydiner Indusind Bank Credit Card ⓘ if you are a frequent diner who values exclusive restaurant discounts, access to premium dining lounges, and a complimentary EazyDiner Prime membership. It suits those who can comfortably meet the Rs 2.00 lakh annual spend to waive fees and want to optimise benefits in the dining and entertainment category. Skip this card if your spend is mostly outside dining or if you do not hit the waiver threshold.
Opt for the Standard Chartered Ultimate Credit Card ⓘ if you prefer a higher flat reward rate on all spends, want access to more domestic and international lounges including Priority Pass, and value travel insurance and golf benefits. It is ideal for premium users who travel frequently and spend across multiple categories. Avoid this card if you have low monthly spends or want to avoid the higher fees without a waiver.
Between the two, the Standard Chartered Ultimate ⓘ wins for overall rewards and travel perks, while the Eazydiner ⓘ is a niche pick for dining enthusiasts focused on restaurant savings.
What to Check Before You Apply
- Confirm if the dining category spend for Eazydiner ⓘ includes all restaurant types or only select partners to avoid surprises in reward rates.
- Check the redemption value and flexibility of reward points for both cards, as this affects real earnings.
- Understand the monthly spend needed to waive fees on Eazydiner ⓘ and whether you can realistically meet it.
- Consider the forex markup on foreign currency transactions; 3.5% on Eazydiner ⓘ is costlier than the 2% on Standard Chartered Ultimate ⓘ.
- Verify the lounge access locations and whether your frequent airports are covered, especially for Eazydiner ⓘ which lacks international lounges.

Comments
No comments yet
Be the first to share your experience with this card.