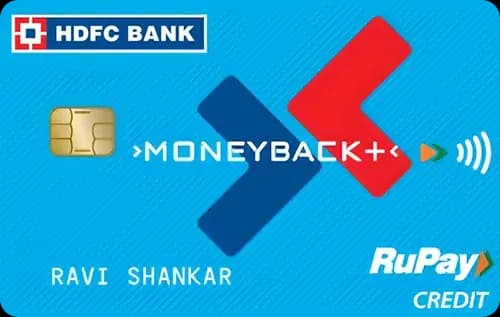
Quick Verdict
- For everyday online shopping spend, the HDFC Bank MoneyBack Plus Credit Cardⓘ offers superior rewards.
- For fuel expenses and occasional domestic lounge access, the ICICI Bank HPCL Coral Credit Cardⓘ is the better pick.
- The ICICI HPCL Coral card is cheaper to hold, with lower joining and annual fees and a higher waiver threshold.
- Choose the HDFC MoneyBack Plus card if you want better online rewards and a lower waiver spend; pick the ICICI HPCL Coral card if you prioritize fuel rewards and domestic lounge benefits.
Side by Side
| Detail | HDFC Bank MoneyBack Plus Credit Cardⓘ | ICICI Bank HPCL Coral Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 500 | Rs 199 |
| Joining fee | Rs 500 | Rs 199 |
| Fee waiver on spend | Rs 50,000 | Rs 1.50 lakh |
| Reward rate | 0.5% base, 3.33% online | 0.5% base, 5% fuel |
| Reward type | points | points |
| Domestic lounge | None | 4 per year (Rs 75,000 quarterly spend gate) |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | first-card, cashback, shopping | fuel, first-card, shopping |
Rewards Compared
The HDFC Bank MoneyBack Plus Credit Cardⓘ delivers Rs 50 back per Rs 10,000 spent at the base reward rate of 0.5%. However, if you spend online, the effective reward rate jumps to 3.33%, translating to Rs 333 per Rs 10,000 spent in that category. This makes it especially attractive for frequent online shoppers seeking cashback benefits. The card also offers a welcome benefit of 500 CashPoints, adding some upfront value.
On the other hand, the ICICI Bank HPCL Coral Credit Cardⓘ provides the same base reward rate of 0.5%, yielding Rs 50 per Rs 10,000 spent generally. Where it stands out is in the fuel category, offering a 5% reward rate, which means Rs 500 per Rs 10,000 spent on fuel. This higher rate makes it a compelling choice for those with significant fuel expenses. It also comes with an activation fuel benefit, which can be valuable for new cardholders.
Fees Compared
The HDFC MoneyBack Plus card charges a joining fee and annual fee of Rs 500 each, with a fee waiver on an annual spend of Rs 50,000. This means a monthly spend of about Rs 4,167 is required to avoid fees. The card’s base reward rate covers the fee at around Rs 1,00,000 annual spend, so moderate users may find the fee worthwhile if they leverage the online category rewards.
In contrast, the ICICI HPCL Coral card has a lower joining and annual fee of Rs 199 each, but a higher fee waiver threshold of Rs 1.50 lakh annually or Rs 12,500 monthly. The break-even for fee coverage by base rewards is around Rs 39,800 annually, which is significantly lower than the HDFC card. This makes the ICICI card more affordable to hold for users with higher monthly spends, especially if fuel rewards are maximized.
Which One Should You Pick
Choose the HDFC Bank MoneyBack Plus Credit Cardⓘ if you are a first-time cardholder who shops frequently online and wants a straightforward cashback experience with a moderate fee waiver threshold. It suits those who want decent rewards without chasing high spends and do not require lounge access.
The ICICI Bank HPCL Coral Credit Cardⓘ is better suited for users who spend heavily on fuel and want occasional domestic lounge access. It is also a good first card for those who prefer a lower fee but can meet a higher waiver spend. The card’s quarterly Rs 75,000 spend gate for domestic lounges makes it ideal for those who can cluster spends and enjoy lounge benefits.
Overall, if your spending is focused on online shopping and you prefer a lower waiver threshold, go with the HDFC MoneyBack Plus card. If your priority is fuel rewards and some lounge access with a lower fee, the ICICI HPCL Coral card is the clear winner. Skip the HDFC card if you rarely shop online, and avoid the ICICI card if you cannot meet its higher waiver spend or do not value lounge access.
What to Check Before You Apply
- Confirm the quarterly Rs 75,000 spend gate for domestic lounge access on the ICICI HPCL Coral card to ensure you can meet it.
- Understand the redemption value and process for points, as both cards offer points but do not specify conversion rates.
- Carefully calculate the monthly spend required to waive fees on both cards to avoid unexpected charges.
- Be aware of the 3.5% forex markup on both cards if you plan to use them for international transactions.
- Check which domestic airport lounges are accessible with the ICICI card and if they suit your travel routes.

Comments
No comments yet
Be the first to share your experience with this card.