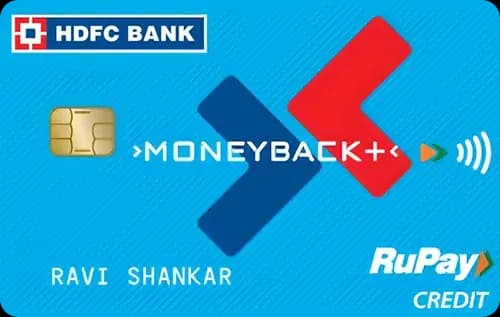
Quick Verdict
- For everyday spending, the Yes Bank Rupay Credit Cardⓘ offers a higher base reward rate, making it the better choice.
- For travel perks, particularly domestic lounges, the Yes Bank Rupay Credit Card stands out with 4 complimentary visits per year, unlike the HDFC Bank MoneyBack Plus Credit Cardⓘ.
- The HDFC Bank MoneyBack Plus Credit Cardⓘ costs Rs 500 annually with a joining fee, but this can be waived with Rs 50,000 annual spend. The Yes Bank Rupay Credit Cardⓘ is lifetime free, making it cheaper to hold.
- Shoppers looking for strong online rewards may prefer the HDFC MoneyBack Plus, while grocery and dining spenders will benefit more from the Yes Bank Rupay. First-time card users and budget-conscious customers should lean towards the Yes Bank Rupay.
Side by Side
| Detail | HDFC Bank MoneyBack Plus Credit Cardⓘ | Yes Bank Rupay Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 500 | Nil (lifetime free) |
| Joining fee | Rs 500 | Nil (lifetime free) |
| Fee waiver on spend | Rs 50,000 | Rs 75,000 |
| Reward rate | 0.5% base, 3.33% online | 1% base, 3% grocery & dining, 1% UPI |
| Reward type | points | points |
| Domestic lounge | None | 4 per year (with Rs 50,000 quarterly spend) |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | first-card, cashback, shopping | upi-rupay, rewards, grocery, first-card, shopping |
Rewards Compared
Spending Rs 10,000 on the HDFC Bank MoneyBack Plus Credit Cardⓘ yields Rs 50 in rewards at the base rate, but if the spend is online, the effective reward rate jumps to Rs 333 per Rs 10,000. This makes it attractive for online shoppers. However, outside this category, the base rewards are quite modest.
On the other hand, the Yes Bank Rupay Credit Cardⓘ delivers Rs 100 per Rs 10,000 at the base level, doubling the HDFC card’s basic return. In grocery and dining categories, this card offers 3% rewards, translating to Rs 300 back on Rs 10,000, which is competitive and covers popular everyday expenses. UPI payments also earn 1%, providing broader usability.
Fees Compared
The HDFC MoneyBack Plus Credit Cardⓘ demands a joining fee of Rs 500 and an annual fee of Rs 500. Both fees can be waived with Rs 50,000 annual spend, equating to about Rs 4,167 monthly. The card’s break-even spend to cover the annual fee through base rewards is approximately Rs 1,00,000.
The Yes Bank Rupay Credit Cardⓘ is lifetime free with no joining or annual fees. Its fee waiver threshold of Rs 75,000 is irrelevant since there are no fees to waive. This clearly positions the Rupay card as a low-cost option. However, to unlock domestic lounge access, cardholders must spend Rs 50,000 quarterly, adding a spending requirement to access that perk.
Which One Should You Pick
Choose the HDFC Bank MoneyBack Plus Credit Cardⓘ if you primarily shop online and want tangible rewards from your spending in that category. This card suits first-time credit card users who want a straightforward cashback model with a manageable fee waiver threshold. However, if you rarely spend online or want lounge access, this card falls short.
The Yes Bank Rupay Credit Cardⓘ is ideal for spenders focused on groceries, dining, and UPI transactions, where its category rewards excel. It is also perfect for those who want a fee-free card with domestic lounge privileges after meeting the quarterly spend gate. First-time users and budget-conscious customers will appreciate its no-fee structure and decent rewards.
Overall, the Yes Bank Rupay Credit Cardⓘ emerges as the more versatile and cheaper-to-hold card with better base rewards and lounge access. The HDFC MoneyBack Plus Credit Cardⓘ is a niche choice for online shopping enthusiasts willing to pay a fee or meet waiver conditions.
What to Check Before You Apply
- Confirm if your spending aligns with the categories where each card offers higher rewards (online vs grocery/dining).
- Understand the redemption value and ease for points earned as both cards use points but may differ in conversion.
- Calculate the monthly spend needed to waive fees on the HDFC MoneyBack Plus card and ensure you can meet it comfortably.
- Consider the 3.5% forex markup on both cards if you travel abroad or spend heavily in foreign currency.
- For the Yes Bank Rupay card, verify the quarterly spend requirement to access the 4 free domestic lounges and whether you will use this benefit.

Comments
No comments yet
Be the first to share your experience with this card.