How Salon MCC Codes Decide Whether Your Credit Card Gives Rewards
Published: 17 October 2026 Category: how-to-guides | cardbuzz
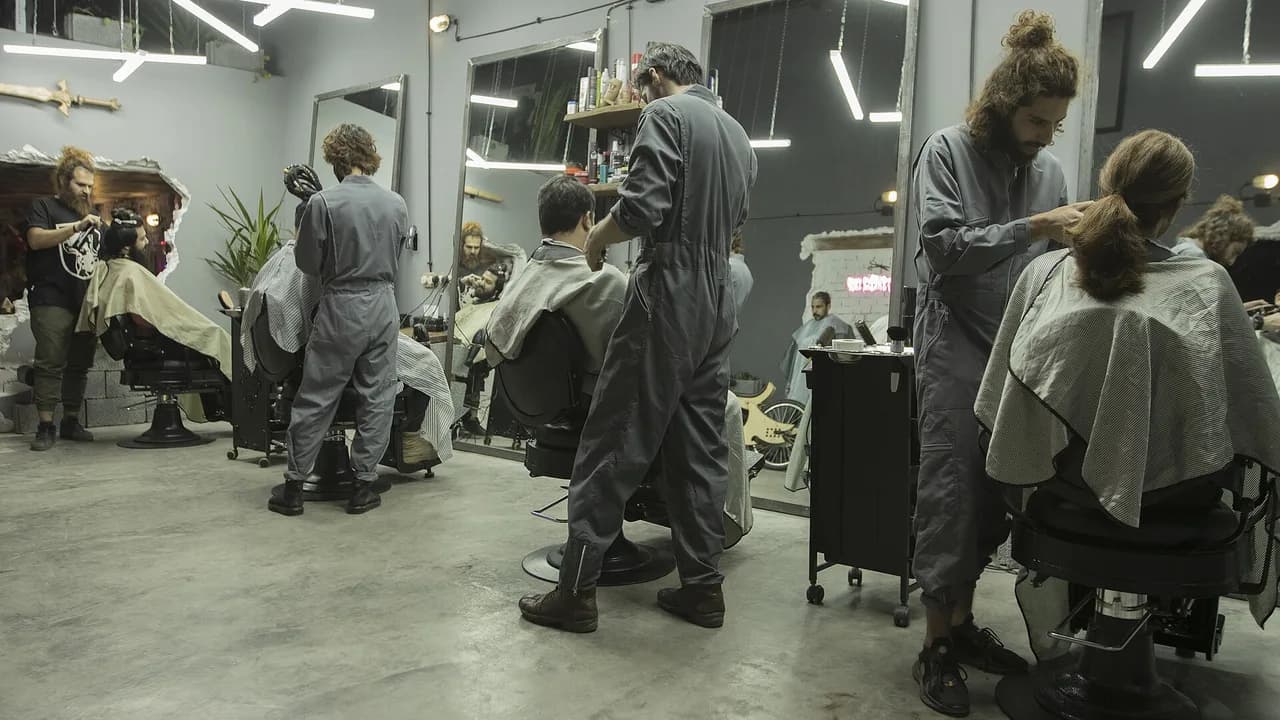
Two customers pay ₹4,000 each at the same salon chain on the same day. One earns 800 reward points; the other earns zero. The difference is not the card tier, the bill size, or the outlet — it is a four-digit number called the Merchant Category Code (MCC) attached to the transaction. This guide explains how salons, spas, and beauty merchants are coded, how that coding interacts with your card's reward terms, and what you can check before you pay.
What an MCC is and why it matters for rewards
Every card transaction carries a Merchant Category Code, assigned by the acquiring bank when the merchant is onboarded. It tells the card network what kind of business the merchant is. Your issuer's reward engine then reads that code and applies the rules in the card's terms: bonus categories, milestone accelerators, and — critically — exclusion lists.
For grooming and beauty spends, the three codes that matter are:
- MCC 7230 — Barber and Beauty Shops. This is the standard code for salons, barbershops, nail studios, and beauty parlours. It is published in Visa's merchant data standards as the barber/beauty category.
- MCC 7298 — Health and Beauty Spas. Day spas, wellness spas, and massage centres typically land here.
- MCC 7297 — Massage Parlours. A separate code that some stand-alone massage outlets carry.
The same salon can show different MCCs depending on how it takes payment. A Lakmé Salon or Enrich outlet swiping your card on its own point-of-sale terminal usually codes as 7230. The same bill paid through an aggregator link (a payment gateway like Razorpay or a salon booking app) may code under the aggregator's own category instead — often a generic business-services code. This is the single most common reason a "salon bill" earns no salon bonus.
How reward exclusions typically treat beauty spends
Most Indian reward credit cards publish a list of MCCs excluded from base rewards or from milestone spend counting. Beauty and wellness codes appear on some of these lists, not all. What you can state with confidence:
- Base rewards almost always apply to 7230 transactions unless the card's terms explicitly list it. Most general-spend cards reward salon bills normally.
- Milestone and accelerator programmes are where exclusions bite. Premium cards that give bonus milestones on travel or dining sometimes exclude "personal care" or "health and beauty" categories from milestone counting. The only reliable source is the card's MITC (Most Important Terms and Conditions) or rewards programme T&C on the issuer's website — for example, HDFC Bank's MITC documents explicitly list excluded merchant categories for its cards, and several Indian issuers exclude wallet loads and certain personal-care spends from rewards entirely.
- Cashback cards are the strictest. Flat-cashback cards frequently exclude MCC 7230-classified transactions from cashback eligibility. If your primary card is a cashback card, read its exclusion schedule before assuming the salon bill earns anything.
The practical rule: never assume. Open the card's rewards T&C, search for "salon", "beauty", "spa", "7230", and "personal care". The search takes ninety seconds and answers the question definitively.
Salon chains vs stand-alone salons: the coding difference
Large chains — Lakmé Salon, Enrich, Looks, Jawed Habib outlets — usually process cards through their own acquiring relationships, so the 7230 code is stable. Stand-alone and home-based salons are more variable:
- QR-code payments (UPI) earn no card rewards at all. If the salon shows you a personal UPI QR and you pay from a bank account, there is no card transaction and no rewards. Some customers put UPI on a credit card via third-party apps, but that route typically codes as a wallet load or P2P transfer — and most issuers exclude wallet loads from rewards (HDFC's MITC, for instance, is explicit on this).
- Payment links sent over WhatsApp code however the link provider is set up. Ask the salon which gateway they use, or check the transaction description in your card statement after the first visit.
- Salon booking apps (Urban Company-type home services, salon-at-home platforms) bill under the platform's merchant account, not the salon's. The MCC reflects the platform, which is often coded as a home-services or generic-services merchant. Your card may treat it as online services rather than a beauty merchant — sometimes better for rewards, sometimes worse; check the first statement.
The online beauty purchase case
Buying cosmetics online is a different MCC story. Nykaa (nykaa.com), Tira (tirabeauty.com), and Sephora India (sephora.in) are e-commerce merchants; their transactions typically code as retail or department-store MCCs (5310/5311 class) rather than beauty-service codes. That means:
- The salon-spa exclusions in your card's terms usually do not apply to these purchases.
- But the transactions are also not "dining" or "travel", so they earn only base rewards unless a bank offer is running.
- Marketplace purchases on Amazon or Flipkart follow the marketplace's coding, not the product category.
One more wrinkle: buying a Nykaa gift card with your credit card and then spending the gift card is, to your issuer, a gift-card purchase — some issuers treat prepaid/voucher purchases as wallet-adjacent and exclude them. Paying the beauty retailer directly is the cleaner route for rewards.
How to verify your own salon's coding
- Pay once, then read the statement. Your card statement or the issuer's app often shows a merchant category descriptor. One ₹500 haircut tells you the MCC behaviour for the whole chain's outlet.
- Call the issuer and ask: "What MCC was my transaction on [date] at [merchant]?" Support agents can see it.
- Cross-check the rewards T&C for that MCC number before a big-ticket treatment (keratin, smoothening, bridal packages run ₹8,000–₹30,000 — worth ninety seconds of reading).
- For chains, test one outlet. MCC coding is usually consistent across a chain's outlets, but franchise outlets sometimes use their own acquiring — Enrich and Looks both run franchise models, so an outlet in another city may code differently.
When the coding works in your favour
Some cards give accelerated rewards on "lifestyle" or "wellness" categories that include 7230/7298. If you spend heavily on grooming — monthly facials, regular hair colour, spa visits — a card with a lifestyle accelerator can out-earn a generic rewards card on the same bills. The math is simple: take your last twelve months of salon and spa statements, total them, and compare (base rate × total) against (accelerated rate × total minus the card's annual fee). Grooming is a recurring, predictable spend category, which makes this one of the easiest reward comparisons to run honestly.
The bottom line
MCC 7230 (salons), 7298 (spas), and 7297 (massage) decide how your issuer sees a grooming transaction. Chains code consistently; aggregators, payment links, and booking apps can change the code; UPI QR payments earn nothing on cards. The ninety-second habit — one test transaction, one look at the statement, one search of the card's exclusion list — is worth more than any generic "best card for salons" list, because the coding of your salon and the terms of your card are the only two inputs that matter.
Comments
No comments yet
Be the first to share your experience with this card.