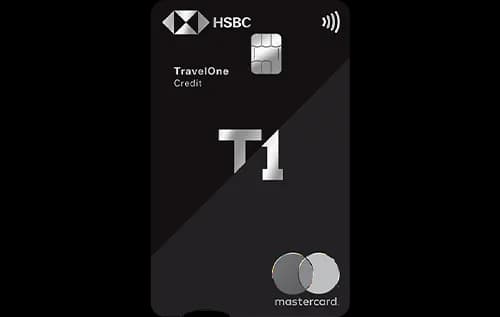
Quick Verdict
- For everyday spending, the Yes Bank Marquee Credit Cardⓘ wins with a higher base reward rate of 1.8%, compared to 1% on the HSBC Travelone Credit Cardⓘ.
- For travel and lounge access, the HSBC Travelone Credit Cardⓘ edges ahead with 8 domestic lounge visits compared to unlimited on Yes Bank but a lower threshold for fee waiver and better travel-related discounts.
- The HSBC Travelone Credit Cardⓘ is cheaper to hold if you spend around Rs 5 lakh annually, as the Yes Bank card requires higher spend to cover fees.
- Pick HSBC Travelone Credit Cardⓘ if you want travel perks and a lower forex markup. Choose Yes Bank Marquee Credit Cardⓘ for higher rewards on online spends and unlimited domestic lounges.
Side by Side
| Detail | HSBC Travelone Credit Cardⓘ | Yes Bank Marquee Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 4,999 | Rs 4,999 |
| Joining fee | Rs 4,999 | Rs 9,999 |
| Fee waiver on spend | Rs 8.00 lakh | Rs 10.00 lakh |
| Reward rate | 1% base; 3% travel & dining | 1.8% base; 3.6% online |
| Reward type | points | points |
| Domestic lounge | 8 per year | Unlimited |
| International lounge | 6 per year | 6 per year |
| Forex markup | 0.99% | 1% |
| Best suited for | travel, rewards, lounge, forex, shopping | rewards, shopping, lounge, forex, premium, travel |
Rewards Compared
The HSBC Travelone Credit Cardⓘ offers a base reward of Rs 100 on Rs 10,000 spent, with elevated 3% return for travel and dining categories, yielding Rs 300. This makes it appealing to frequent travelers and food enthusiasts who can capitalize on these bonus rates. The points are redeemable as travel-related benefits, adding to its travel suitability.
The Yes Bank Marquee Credit Cardⓘ provides a stronger base return of Rs 180 per Rs 10,000 spent, nearly double that of HSBC Travelone, and an even higher 3.6% return on online spends worth Rs 360 per Rs 10,000. This card suits shoppers and online spenders looking for more consistent, higher returns across their spend, though it lacks the specific travel and dining category boosts.
Fees Compared
Both cards have an annual fee of Rs 4,999. The HSBC Travelone Credit Cardⓘ also charges a joining fee of Rs 4,999, while the Yes Bank Marquee Credit Cardⓘ demands double that at Rs 9,999 upfront. Fee waiver thresholds differ significantly: HSBC requires Rs 8 lakh annual spend (about Rs 66,667 monthly), whereas Yes Bank needs Rs 10 lakh annually (about Rs 83,333 monthly).
Regarding break-even, the HSBC card's base reward rate covers its annual fee after Rs 4,99,900 spent, roughly 5 lakh. The Yes Bank card requires only Rs 2,77,722 (about 2.78 lakh) to cover fees due to its higher base rewards. Thus, for lower spenders, the HSBC card's fee waiver is more attainable, while the Yes Bank card rewards higher spenders better despite the steeper joining fee.
Which One Should You Pick
Choose the HSBC Travelone Credit Cardⓘ if you prioritize travel benefits, including multiple domestic and international lounge visits, travel-related discounts, and a lower forex markup of 0.99%. It is ideal for travelers and those spending consistently above Rs 66,667 monthly to avoid fees. Skip this card if your spending is mostly online or lower than Rs 5 lakh annually.
Opt for the Yes Bank Marquee Credit Cardⓘ if you seek higher base rewards, especially on online transactions, plus unlimited domestic lounge access and concierge services. It suits premium shoppers and frequent online spenders comfortable with a higher joining fee and Rs 83,333 monthly spend for fee waivers. Avoid this card if you prefer travel perks or have a lower annual spend.
Overall, the Yes Bank Marquee Credit Cardⓘ wins on rewards and lounge access for online spenders and premium users, while HSBC Travelone Credit Cardⓘ is better for travel enthusiasts and forex spenders who want cost-effective fees.
What to Check Before You Apply
- Confirm if the reward categories have caps or exclusions that limit earning potential.
- Review redemption options carefully to ensure points translate to good value.
- Calculate the monthly spend needed to waive fees to avoid surprises.
- Check the forex markup percentage and if the card suits your international travel habits.
- Verify the domestic and international lounge access locations and partner airports.

Comments
No comments yet
Be the first to share your experience with this card.