Quick Verdict
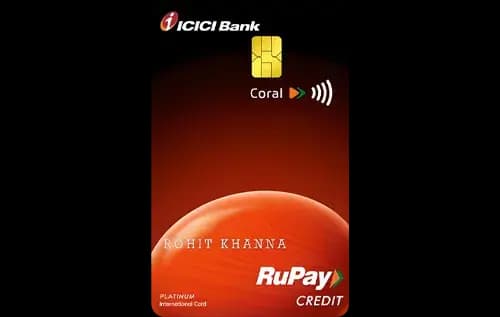
- The ICICI Bank Coral Credit Cardⓘ edges out for everyday spend when factoring in base rewards and category benefits like groceries and utilities.
- For grocery and fuel shopping, the RBL Bank ShopRite Credit Cardⓘ offers significantly higher rewards, making it the better pick for category-focused spenders.
- The RBL ShopRite card is cheaper to hold with no joining or annual fees, while the ICICI Coral card charges Rs 500 for each but offers fee waivers on spend.
- Choose the ICICI Coral card if you value domestic lounge access and dining rewards; go for the RBL ShopRite if you prioritize no fees and high rewards on groceries and fuel.
Side by Side
| Detail | ICICI Bank Coral Credit Cardⓘ | RBL Bank ShopRite Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 500 | Nil (lifetime free) |
| Joining fee | Rs 500 | Nil (lifetime free) |
| Fee waiver on spend | Rs 1.50 lakh | Rs 2.00 lakh |
| Reward rate | 0.5% base, 1% grocery & utilities | 0.4% base, 5% grocery & fuel |
| Reward type | points | points |
| Domestic lounge | 4 per year, Rs 75,000 quarterly spend | None |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | first-card, rewards, dining, lounge | cashback, grocery, fuel, shopping |
Rewards Compared
On a generic Rs 10,000 spend, the ICICI Bank Coral Credit Cardⓘ delivers Rs 50 in rewards at its base rate of 0.5%. This increases to Rs 100 when spending in grocery or utilities categories due to a 1% reward rate. The card’s rewards focus on balanced everyday spending with moderate returns across categories and the added benefit of domestic lounge access, which adds value for frequent travelers or diners.
Conversely, the RBL Bank ShopRite Credit Cardⓘ returns Rs 40 on the same Rs 10,000 base spend at 0.4%. However, it significantly outperforms the Coral card in key categories like grocery and fuel, where it offers a 5% reward rate, translating to Rs 500 per Rs 10,000 spent. This makes the RBL ShopRite highly lucrative for shoppers who prioritize these categories, although it lacks lounge privileges and has a slightly lower base reward rate.
Fees Compared
The ICICI Coral card requires a Rs 500 joining fee and a Rs 500 annual fee. Both fees can be waived if you spend Rs 1.50 lakh annually, which breaks down to Rs 12,500 monthly. The RBL ShopRite card is free for life with no joining or annual fees, but it demands a higher spend of Rs 2.00 lakh annually (Rs 16,667 monthly) to maintain fee waiver status, which is effectively moot since fees do not apply.
To justify the Rs 500 higher annual fee on the Coral card based on its higher base reward rate, a spend of about Rs 5.00 lakh annually is needed to cover this cost purely through rewards. This considerable spend threshold means casual users may find the RBL ShopRite’s no-fee structure more attractive despite lower base returns.
Which One Should You Pick
The ICICI Bank Coral Credit Cardⓘ is best suited for first-time credit card users and those who want a balanced card that rewards everyday spending moderately with additional benefits. Its domestic lounge access and rewards in utilities and dining categories add distinct value for users who also travel domestically. However, users not planning to meet the Rs 1.50 lakh annual spend to waive fees should consider whether the benefits justify the cost.
The RBL Bank ShopRite Credit Cardⓘ fits shoppers who frequently spend on groceries and fuel and want to maximize rewards in these categories without worrying about fees. Its lifetime free status is compelling for budget-conscious users who want straightforward cashback-like rewards. However, it does not offer lounge access or significant rewards outside its focus categories, so travelers or diners may find it lacking.
In summary, pick the ICICI Coral cardⓘ if you value lounge access and a balanced reward structure with fee waivers at moderate spend levels. Opt for the RBL ShopRite cardⓘ if you want a fee-free card that delivers high rewards on groceries and fuel but do not require travel perks. Skip the Coral card if you cannot meet the fee waiver spend; skip the ShopRite card if you want travel benefits or broader rewards.
What to Check Before You Apply
- Confirm the quarterly Rs 75,000 domestic lounge spend gate on the ICICI Coral card to ensure you can access lounges without missing out.
- Understand the redemption terms for points as both cards use points, but value can differ based on the issuer’s program.
- Calculate your typical monthly spend against the Rs 12,500 and Rs 16,667 thresholds to see which fee waiver is realistic for you.
- Be aware that both cards charge the standard 3.5% forex markup, so neither is ideal for heavy foreign currency spend.

Comments
No comments yet
Be the first to share your experience with this card.