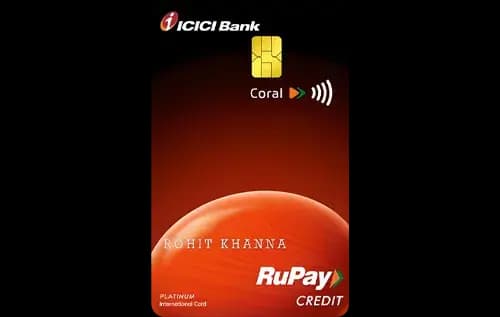
Quick Verdict
- The Yes Prosperity Edge Credit Cardⓘ wins for everyday spend with a higher base reward rate and better category returns.
- Both cards offer domestic lounge access, but Yes Prosperity Edge has a lower quarterly spend gate for lounges, making it easier to access.
- The ICICI Bank Coral Credit Cardⓘ is cheaper to hold if you spend less than about Rs 1.00 lakh annually; otherwise, Yes Prosperity Edge’s higher rewards justify its slightly higher fees.
- Choose ICICI Coral if you are a first-time cardholder looking for simple rewards and occasional lounge visits. Opt for Yes Prosperity Edge if you value higher rewards on dining and groceries and can meet the spend threshold for fee waiver and lounge access.
Side by Side
| Detail | ICICI Bank Coral Credit Cardⓘ | Yes Prosperity Edge Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 500 | Rs 599 |
| Joining fee | Rs 500 | Rs 599 |
| Fee waiver on spend | Rs 1.50 lakh | Rs 1.00 lakh |
| Reward rate | 0.5% | 0.8% |
| Reward type | Points | Points |
| Domestic lounge | 4 per year | 4 per year |
| International lounge | None | None |
| Lounge spend gate | Rs 75,000 quarterly | Rs 50,000 quarterly |
| Forex markup | 3.5% | 3.5% |
| Best suited for | First-card, rewards, dining, lounge | Rewards, dining, first-card, lounge, shopping |
| Welcome benefit | None | Vouchers worth Rs 1,000 |
| Golf access | Not available | Available |
Rewards Compared
Spending Rs 10,000 on the ICICI Bank Coral Credit Cardⓘ earns Rs 50 back at the base rate of 0.5%. If your spend is in groceries or utilities, the rate doubles to 1%, increasing returns to Rs 100 per Rs 10,000. This card rewards well in these essential categories but does not offer enhanced benefits for dining or shopping.
In contrast, the Yes Prosperity Edge Credit Cardⓘ offers a stronger base reward of 0.8%, meaning Rs 80 back on Rs 10,000 spent. Its category rewards for dining and grocery double to 2%, translating to Rs 200 back on Rs 10,000 spend in these categories. This makes Yes Prosperity Edge more lucrative for those who frequently dine out or shop for groceries, delivering better returns in popular spending areas.
Fees Compared
The ICICI Bank Coral Credit Cardⓘ has an annual and joining fee of Rs 500 each, with a fee waiver threshold of Rs 1.50 lakh annual spend (about Rs 12,500 monthly). You need to spend roughly Rs 1.00 lakh annually to cover the fee purely through the base reward rate.
Yes Prosperity Edge has a slightly higher joining and annual fee of Rs 599 each but a lower waiver threshold of Rs 1.00 lakh annually (about Rs 8,333 monthly). Due to its higher 0.8% base reward rate, you only need to spend around Rs 74,875 annually for the rewards to offset the fees. The extra Rs 99 fee for Yes Prosperity Edge is justified if you can spend an additional Rs 33,000 or more annually compared to ICICI Coral to make the rate difference worthwhile.
Which One Should You Pick
Choose the ICICI Bank Coral Credit Cardⓘ if you are a new cardholder looking for a straightforward rewards card with modest fees and decent returns on grocery and utility spends. It is well suited for those who want occasional domestic lounge access without committing to high monthly spends. Skip this card if you spend heavily on dining or grocery and want higher reward rates.
The Yes Prosperity Edge Credit Cardⓘ is ideal if you prioritize rewards on dining and grocery spends and can comfortably meet its fee waiver and lounge access spend requirements. Its welcome vouchers and golf access add value for lifestyle-oriented users. Avoid this card if your spending is irregular or below Rs 1.00 lakh annually, as the fees may not be justified.
Overall, Yes Prosperity Edge offers better value for frequent spenders focused on dining and groceries, while ICICI Coral is a sensible pick for cautious or new spenders wanting simple benefits and lounge access.
What to Check Before You Apply
- Confirm the quarterly lounge spend gate, as ICICI requires Rs 75,000 while Yes Bank asks for Rs 50,000, affecting lounge access.
- Check for caps on category rewards or point accumulation to avoid missing out on returns.
- Understand the fee waiver spend thresholds and how monthly spend aligns with your budget to avoid paying fees unnecessarily.
- Be aware of the 3.5% forex markup fee on international transactions, making these cards less ideal for heavy foreign currency spenders.

Comments
No comments yet
Be the first to share your experience with this card.