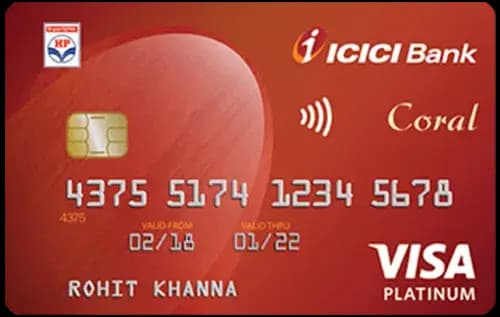
Quick Verdict
- The ICICI HPCL Super Saver Credit Card ⓘ wins for everyday spending with a superior base reward rate of 1% compared to 0.5% on the Coral.
- Both cards match on fuel rewards at 5%, but the Super Saver extends this 5% rate to utilities and grocery, making it better for diverse categories.
- The ICICI Bank HPCL Coral Credit Card ⓘ is cheaper to hold with a lower annual fee of Rs 199 versus Rs 500 on the Super Saver.
- Pick the Coral ⓘ if you want a low-fee card primarily for fuel and light shopping, and the Super Saver ⓘ if you spend across fuel, groceries, and utilities and want higher rewards despite the higher fee.
Side by Side
| Detail | ICICI Bank HPCL Coral Credit Card ⓘ | ICICI HPCL Super Saver Credit Card ⓘ |
|---|---|---|
| Annual fee | Rs 199 | Rs 500 |
| Joining fee | Rs 199 | Rs 500 |
| Fee waiver on spend | Rs 1.50 lakh | Rs 1.50 lakh |
| Reward rate | 0.5% base, 5% fuel | 1% base, 5% fuel, 5% utilities, 5% grocery |
| Reward type | points | points |
| Domestic lounge | 4 per year | 4 per year |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | fuel, first-card, shopping | fuel, grocery, cashback, shopping, lounge |
Rewards Compared
With Rs 10,000 spent, the ICICI Bank HPCL Coral Credit Card ⓘ returns Rs 50 at the base rate of 0.5%. However, if you spend specifically on fuel, the return jumps to Rs 500 owing to the 5% fuel category rate. This makes the Coral ⓘ an excellent choice for those whose spending is concentrated in fuel but modest elsewhere.
On the other hand, the ICICI HPCL Super Saver Credit Card ⓘ doubles the base rate to 1%, yielding Rs 100 on Rs 10,000 spend. It matches the Coral ⓘ in fuel returns with Rs 500, but importantly extends the 5% reward rate to utilities and groceries as well, also returning Rs 500 on Rs 10,000 spent in those categories. This breadth makes the Super Saver ⓘ more rewarding for a diversified monthly spend.
Fees Compared
The Coral ⓘ charges a joining fee and annual fee of Rs 199 each, with a waiver if you spend Rs 1.50 lakh annually, which breaks down to Rs 12,500 monthly. The Super Saver ⓘ demands a higher joining and annual fee at Rs 500 each but shares the same waiver threshold of Rs 1.50 lakh annually.
To justify the higher Rs 301 annual fee difference, you need to spend an extra Rs 60,200 annually on the Super Saver ⓘ to cover that fee via the reward rate difference. For spenders below this level, the Coral ⓘ offers better value. For those who exceed it, the Super Saver ⓘ delivers more rewards overall despite the higher fee.
Which One Should You Pick
Choose the ICICI Bank HPCL Coral Credit Card ⓘ if you want a low-cost entry-level card focused on fuel and occasional shopping rewards. It suits first-time cardholders or those with moderate spend who want to avoid heavy fees and still get decent fuel rewards.
Opt for the ICICI HPCL Super Saver Credit Card ⓘ if you spend significantly on fuel, groceries, and utilities and can comfortably meet the Rs 1.50 lakh annual waiver threshold. The higher base and category reward rates justify the higher fee for more intensive spenders who want comprehensive value including lounge access.
If you rarely spend on utilities or groceries or want to keep fees minimal, skip the Super Saver ⓘ. If your spend is low and you want a simple fuel rewards card with minimal fees, avoid the Super Saver and pick the Coral ⓘ.
What to Check Before You Apply
- Confirm the Rs 75,000 quarterly spend gate to access the 4 free domestic lounges per year on both cards.
- Understand the actual redemption value of points since both cards earn points, not direct cashback.
- Ensure you can meet the Rs 12,500 monthly waiver spend to avoid annual fees.
- Beware of the 3.5% forex markup rate on foreign currency spends, which is quite high.
- Check which airports and lounges are accessible with the domestic lounge benefit.

Comments
No comments yet
Be the first to share your experience with this card.