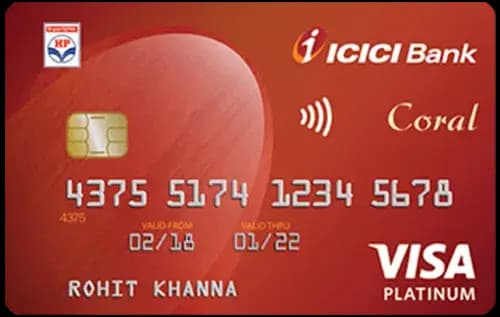
Quick Verdict
- For everyday spending, both the ICICI Bank HPCL Coral Credit Cardⓘ and the IDFC First Millennia Cardⓘ offer the same base reward rate of 0.5%, making them equal in general returns.
- The ICICI HPCL Coralⓘ card stands out for fuel purchases with an effective 5% reward rate, making it the better choice for fuel spenders.
- The IDFC First Millenniaⓘ card is cheaper to hold since it has no joining or annual fees, whereas the ICICI Coralⓘ charges Rs 199 for both, which can be waived only on Rs 1.5 lakh annual spend.
- Choose the ICICI Coralⓘ if you prioritize fuel rewards and occasional domestic lounge access with moderate spending. Pick the IDFC Millenniaⓘ if you want a lifetime free card suitable for new cardholders and regular shopping without worrying about fees.
Side by Side
| Detail | ICICI Bank HPCL Coral Credit Cardⓘ | IDFC First Millennia Cardⓘ |
|---|---|---|
| Annual fee | Rs 199 | Nil (lifetime free) |
| Joining fee | Rs 199 | Nil (lifetime free) |
| Fee waiver on spend | Rs 1.50 lakh | None |
| Reward rate | 0.5% base, 5% fuel | 0.5% base |
| Reward type | Points | Points |
| Domestic lounge | 4 per year | 4 per year |
| International lounge | None | None |
| Lounge spend gate | Rs 75,000 quarterly | Rs 20,000 monthly |
| Forex markup | 3.5% | 3.5% |
| Best suited for | Fuel, first-card, shopping | Lifetime free, first-card, shopping |
Rewards Compared
Both the ICICI Bank HPCL Coral Credit Cardⓘ and the IDFC First Millennia Cardⓘ offer a base reward rate of 0.5%, which translates into Rs 50 back on every Rs 10,000 spent on general purchases. This parity means that for everyday spending outside of specific categories, neither card offers a significant advantage over the other. However, the ICICI Coralⓘ card shines in the fuel category, offering a robust 5% return which equates to Rs 500 for every Rs 10,000 spent on fuel. This elevated rate makes it particularly attractive for customers who have significant fuel expenses. The IDFC Millenniaⓘ card does not offer category-specific higher rewards but compensates with a straightforward and consistent cashback structure.
In terms of welcome benefits, the IDFC First Millenniaⓘ card provides an initial 5% cashback on the first EMI spend up to Rs 1,000, along with additional vouchers worth Rs 500 on spending Rs 5,000 within the first 30 days. The ICICI Coralⓘ card offers an activation fuel benefit that complements its fuel rewards theme, though no exact value is specified. Overall, regular spenders focused on fuel will find the ICICI Coralⓘ more rewarding, while those seeking a fee-free, no-fuss card with some welcome perks may prefer the IDFC Millenniaⓘ.
Fees Compared
The ICICI Bank HPCL Coral Credit Cardⓘ levies both a joining fee and an annual fee of Rs 199 each. However, these fees are waived if the cardholder spends Rs 1.50 lakh annually, which breaks down to Rs 12,500 per month. For cardholders who spend less than this threshold, the fees effectively reduce the net rewards earned. The card's break-even spend to cover the annual fee at the base reward rate is Rs 39,800, meaning if a user spends below this amount on non-fuel categories, the fee outweighs the base cashback.
In contrast, the IDFC First Millennia Cardⓘ boasts a lifetime free model with no joining or annual fees, making it a highly economical choice for users who prefer to avoid any fee commitments. This zero-fee structure is attractive for first-time cardholders or those with moderate spending who want to avoid penalty fees. However, the IDFC card requires a lower spend gate of Rs 20,000 monthly for domestic lounge access compared to Rs 75,000 quarterly on the ICICI card.
Neither card offers international lounge access, and both charge a 3.5% forex markup on foreign currency transactions, which is standard in the Indian credit card market.
Which One Should You Pick
The ICICI Bank HPCL Coral Credit Cardⓘ is best suited for individuals who have significant fuel expenses or want a card that rewards fuel spending heavily. It is also a good fit for those seeking domestic lounge access and who are willing to meet the Rs 1.50 lakh annual spend to waive the fees. This card is a strong contender for first-time credit card users who also shop regularly and want some additional perks.
The IDFC First Millennia Cardⓘ is ideal for users looking for a no-annual-fee, no-joining-fee option that still offers a decent 0.5% base cashback on everyday spending. It is perfect for first-time cardholders who want to avoid fee complexities while enjoying occasional lounge access with a lower spend gate. The welcome benefits add extra value for new users who plan to use EMI options early on.
In conclusion, fuel spenders and those comfortable with a modest annual fee should choose the ICICI Coralⓘ card. Everyone else, especially fee-sensitive users or those seeking a simple, lifetime free card, should opt for the IDFC Millenniaⓘ. Those with minimal fuel spending or who cannot meet the fee waiver threshold should skip the ICICI Coralⓘ to avoid paying fees without adequate reward returns.
What to Check Before You Apply
- Verify the quarterly Rs 75,000 and monthly Rs 20,000 spend gates for domestic lounge access and whether your spending pattern meets these thresholds.
- Understand the redemption value and rules of points since both cards use a points system but details on redemption flexibility are not specified.
- Be clear on the annual fee waiver math on the ICICI Coralⓘ card to avoid surprises if your spend fluctuates below Rs 1.50 lakh.
- Both cards charge a 3.5% forex markup; frequent international travelers should consider this cost or look for cards with lower forex fees.
- Check which airports the domestic lounge access applies to and if these lounges suit your travel habits.

Comments
No comments yet
Be the first to share your experience with this card.