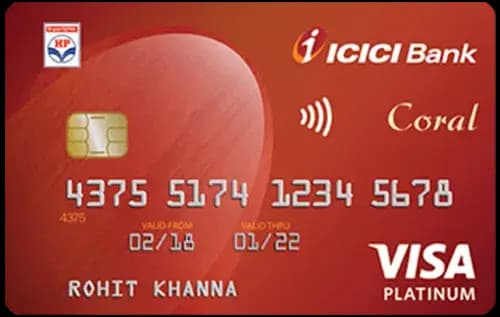
Quick Verdict
- For everyday spending, the IDFC First Wow Credit Cardⓘ offers a higher base reward rate and no annual fees, making it the better choice.
- The ICICI Bank HPCL Coral Credit Cardⓘ wins for fuel purchases, delivering a strong 5% return on fuel spends.
- The HPCL Coral card offers domestic lounge access, which the Wow card lacks, but only after meeting a quarterly spend gate of Rs 75,000.
- Choose the HPCL Coral if you frequently spend on fuel and value lounge visits; pick the Wow card for no-fee lifetime use, forex transactions, and higher base rewards.
Side by Side
| Detail | ICICI Bank HPCL Coral Credit Cardⓘ | IDFC First Wow Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 199 | Nil (lifetime free) |
| Joining fee | Rs 199 | Nil (lifetime free) |
| Fee waiver on spend | Rs 1.50 lakh | None |
| Reward rate | 0.5% base, 5% on fuel | 1% base, 1% on online spend |
| Reward type | points | points |
| Domestic lounge | 4 per year (Rs 75,000 quarterly spend gate) | None |
| International lounge | None | None |
| Forex markup | 3.5% | 0% |
| Best suited for | fuel, first-card, shopping | lifetime-free, first-card, student, forex, dining, shopping |
Rewards Compared
Spending Rs 10,000 on the ICICI Bank HPCL Coral Credit Cardⓘ yields Rs 50 back at the base rate, but if the spend is on fuel, the return jumps sharply to Rs 500. This makes it an excellent choice for those whose major expense is fuel. Other categories earn just 0.5%, so rewards outside fuel are modest.
In contrast, the IDFC First Wow Credit Cardⓘ offers a flat 1% return on all spending, including Rs 100 per Rs 10,000 on online purchases. While it lacks elevated category bonuses like fuel, its higher base rate means consistent rewards for everyday and diverse spends. This card is thus more versatile, especially for those who do not want to track category spends.
Fees Compared
The HPCL Coral card charges a joining and annual fee of Rs 199 each. The Rs 199 annual fee is waived if you spend at least Rs 1.50 lakh annually, which breaks down to Rs 12,500 per month. The break-even spend to cover the fee through base rewards alone is about Rs 39,800 annually.
The Wow card has no joining or annual fees, making it attractive for users who want a no-cost credit card. There is no fee waiver to track, which simplifies usage. For someone spending less than Rs 1.50 lakh annually or who dislikes fee management, the Wow card is clearly cheaper.
Which One Should You Pick
If you primarily spend on fuel and can maintain Rs 75,000 quarterly on the HPCL Coral card to access four domestic lounges annually, this card is a solid pick. It’s also suitable if you want a first credit card with some fuel perks and don’t mind paying or waiving a small annual fee. However, the 3.5% forex markup and modest base reward rate limit its appeal for international or diversified spenders.
The IDFC First Wow Credit Card suits students, first-time cardholders, and those who want a lifetime-free credit card without worrying about fees. Its zero forex markup makes it ideal for forex and international spends. The higher 1% base reward rate is beneficial for everyday transactions, dining, and online shopping. But if you want lounge access or fuel-specific rewards, this card falls short.
In a decisive call, pick the IDFC First Wow Credit Cardⓘ for everyday use, forex, and no fees. Opt for the ICICI Bank HPCL Coral Credit Cardⓘ only if fuel rewards and domestic lounge access are priorities. Skip the Wow card if you want lounge privileges or fuel bonuses, and skip the HPCL Coral card if you want no fees or international spending benefits.
What to Check Before You Apply
- Confirm the quarterly Rs 75,000 spend gate on the HPCL Coral card for lounge access; it may be high for some users.
- Check the redemption process and value of points, as both cards use points but details on redemption value are limited.
- For the HPCL Coral, ensure you can meet Rs 12,500 monthly spend to waive the annual fee; otherwise, fees may outweigh rewards.
- If you plan foreign currency spends, the Wow card’s zero forex markup is advantageous; the Coral card’s 3.5% markup is expensive.

Comments
No comments yet
Be the first to share your experience with this card.