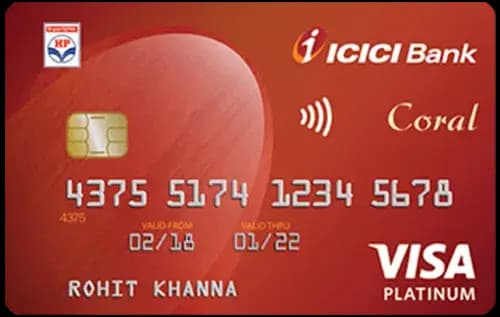
Quick Verdict
- For everyday spend, both the ICICI Bank HPCL Coral Credit Card ⓘ and the LIC Classic Credit Card ⓘ deliver the same base reward rate of 0.5%, making them equally rewarding for general purchases.
- When it comes to fuel expenses, the ICICI Bank HPCL Coral Credit Card ⓘ stands out with a 5% reward rate, ideal for heavy fuel spenders, while the LIC Classic Credit Card ⓘ does not offer category bonuses.
- The LIC Classic Credit Card ⓘ is cheaper to hold, with no joining or annual fees, compared to the ICICI Bank HPCL Coral Credit Card ⓘ which charges Rs 199 for both joining and annual fees but offers a waiver on Rs 1.50 lakh annual spend.
- Choose the ICICI Bank HPCL Coral Credit Card ⓘ if you want strong fuel rewards and occasional domestic lounge access, and pick the LIC Classic Credit Card ⓘ for a truly no-fee, lifetime-free option with some lounge benefits.
Side by Side
| Detail | ICICI Bank HPCL Coral Credit Card ⓘ | LIC Classic Credit Card ⓘ |
|---|---|---|
| Annual fee | Rs 199 | Nil (lifetime free) |
| Joining fee | Rs 199 | Nil (lifetime free) |
| Fee waiver on spend | Rs 1.50 lakh | None |
| Reward rate | 0.5% base, 5% on fuel | 0.5% base |
| Reward type | Points | Points |
| Domestic lounge | 4 per year | 2 per year |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | Fuel, first-card, shopping | Lifetime-free, first-card, lounge |
Rewards Compared
The ICICI Bank HPCL Coral Credit Card ⓘ offers a base reward of Rs 50 on Rs 10,000 spent, equating to 0.5% cashback in points. However, when spending on fuel, it delivers a much stronger 5% effective return, which means Rs 500 back on the same Rs 10,000. This makes it an excellent choice for users who spend significantly on fuel and want to maximise rewards in that category. For other purchases, it matches the standard 0.5% rate.
The LIC Classic Credit Card ⓘ also provides a 0.5% base reward rate on all spend, yielding Rs 50 on Rs 10,000, but it does not offer any category-specific enhanced rates. Its strength lies in being a simple, no-fee card that rewards all spending equally. Neither card offers international lounge access or differentiated rewards beyond the fuel category for ICICI HPCL Coral.
Fees Compared
The ICICI Bank HPCL Coral Credit Card ⓘ charges a joining fee and an annual fee of Rs 199 each. These fees are waived if you spend Rs 1.50 lakh annually, which translates to about Rs 12,500 per month. This waiver threshold means moderate to heavy spenders can avoid fees completely. The break-even spend to cover the Rs 199 annual fee through base rewards alone is Rs 39,800 annually, calculated on the 0.5% base reward rate.
In contrast, the LIC Classic Credit Card ⓘ is a lifetime free card with no joining or annual fees, making it cost-effective for all types of users, especially those with lower spends or who want a fee-free card without conditions. Neither card offers fee waivers on monthly or quarterly spend beyond these points.
Which One Should You Pick
Pick the ICICI Bank HPCL Coral Credit Card ⓘ if you are a fuel spender looking for a rewarding category bonus and do not mind paying a small fee that can be waived with reasonable spend. It also suits shoppers who want some domestic lounge access with a quarterly spend gate of Rs 75,000. However, if you rarely spend on fuel or cannot meet the waiver threshold, the fees might not justify this card.
Choose the LIC Classic Credit Card ⓘ if you want a truly fee-free card with straightforward rewards and some domestic lounge access capped at two visits per year. This card is ideal as a first credit card or for users who value no fees and simple rewards. It lacks category bonuses, so it is less attractive for targeted spenders.
In summary, fuel and lounge enthusiasts with moderate to high spend should lean towards the ICICI Bank HPCL Coral Credit Card ⓘ, while those seeking a lifetime free, no-hassle card should opt for the LIC Classic Credit Card ⓘ. Avoid the Coral if you cannot meet the fee waiver or do not spend on fuel. Skip the LIC Classic if you want high category rewards or international lounge access.
What to Check Before You Apply
- Confirm the fee waiver spend thresholds and ensure your monthly or annual spend meets them to avoid fees on the Coral card.
- Check if the domestic lounge access caps and quarterly or monthly spend gates align with your usage patterns.
- Be aware of the 3.5% forex markup on both cards for foreign currency transactions, which is standard but costly for international travelers.
- Verify if any reward caps or redemption value limits apply to points earned, especially for the Coral card with its category bonuses.

Comments
No comments yet
Be the first to share your experience with this card.