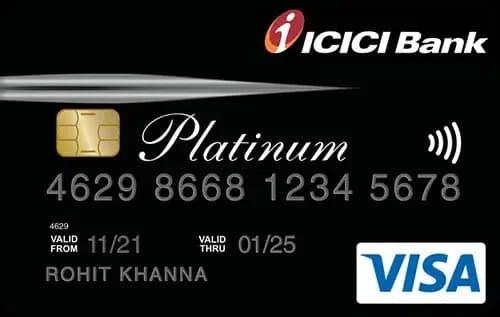
Quick Verdict
- The ICICI Bank Platinum Chip Credit Card ⓘ wins for everyday spend with a higher base reward rate and zero fees.
- The BPCL SBI Credit Card ⓘ is the better choice for fuel spenders, offering a strong category reward of 4.25% on fuel.
- ICICI’s card is cheaper to hold as it has no joining or annual fee, unlike the BPCL SBI card which charges Rs 499 unless you spend Rs 1,00,000 annually.
- Choose ICICI Platinum Chip for a no-fee, simple rewards card mainly for dining and shopping; pick BPCL SBI if you frequently buy fuel and can meet the fee waiver threshold.
Side by Side
| Detail | ICICI Bank Platinum Chip Credit Card ⓘ | BPCL SBI Credit Card ⓘ |
|---|---|---|
| Annual fee | Nil (lifetime free) | Rs 499 |
| Joining fee | Nil (lifetime free) | Rs 499 |
| Fee waiver on spend | Rs 1.00 lakh annually | |
| Reward rate | 0.5% | 0.25% |
| Reward type | points | points |
| Domestic lounge | None | None |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | lifetime-free, first-card, dining, shopping | fuel, first-card |
Rewards Compared
The ICICI Bank Platinum Chip Credit Card ⓘ offers a straightforward base reward of 0.5%, translating to Rs 50 back on every Rs 10,000 spent. This reward rate holds steady across most categories, including utilities, but it does not offer elevated category-specific returns beyond this. The card’s simplicity and zero fees make it attractive for everyday expenses like dining and shopping, where you earn consistent returns without worrying about category restrictions.
In contrast, the BPCL SBI Credit Card ⓘ has a lower base reward of 0.25%, which gives Rs 25 on Rs 10,000 spent generally. However, it shines with a 4.25% reward rate on fuel purchases, offering Rs 425 back on Rs 10,000 spent in that category, making it a powerful card for fuel-heavy users. It also offers 1.25% back (Rs 125) on online spends, which is better than its base rate but still below ICICI’s flat 0.5%. For users with significant fuel expenses, the BPCL SBI card creates much higher value despite the lower base rate.
Fees Compared
The ICICI Bank Platinum Chip Credit Card ⓘ impresses with no joining fee and no annual fee, making it a completely free card to hold for life. There is no requirement to meet any spend threshold to avoid fees, providing hassle-free ownership.
The BPCL SBI Credit Card ⓘ charges Rs 499 each for joining and annual fees, but these can be waived if the cardholder spends Rs 1,00,000 annually, or about Rs 8,333 monthly. For those unable to meet this threshold, the fees are unavoidable. The card’s break-even point to cover the Rs 499 annual fee at its base reward rate is roughly Rs 1,99,600 spend, which is nearly Rs 2 lakh and quite high. However, if the user spends mainly on fuel at 4.25% rewards, the fee is justified at much lower spend levels.
Which One Should You Pick
Pick the ICICI Bank Platinum Chip Credit Card ⓘ if you want a truly no-fee card that rewards you evenly on all spends. It suits first-time cardholders, those wanting lifetime free usage, and people who spend on dining and shopping but do not want to track categories or meet minimum spends. This card is the best low-maintenance option with a decent flat reward.
The BPCL SBI Credit Card ⓘ is ideal if you regularly purchase fuel and can meet or exceed the Rs 1,00,000 annual spend to waive the fee. Its excellent 4.25% reward on fuel makes it very compelling for drivers and two-wheeler owners who want to maximize savings on petrol or diesel. It also suits first-card buyers who expect fuel to be their primary spend category.
If you are not a heavy fuel spender or cannot meet the waiver threshold, skip BPCL SBI to avoid paying Rs 499 in fees for just 0.25% base rewards. Conversely, if you want the highest possible rewards on fuel and spend enough to waive fees, skip ICICI Platinum Chip as BPCL SBI will give you more value.
What to Check Before You Apply
- Confirm if your monthly or annual spend meets the fee waiver threshold on the BPCL SBI card to avoid paying fees.
- Understand the redemption process for rewards points on both cards to ensure you get full value.
- Check whether foreign transactions incur the 3.5% forex markup on both cards if you plan to use them abroad.
- Neither card offers domestic or international lounge access, so do not expect travel perks.
- Be aware of any reward caps or exclusions that may limit your effective return, especially on the BPCL SBI card’s category bonuses.

Comments
No comments yet
Be the first to share your experience with this card.