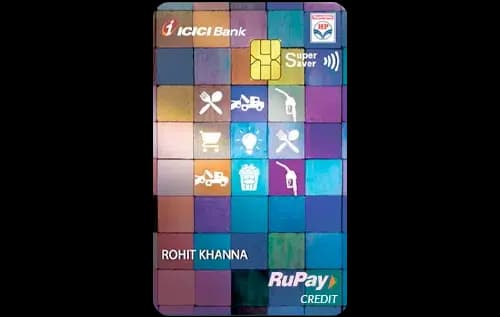
Quick Verdict
- The ICICI HPCL Super Saver Credit Cardⓘ wins for everyday spending with a higher base reward rate and strong category returns on fuel, utilities, and grocery.
- The HDFC Bank Rupay IRCTC Credit Cardⓘ is better suited for travel-focused users, offering higher rewards on travel spends and more domestic lounge visits annually.
- The HDFC card is cheaper to hold with no annual fee, while the ICICI card charges Rs 500 annually but offers a waiver on Rs 1.50 lakh yearly spend.
- Pick the ICICI card if your spend is heavy on fuel, groceries, and utilities and you want some lounge access. Choose the HDFC Rupay IRCTC card if you prioritize travel rewards, want more lounge visits, or want a no-fee card.
Side by Side
| Detail | ICICI HPCL Super Saver Credit Cardⓘ | HDFC Bank Rupay IRCTC Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 500 | Nil (lifetime free) |
| Joining fee | Rs 500 | Rs 500 |
| Fee waiver on spend | Rs 1.50 lakh annual (Rs 12,500 per month) | Rs 1.50 lakh annual (Rs 12,500 per month) |
| Reward rate | 1% base | 0.5% base |
| Reward type | Points | Points |
| Domestic lounge | 4 per year (Rs 75,000 quarterly spend gate) | 8 per year (Rs 75,000 quarterly spend gate) |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | Fuel, grocery, cashback, shopping, lounge | Travel, UPI Rupay, first card |
Rewards Compared
Spending Rs 10,000 on the ICICI HPCL Super Saver Credit Cardⓘ earns Rs 100 back at the base rate of 1%. However, this card really shines in its category spends like fuel, groceries, and utilities where the effective reward rate jumps to 5%, giving Rs 500 back on Rs 10,000 spent in these categories. This makes it a strong choice for users who spend heavily on these essentials.
The HDFC Bank Rupay IRCTC Credit Cardⓘ returns Rs 50 on Rs 10,000 spent at its base rate of 0.5%. It offers a lucrative 5% reward in the travel category, matching the ICICI card’s category returns. Additionally, it provides 1% returns on UPI spends, which is a unique perk for digital payments. Overall, while the base rate is lower, it rewards travel spenders well.
Fees Compared
The ICICI card charges an annual fee of Rs 500 plus a joining fee of Rs 500. The annual fee is waived if you spend Rs 1.50 lakh annually, which breaks down to Rs 12,500 per month. The HDFC Rupay IRCTC card has no annual fee at all but charges a Rs 500 joining fee. Both cards share the same fee waiver on spend threshold, but the HDFC card’s lifetime free status on annual fees makes it more cost-effective for low to moderate spenders.
The ICICI card’s higher base reward rate requires an additional Rs 1,00,000 in spend compared to the HDFC card to cover the extra Rs 500 annual fee, indicating it is more suited for users with higher spend who can benefit from the superior category rewards.
Which One Should You Pick
Choose the ICICI HPCL Super Saver Credit Cardⓘ if you spend heavily on fuel, groceries, and utilities and want decent domestic lounge access. This card is ideal for users looking for strong category rewards with moderate fees that can be waived with decent annual spending.
The HDFC Bank Rupay IRCTC Credit Cardⓘ suits those who prioritize travel rewards, want more domestic lounge visits per year, or prefer a no-annual-fee card to keep costs low. It also works well as a first credit card or for users who transact frequently via UPI and want some rewards there.
If you do not spend regularly on fuel or groceries, skip the ICICI card as the fee might not justify the lower base reward. Conversely, if you want strong everyday rewards on essentials and some lounge benefits, the HDFC card’s lower base rate and limited categories may feel restrictive.
What to Check Before You Apply
- Confirm the quarterly Rs 75,000 lounge spend gate to ensure you qualify for free lounge access.
- Check if the bonus reward points and welcome benefits have redemption caps or validity periods.
- Verify that your monthly spend comfortably meets the Rs 12,500 fee waiver threshold to avoid paying the annual fee on the ICICI card.
- Be aware of the 3.5% forex markup on both cards if you plan to use them extensively for international transactions.
- Confirm the number of lounges and locations available domestically to see if they match your travel patterns.

Comments
No comments yet
Be the first to share your experience with this card.