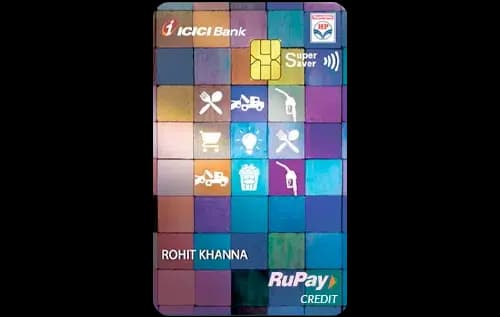
Quick Verdict
- The ICICI HPCL Super Saver Credit Card ⓘ wins for everyday spend with a 1% base reward rate and 5% on fuel, utilities, and grocery categories.
- The ICICI HPCL Super Saver Credit Card ⓘ also offers domestic lounge access, making it better for occasional lounge users, while the ICICI Bank Platinum Chip Credit Card ⓘ provides no lounge benefits.
- The ICICI Bank Platinum Chip Credit Card ⓘ is cheaper to hold with no joining or annual fees, making it ideal for low spenders or first-time cardholders.
- Choose the Super Saver card ⓘ if you spend heavily on fuel, groceries, or utilities and can meet the Rs 1.5 lakh waiver threshold; pick the Platinum Chip card ⓘ for a no-fee, simple rewards experience, especially if your spend is modest or you want a fee-free starter card.
Side by Side
| Detail | ICICI HPCL Super Saver Credit Card ⓘ | ICICI Bank Platinum Chip Credit Card ⓘ |
|---|---|---|
| Annual fee | Rs 500 | Nil (lifetime free) |
| Joining fee | Rs 500 | Nil (lifetime free) |
| Fee waiver on spend | Rs 1.50 lakh | None |
| Reward rate | 1% base, 5% fuel/utilities/grocery | 0.5% base, 0.5% utilities |
| Reward type | points | points |
| Domestic lounge | 4 per year (Rs 75,000 quarterly spend gate) | None |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | fuel, grocery, cashback, shopping, lounge | lifetime-free, first-card, dining, shopping |
Rewards Compared
The ICICI HPCL Super Saver Credit Card ⓘ delivers Rs 100 back per Rs 10,000 spent at the base rate of 1%. Its standout feature is the 5% return on fuel, utilities, and grocery spends, translating to Rs 500 back on Rs 10,000 in these categories, significantly boosting rewards for daily essentials and fuel. This makes it highly attractive for users with substantial expenditure in these segments.
In contrast, the ICICI Bank Platinum Chip Credit Card ⓘ offers a straightforward 0.5% reward rate across the board, yielding Rs 50 for Rs 10,000 spent, with utilities also at 0.5%. It lacks category-specific bonus rates, providing modest rewards suitable for low to moderate spenders who prioritize no annual fees over high returns.
Fees Compared
The ICICI HPCL Super Saver Credit Card ⓘ charges a joining fee and annual fee of Rs 500 each, totaling Rs 1,000 in the first year. However, this fee is waived if you spend Rs 1.5 lakh annually, which equates to about Rs 12,500 monthly. The card requires Rs 50,000 in spend annually just to cover the annual fee via base rewards, making it beneficial only if you regularly spend above this level, especially in bonus categories.
The ICICI Bank Platinum Chip Credit Card ⓘ has no joining or annual fees, making it cost-free to hold at any spend level. However, the effective reward rate is half that of the Super Saver card ⓘ, meaning you forgo some rewards in exchange for zero fees. The break-even point comparing these two cards' rewards and fees is roughly Rs 1,00,000 annual spend; above this, Super Saver ⓘ becomes more rewarding despite fees.
Which One Should You Pick
Choose the ICICI HPCL Super Saver Credit Card ⓘ if you spend heavily on fuel, groceries, or utilities and can comfortably meet the Rs 1.5 lakh annual spend to waive fees. It suits shoppers looking for higher returns plus domestic lounge access and welcome bonuses. Avoid it if your spend is light or irregular, as fees and forex markup may erode value.
Opt for the ICICI Bank Platinum Chip Credit Card ⓘ if you want a completely fee-free credit card with modest rewards. It fits first-time credit card users, those who prefer simplicity, or consumers with low to moderate monthly spends. Skip it if you seek higher category rewards or lounge access, as it offers none.
Ultimately, the Super Saver ⓘ is best for category-focused high spenders valuing lounges, while the Platinum Chip ⓘ is ideal for fee-conscious users wanting a no-fuss card.
What to Check Before You Apply
- Confirm the Rs 1.5 lakh annual spend threshold for fee waiver on the Super Saver ⓘ as missing it means paying Rs 500 annual fee.
- Check the redemption value and point expiry policies for both cards to ensure rewards can be effectively utilized.
- Be aware that the Super Saver ⓘ imposes a Rs 75,000 quarterly spend gate to access four domestic lounges annually.
- Both cards apply a 3.5% forex markup on foreign currency spend, which can add significant costs abroad.

Comments
No comments yet
Be the first to share your experience with this card.