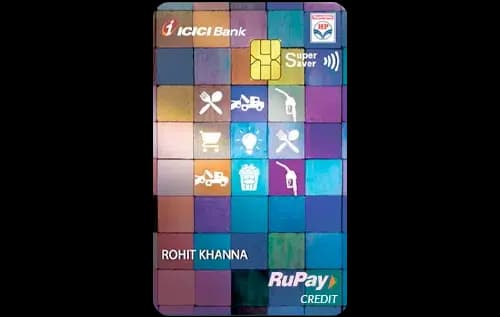
Quick Verdict
- For everyday spending on groceries, fuel, and utilities, the ICICI HPCL Super Saver Credit Cardⓘ wins with a 5% reward rate in these categories.
- For travel and lounge benefits, the Makemytrip ICICI Bank Signature Credit Cardⓘ is superior, offering higher travel rewards and more domestic and international lounge visits.
- The ICICI HPCL Super Saver Credit Card is cheaper to hold with a lower joining and annual fee, and easier fee waiver threshold.
- Choose the ICICI HPCL Super Saver for regular spends in fuel and groceries, and pick the Makemytrip ICICI Bank Signature for travel-focused benefits and lounge access.
Side by Side
| Detail | ICICI HPCL Super Saver Credit Cardⓘ | Makemytrip ICICI Bank Signature Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 500 | Rs 999 |
| Joining fee | Rs 500 | Rs 999 |
| Fee waiver on spend | Rs 1.50 lakh | None |
| Reward rate | 1% base, 5% fuel, utilities, grocery | 1.25% base, 6% travel, 2.5% dining |
| Reward type | points | points |
| Domestic lounge | 4 per year | 8 per year |
| International lounge | None | 4 per year |
| Forex markup | 3.5% | 3.5% |
| Best suited for | fuel, grocery, cashback, shopping, lounge | travel, lounge, rewards |
Rewards Compared
Spending Rs 10,000 on the ICICI HPCL Super Saver Credit Cardⓘ earns Rs 100 back at the base rate. However, in key categories like fuel, utilities, and grocery, it returns Rs 500 per Rs 10,000 spent, reflecting a generous 5% reward rate. This makes it highly attractive for users who spend heavily in these everyday categories. The welcome benefits also add value with bonus points and cashback on fuel.
In contrast, the Makemytrip ICICI Bank Signature Credit Cardⓘ offers a better base reward rate of 1.25%, equivalent to Rs 125 on Rs 10,000 spent overall. Its category rewards shine in travel with 6% returns (Rs 600 per Rs 10,000) and decent 2.5% returns on dining (Rs 250 per Rs 10,000). This card is clearly designed for frequent travelers and those who dine out often, providing enhanced value in those categories.
Fees Compared
The ICICI HPCL Super Saver Credit Card charges Rs 500 for both joining and annual fees. These fees are fully waived if you spend Rs 1.50 lakh annually, which breaks down to Rs 12,500 per month. This makes it easier to avoid fees for moderate spenders. The break-even spend to cover the base reward rate fee is Rs 50,000.
The Makemytrip ICICI Bank Signature Credit Card has higher fees at Rs 999 each for joining and annual fees, with no fee waiver mentioned. The card requires Rs 79,920 in spend just to cover its base reward rate fee through earned rewards. To justify the higher fees compared to the Super Saver card, you would need to spend about Rs 1,99,600 more annually to make the higher reward rates worthwhile.
Which One Should You Pick
Choose the ICICI HPCL Super Saver Credit Cardⓘ if you spend significantly on fuel, groceries, and utilities and want a low-fee card with decent rewards. It is ideal for budget-conscious users who want to maximize returns on everyday expenses and prefer simpler fee waiver conditions. Skip this card if you travel frequently and want premium lounge access.
The Makemytrip ICICI Bank Signature Credit Cardⓘ is tailored for frequent travelers who value enhanced travel and dining rewards, plus generous lounge access both domestically and internationally. It suits higher spenders who do not mind paying a premium for these perks. Avoid this card if you are a low or moderate spender or if you rarely travel, as the fees and lack of waiver make it expensive.
The final call: for everyday spenders focused on fuel and groceries, the ICICI HPCL Super Saver is the better value. For travel enthusiasts wanting lounge benefits and travel rewards, the Makemytrip ICICI Bank Signature card is the superior choice, despite its higher cost.
What to Check Before You Apply
- Verify if the reward category caps or limits affect your earning potential, especially for fuel and travel spends.
- Understand the actual redemption value of points, as the effective return depends on how you use them.
- Calculate if you can comfortably meet the annual spend for fee waiver on the Super Saver card, or if the Signature card’s fee is worth paying without waiver.
- Note the 3.5% forex markup on both cards, which is standard but costly for foreign currency transactions.
- Confirm the lounge access gates and partner airports to ensure convenient lounge usage.

Comments
No comments yet
Be the first to share your experience with this card.