Quick Verdict
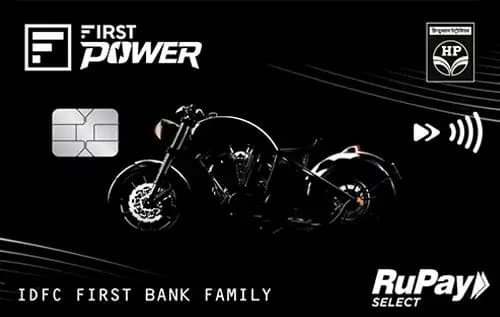
- The IDFC HPCL First Power Credit Cardⓘ wins for everyday spends with a higher base reward rate and strong category bonuses on fuel, grocery, and utilities.
- The HDFC Bank Rupay IRCTC Credit Cardⓘ is preferable for travel spenders due to its 5% travel reward and domestic lounge access.
- The HDFC Rupay IRCTC card is cheaper to hold overall, with no annual fee, compared to Rs 199 annual fee on the IDFC card.
- Pick IDFC First Power if you want superior rewards on essential spends and can meet the Rs 50,000 annual waiver. Choose HDFC Rupay IRCTC if you want lounge access and fee-free lifetime holding.
Side by Side
| Detail | IDFC HPCL First Power Credit Cardⓘ | HDFC Bank Rupay IRCTC Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 199 | Nil (lifetime free) |
| Joining fee | Rs 199 | Rs 500 |
| Fee waiver on spend | Rs 50,000 | Rs 1.50 lakh |
| Reward rate | 0.75% base | 0.5% base |
| Reward type | points | points |
| Domestic lounge | None | 8 per year |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | fuel, upi-rupay, first-card | travel, upi-rupay, first-card |
Rewards Compared
The IDFC HPCL First Power Credit Cardⓘ offers a base reward of Rs 75 on Rs 10,000 spent, which is 0.75%. More impressively, it boosts returns to Rs 500 on Rs 10,000 in key categories such as fuel, grocery, and utilities, all at 5%. This makes it highly rewarding for everyday essential expenses, especially fuel. The card also provides a Rs 250 gift voucher on the first HPCL fuel transaction and up to 5% cashback on the first EMI transaction, enhancing its value for first-time users.
In contrast, the HDFC Bank Rupay IRCTC Credit Cardⓘ yields Rs 50 on Rs 10,000 spent at a 0.5% base rate, which is lower than the IDFC card. However, it shines for travel spending with a 5% reward rate, translating to Rs 500 back on Rs 10,000 spent in travel categories. It also offers 1% back (Rs 100 per Rs 10,000) on UPI transactions. This card is tailored more for those with travel-focused expenses rather than general everyday spending.
Fees Compared
The IDFC HPCL First Power Credit Cardⓘ has a joining and annual fee of Rs 199 each, but the annual fee is waived if you spend Rs 50,000 annually, which breaks down to approximately Rs 4,167 per month. You would need to spend Rs 26,533 at the base rate to cover the annual fee purely from rewards.
Meanwhile, the HDFC Bank Rupay IRCTC Credit Cardⓘ has a higher joining fee of Rs 500 but no annual fee at all, making it lifetime free to hold. Its fee waiver on spend is Rs 1.50 lakh annually, but since the annual fee is nil, this is mostly relevant for lounge access qualification. Lounge access requires Rs 75,000 quarterly spend to avail of 8 domestic lounges annually.
The IDFC card’s higher base reward rate justifies the Rs 199 annual fee for moderate spenders, whereas the HDFC card's cost structure suits those wanting a fee-free card with travel benefits.
Which One Should You Pick
Choose the IDFC HPCL First Power Credit Cardⓘ if your spending focus is on fuel, groceries, and utilities, and you want to maximize rewards on these everyday categories. It is also suitable if you are a first-time credit card user looking for easy fee waiver at Rs 50,000 annual spend and a modest joining fee.
Opt for the HDFC Bank Rupay IRCTC Credit Cardⓘ if you prioritize travel rewards and value domestic lounge access. This card is perfect for frequent travelers who can meet the Rs 75,000 quarterly spend for lounges and want a truly fee-free lifetime card after the joining fee. Its UPI rewards also add incremental value for digital payments.
In summary, skip the IDFC card if you rarely spend on fuel or grocery or cannot meet the Rs 50,000 waiver threshold. Conversely, skip the HDFC Rupay IRCTC card if you do not travel often or want higher base rewards on everyday spends, as its base rate is lower and no international lounges are offered.
What to Check Before You Apply
- Verify if the 5% category rewards on the IDFC card have a monthly or annual cap.
- Confirm the redemption value of points for each card to ensure you get full value.
- Understand the exact monthly spend required to waive fees and how easy it is for you to meet them.
- Check that both cards charge a 3.5% forex markup on international spends, which is standard but costly.

Comments
No comments yet
Be the first to share your experience with this card.