Quick Verdict
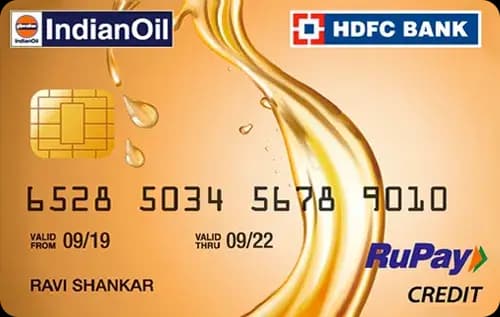
- For everyday spends on fuel and groceries, the Indianoil HDFC Bank Credit Cardⓘ wins with a higher 5% reward rate in these categories.
- The IndusInd Bank Tiger Credit Cardⓘ takes the lead for travel and lounge benefits thanks to four free domestic lounge visits per year and no annual or joining fees.
- In terms of cost to hold, the IndusInd Tiger is cheaper with no joining or annual fees, whereas the Indianoil HDFC card charges Rs 500 each, waivable only on Rs 50,000 annual spend.
- Choose the Indianoil HDFC cardⓘ if your spending is heavy on fuel and groceries and you can meet the fee waiver. Opt for the IndusInd Tigerⓘ if you want a truly fee-free card with lounge access and moderate rewards on online and UPI spends.
Side by Side
| Detail | Indianoil HDFC Bank Credit Card ⓘ | IndusInd Bank Tiger Credit Card ⓘ |
|---|---|---|
| Annual fee | Rs 500 | Nil (lifetime free) |
| Joining fee | Rs 500 | Nil (lifetime free) |
| Fee waiver on spend | Rs 50,000 | None |
| Reward rate | 1% base, 5% fuel & grocery | 1% base, 2.5% online, 1% UPI |
| Reward type | points | points |
| Domestic lounge | None | 4 per year |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | fuel, first-card, UPI-Rupay | lifetime-free, UPI-Rupay, rewards, lounge, travel |
Rewards Compared
The Indianoil HDFC Bank Credit Cardⓘ delivers Rs 100 back on Rs 10,000 spent as a base reward rate, but it shines with 5% returns on fuel and grocery spends, yielding Rs 500 on Rs 10,000 in these categories. This makes it an excellent choice for customers who spend heavily on fuel or groceries and want higher rewards in these segments.
The IndusInd Bank Tiger Credit Cardⓘ offers a 1% base reward rate equivalent to Rs 100 on Rs 10,000 spent, similar to the Indianoil HDFC card base rate. However, it boosts rewards on online spends to 2.5%, or Rs 250 per Rs 10,000, and on UPI spends to 1%, matching the base rate. This card is better suited for those who spend more online or via UPI and value fee-free usage and lounge access over category-specific fuel rewards.
Fees Compared
The Indianoil HDFC Bank Credit Cardⓘ charges a joining fee of Rs 500 and an annual fee of Rs 500. These fees are waived if you spend Rs 50,000 annually, which breaks down to about Rs 4,167 per month. If your spend is below this threshold, you effectively pay Rs 1,000 in fees yearly, which means your base reward of 1% needs to cover this cost by spending at least Rs 50,000 annually.
In contrast, the IndusInd Bank Tiger Credit Cardⓘ has no joining or annual fees, making it a lifetime free card. This is a significant advantage for users who want to avoid fees altogether. The Tiger card requires a quarterly spend of Rs 40,000 to access each domestic lounge visit, so there is a spend gate for lounge entry but no fee waiver threshold.
Which One Should You Pick
Choose the Indianoil HDFC Bank Credit Cardⓘ if you frequently spend on fuel or groceries and can meet the Rs 50,000 annual spend to waive fees. Its higher 5% returns in these categories compensate for the fees and make it a strong fuel-linked rewards card. It is also a good option for first-time credit card users looking for a simple rewards structure.
Opt for the IndusInd Bank Tiger Credit Cardⓘ if you prefer a no-fee card with moderate rewards across online and UPI spends and value lounge access without additional charges. It suits those who want to avoid fees completely and enjoy some travel perks like domestic lounges and golf access.
In conclusion, fuel-heavy spenders who can meet the fee waiver should pick the Indianoil HDFC cardⓘ. If you want a hassle-free, fee-free card with lounge privileges and decent online rewards, the IndusInd Tigerⓘ is the better pick. Those not spending much on fuel or groceries should skip the Indianoil HDFC cardⓘ due to fees. Likewise, if you do not need lounges or travel perks, the IndusInd Tigerⓘ may be overkill.
What to Check Before You Apply
- Confirm if your monthly or annual spend meets the fee waiver criteria for the Indianoil HDFC Bank Credit Cardⓘ.
- Check caps or limits on fuel and grocery rewards to ensure you can maximize the 5% rate.
- Understand that both cards charge a 3.5% forex markup on international spends, which can be costly for frequent travelers.
- Verify the number of lounges allowed and the spend gates for domestic lounge access on the IndusInd Tiger Credit Cardⓘ, especially if you plan to use this benefit often.

Comments
No comments yet
Be the first to share your experience with this card.