Quick Verdict
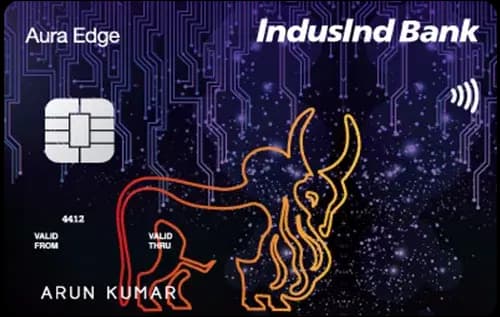
- For everyday spend, the IndusInd Platinum AUra Edge Credit Card ⓘ wins with a higher base reward rate and strong category returns.
- For dining and grocery categories specifically, the SBI Simplysave Credit Card ⓘ offers better category rewards.
- The IndusInd card is cheaper to hold with no joining or annual fees, while the SBI card has fees but offers a waiver on spending Rs 1,00,000 annually.
- Choose the IndusInd Platinum AUra Edge if you want a no-fee, straightforward rewards card for general shopping. Pick the SBI Simplysave if you spend heavily on dining and groceries and can meet the fee waiver threshold.
Side by Side
| Detail | IndusInd Platinum AUra Edge Credit Card ⓘ | SBI Simplysave Credit Card ⓘ |
|---|---|---|
| Annual fee | Nil (lifetime free) | Rs 499 |
| Joining fee | Nil (lifetime free) | Rs 499 |
| Fee waiver on spend | Rs 1,00,000 | |
| Reward rate | 0.7% base, 2.1% dining, grocery, online | 0.25% base, 2.5% dining, grocery |
| Reward type | Points | Points |
| Domestic lounge | None | None |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | Lifetime-free, rewards, first-card, shopping | First-card, dining, grocery, rewards, shopping |
Rewards Compared
The IndusInd Platinum AUra Edge Credit Card ⓘ offers a base reward of Rs 70 on Rs 10,000 spent, which is substantially higher than the Rs 25 earned on the same spend with the SBI Simplysave Credit Card ⓘ. This makes the IndusInd card more rewarding for general, non-category spend. When focusing on categories, the IndusInd card delivers 2.1% returns or Rs 210 on Rs 10,000 spent in dining, grocery, and online shopping, while the SBI Simplysave slightly edges it out with 2.5% returns or Rs 250 in dining and grocery. The SBI card does not list online shopping as a category bonus, so the IndusInd card is better there.
Overall, the IndusInd Platinum AUra Edge is better for general and online spends, while the SBI Simplysave is more rewarding for heavy dining and grocery expenses. Both cards use points as rewards but the effective rupee returns are clearly quantified, making it easy to compare.
Fees Compared
The IndusInd Platinum AUra Edge Credit Card ⓘ has no joining or annual fees, making it a truly lifetime free option. The SBI Simplysave Credit Card ⓘ charges Rs 499 for both joining and annual fees. However, the SBI card offers a fee waiver if you spend Rs 1,00,000 annually, which breaks down to about Rs 8,333 per month. This means if you can consistently spend this amount, you avoid the fee cost.
The break-even spend for the SBI Simplysave card to cover its annual fee through base rewards alone is approximately Rs 1,99,600 or about Rs 2,00,000 annually. This is nearly double the waiver threshold, so the fee waiver is the more practical way to avoid fees. Otherwise, the IndusInd card is cheaper to hold for low to moderate spenders.
Which One Should You Pick
Choose the IndusInd Platinum AUra Edge Credit Card ⓘ if you want a no-fee card that rewards everyday shopping, groceries, dining, and online purchases with solid returns. It is ideal for first-time cardholders or those who prefer simplicity without worrying about fees. It suits users who do not spend very heavily but want decent rewards.
Opt for the SBI Simplysave Credit Card ⓘ if you spend significantly on dining and groceries and can meet the Rs 1,00,000 annual spend to waive fees. The higher category rewards on dining and grocery make it attractive for food lovers and household shoppers who want to maximise returns in these categories. It is also suitable for those who value the welcome benefit of 2,000 reward points for early spending.
Overall, if you want to avoid fees entirely and get better base rewards, pick the IndusInd Platinum AUra Edge. If your spending aligns with the SBI Simplysave’s categories and waiver threshold, it can deliver more value despite fees. Skip the IndusInd card if you want higher category rewards in dining and grocery and can spend heavily. Skip the SBI Simplysave if you want a no-fee card or do not meet the waiver spend.
What to Check Before You Apply
- Confirm if category rewards have any monthly or annual caps that limit your earnings.
- Check the redemption value and ease of redeeming points to ensure rewards convert well.
- Understand the fee waiver maths carefully to avoid unexpected charges.
- Consider the 3.5% forex markup if you plan to use the card abroad frequently.
- Verify if there are any restrictions on lounge access or if none are offered, as is the case here.

Comments
No comments yet
Be the first to share your experience with this card.