Paying for EV Charging: Prepaid Wallets, UPI, and Cards at the Charger
Published: 18 October 2026 Category: how-to-guides | cardbuzz
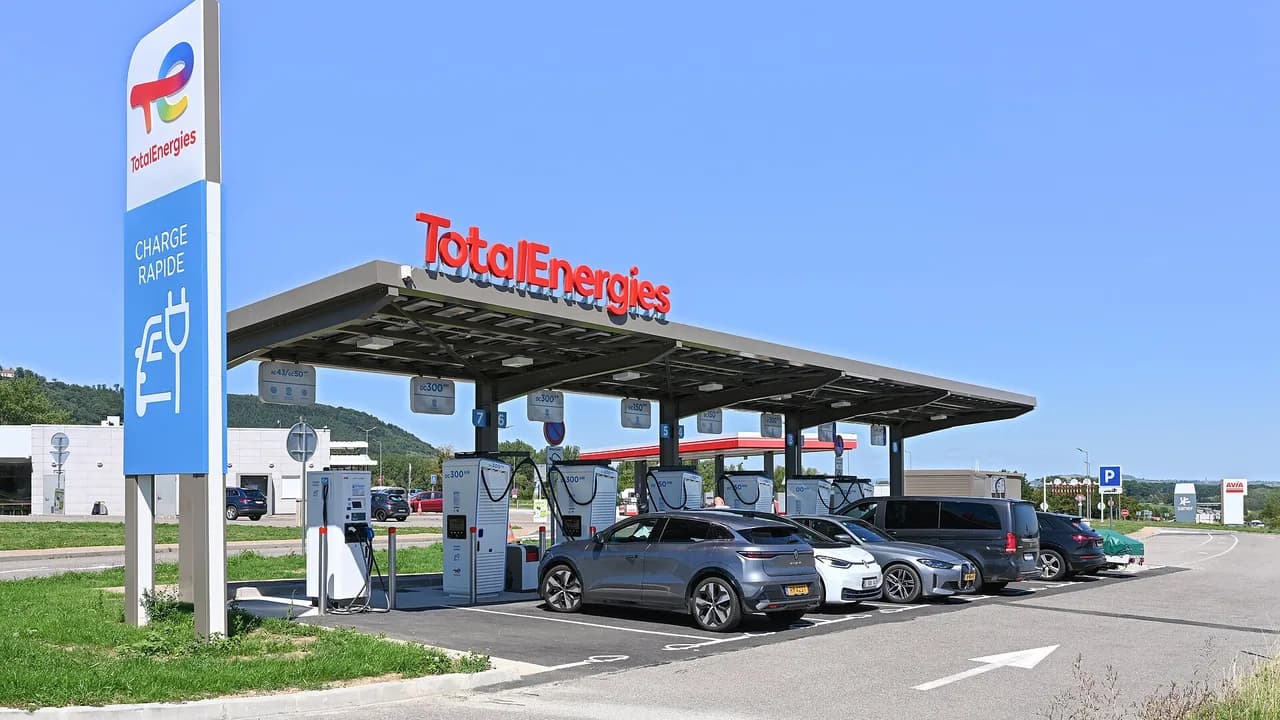
Paying to charge an EV in India is a messier transaction than paying for petrol. There is no single "pump terminal" — you pay inside the charging network's app, and that app takes your money through whatever route you choose: a prepaid wallet inside the app, UPI, or a saved card. Each route codes differently, and the rewards outcome ranges from "normal earn" to "explicitly excluded." This guide maps the payment routes at Indian charging networks and the card mechanics of each.
How charging payments actually flow
The major public networks — Tata Power EZ Charge, Jio-bp pulse, Statiq, ChargeZone, and others — are app-first. The typical flow:
- You locate a charger in the network's app and start the session from the app.
- The app requires a prepaid balance (a wallet inside the app) or deducts per session via your chosen method.
- Billing is per kWh of electricity delivered, plus 18% GST.
The critical point: the card transaction your bank sees is often a wallet load, not a charging payment. You top up the Statiq wallet or the Tata Power wallet with your card; the app then deducts charging costs from the wallet balance. The issuer sees MCC 6540 (or the gateway's MCC) — a wallet load — not an EV charging transaction.
Why the wallet step matters
Many Indian issuers explicitly exclude wallet loads from reward earn. HDFC Bank's MITC, for example, is explicit that wallet loads don't earn rewards on several cards, and similar exclusions exist across issuers. So the chain breaks at the first step:
| Payment route | What the issuer sees | Typical reward outcome |
|---|---|---|
| Card → in-app wallet top-up → charging deducted | Wallet load (MCC 6540 class) | Often excluded from rewards |
| Card saved in app, charged per session (no wallet) | Services/utility MCC via gateway | Usually earns base rewards |
| UPI payment in the app | No card transaction | No card rewards by definition |
| Credit card on UPI (RuPay) at a UPI-accepting charger | UPI transaction | Earns per the card's UPI terms, if any |
The difference between rows 1 and 2 is invisible in the app's UI but decisive for rewards. If your network's app forces a wallet, the rewards question is settled by the wallet-load exclusion, not by any EV or fuel rule.
The tariff reality: what you're actually paying
Public DC fast charging in India typically runs ₹18–₹25 per kWh before GST, with 18% GST on top — so an advertised ₹20/kWh bills at about ₹23.60. Network ranges observed in the market:
| Network / mode | Indicative ₹/kWh (pre-GST) | Notes |
|---|---|---|
| Jio-bp pulse | ~₹16–₹22 | Among the lowest headline rates; plan pricing varies |
| Tata Power EZ Charge | ~₹17 | Consistently competitive among large networks |
| Statiq | ~₹22 | Subscription passes can discount ~10% |
| ChargeZone (DC) | ~₹18–₹25 | Corridor pricing varies by location |
| Public AC (typical) | ~₹8–₹15 | Slower, cheaper |
| Home (domestic tariff) | ~₹6–₹10 | Cheapest by far; state/slab dependent |
At 15 kWh per 100 km (a reasonable planning figure for a mid-size EV), public DC costs roughly ₹2.70–₹3.75 per 100 km per kWh... more precisely: 15 kWh × ₹23.60 ≈ ₹354 per 100 km, or about ₹3.50/km. Home charging at ₹8/kWh is about ₹1.20/km. The payment method changes none of this — but the reward earn on the payment is a small offset worth capturing correctly.
The rewards math on charging
Charging is a utility-like spend. On a card earning 1% base rewards (₹1 per ₹100 in point value), a ₹1,000 monthly public-charging bill earns about ₹10 in value — ₹120 a year. Nobody should choose a card for its EV-charging earn. The right optimisation is:
- Avoid the wallet-load trap where possible — prefer per-session card billing so the transaction codes as a service/utility and earns base rewards.
- Don't pay a convenience fee to earn rewards. Some apps add a gateway fee for card payments but not for UPI. A 1% card fee wipes out a 1% reward earn exactly; with GST on the fee, you're net negative.
- Consider the charging network's own subscription. A 10% discount pass (like Statiq's monthly pass structure) beats any card reward by an order of magnitude for regular public-charging users.
UPI vs card at the charger
Most charging apps accept UPI, and for small top-ups UPI is usually the rational choice: no card surcharge, no wallet-load exclusion question, instant settlement. The card wins only when (a) the transaction codes as a normal service purchase earning base rewards, (b) no extra gateway fee applies, and (c) you want the spend on the card for utilisation/history reasons. For large monthly charging bills, the card's interest-free period has real cash-flow value even at modest reward rates.
RuPay credit cards on UPI add a wrinkle: if the charger's QR or the app's UPI flow accepts credit-card-backed UPI, the transaction may earn per the card's UPI earn terms. Check whether your card earns on UPI transactions at all — many don't, or earn at reduced rates.
Pitfalls
Pitfall 1: Topping up the wallet with a card that excludes wallet loads. This is the single most common rewards failure in EV charging. The exclusion is in the card's MITC under "wallet" — search for it before assuming.
Pitfall 2: Auto-recharge mandates on the wallet. In-app wallets often default to auto-top-up. An auto-debit you forgot about is still a wallet load for rewards purposes, and it complicates spend tracking.
Pitfall 3: Paying GST twice in your mental math. The app's per-kWh display may or may not include GST. Confirm whether the billed rate is inclusive before comparing networks — an ₹18/kWh exclusive rate and a ₹20/kWh inclusive rate are nearly identical.
Pitfall 4: Chasing card rewards instead of the cheaper network. A ₹2/kWh tariff difference on 200 kWh a month is ₹400 — more than any card reward on the same spend. Network choice dominates payment-method choice.
Pitfall 5: Idle fees. Some networks bill idle fees after charging completes. These code as service charges; they're also entirely avoidable by moving the car promptly.
Comments
No comments yet
Be the first to share your experience with this card.