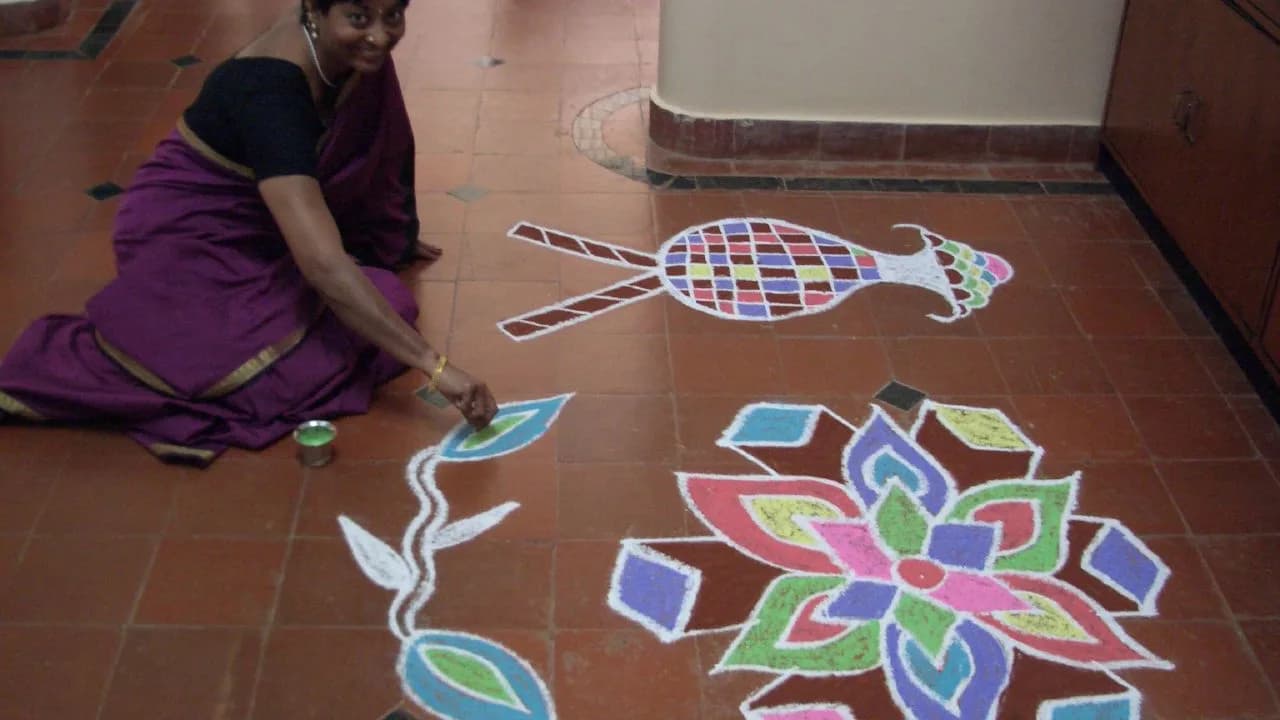
Pongal Travel and Shopping: A Credit-Card Guide to the Harvest Festival
Published: 18 October 2026 Category: buying-guides | cardbuzz
Pongal, the four-day Tamil harvest festival that falls in mid-January, drives one of the most concentrated bursts of regional spending in South India: train and flight bookings home, new clothes for the whole family, brass and steel vessels for the kitchen, sugarcane and jaggery for the pongal pot, and gifts for domestic help and relatives. Because the spending hits across travel, groceries, apparel and home goods within a single week, it rewards a deliberate credit-card plan rather than a single favourite card.
Book travel home before the holiday rush sets in
The Pongal week sees some of the heaviest homeward traffic of the year on routes into Tamil Nadu — Chennai, Coimbatore, Madurai, Trichy, Salem and Tirunelveli fill fast. Two booking mechanics matter here.
Trains: Indian Railways' advance booking window currently runs about 60 days before travel, so January Pongal bookings open in mid-November. When booking through IRCTC, a convenience fee applies per ticket (not per passenger): ₹15 plus GST for non-AC classes and ₹30 plus GST for AC classes, dropping to ₹10 plus GST and ₹20 plus GST respectively when paying through BHIM/UPI. The fee is non-refundable even if the ticket is cancelled. A few card issuers run railway-booking cashback or accelerated rewards on IRCTC, so check whether the card used at checkout earns its headline rate on railway spend — some cards treat it as a utility category and pay a lower rate.
Flights: Chennai, Coimbatore and Madurai see sharp fare spikes in the final ten days before Pongal as demand concentrates. Booking early is the single biggest lever; the second is fare flexibility — shifting departure by even one day can change the price materially on holiday weeks. Airline co-brand cards earn their strongest rewards when the fare is bought directly from the airline rather than an aggregator, while general travel cards often pay bonus rewards on flight bookings through their own travel portals. Compare the final cash fare (after card-portal discounts or instant discounts) against the portal price before assuming the portal is cheaper.
The Pongal shopping basket: clothes, vessels and the festival kitchen
Pongal shopping traditionally includes new clothes for family members, new vessels (the pongal pot itself is often bought fresh each year), sugarcane stalks, jaggery, rice, moong dal, ghee, cashews and decorative items like turmeric plants and mango leaves. Card strategy by basket segment:
- Apparel and footwear: Festive-season bank offers on major marketplaces usually include instant discounts on minimum cart values with specific cards, plus no-cost EMI on larger baskets. Stack in this order: platform coupon, card instant discount, then rewards on the final charged amount. Note that when a purchase is converted to EMI, most cards reduce or remove reward earnings on that transaction, so EMI works best when the cash-flow benefit clearly exceeds the lost rewards.
- Kitchen vessels and home goods: These are classic EMI candidates when buying brass or steel sets in bulk. No-cost EMI is not truly free: issuers commonly charge a processing or conversion fee in the range of ₹99 to ₹299 plus 18% GST (fees can run higher on some cards), and the full purchase amount is blocked against the credit limit until instalments clear. For a vessel set that could be paid outright, the fee plus lost rewards often costs more than the instalment convenience is worth.
- Festival groceries: Sugarcane, jaggery, rice, ghee and dry fruits bought in bulk count as grocery spend, which earns standard rates on most cards and accelerated rates on a few grocery-focused ones. Instant-delivery apps and local supermarkets both accept cards; the instant-delivery convenience fee is small but adds up across many small orders, so consolidating the festival grocery run into one or two orders keeps fees down.
Gifting mechanics: relatives, domestic help and farm workers
Pongal involves gifting across a wide circle — new clothes for parents and elders, cash or gifts for domestic help, and sometimes bonuses for farm or factory workers. Three card-relevant points:
- Buying gift cards or vouchers for gifting is frequently excluded from reward earnings on many Indian credit cards, or capped at low monthly limits. If the plan is to gift store vouchers, check the card's exclusions first; buying the actual gift on the card usually earns more.
- Cash gifts cannot go on a credit card without cash-advance fees and immediate interest, so budget cash gifts from the bank account and keep the card for merchant purchases.
- Domestic and farm help often appreciate practical festival goods — clothes, provisions, utensils — bought in bulk, which also consolidates into fewer, larger card transactions that clear reward thresholds more efficiently.
The Mattu Pongal and Kaanum Pongal outing spends
The third and fourth days of Pongal are outing days: temple visits, cattle fairs, Jallikattu events in some districts, and family picnics or cinema. These generate dining, fuel and entertainment spends. Fuel surcharge waivers on many cards apply at petrol pumps (typically with a minimum and maximum waiver per statement cycle — check the card's published terms), dining cards earn accelerated rewards at restaurants, and movie-ticket offers on entertainment cards or wallet-linked cards can take the edge off family cinema outings. For temple-town trips, parking and toll spends on the card keep everything in one statement for easy review.
Using EMI without wrecking the January statement
Pongal lands right after the December holiday season, when many cardholders are already carrying balances. Stacking fresh Pongal EMIs on top of existing December EMIs pushes utilisation up on two fronts: the new EMI blocks the full amount against the limit, and existing balances are still being paid down. Credit utilisation above 30% on a card starts to weigh on credit scores, and multiple concurrent EMIs reduce the available limit for genuine emergencies. The practical rule: total monthly EMI outgo should stay comfortably below what the household can clear, and at least one card should be kept with enough headroom for the month's essential spending.
Post-Pongal: settle, reconcile and reset
Within a week after the festival, download the statements for every card used and reconcile: confirm instant discounts actually posted, check that convenience fees and processing fees match what was shown at checkout, and verify that EMI conversions reflect the promised tenure and first instalment date. Pay each card in full if possible — interest on carried balances (typically around 3%+ per month on many Indian cards, charged from the transaction date) dwarfs any rewards earned during the festival. Finally, note which categories drove the most spend; that data is the input for choosing which card to lead with at the next festival.
A Pongal-week card calendar
Putting the pieces together, a practical sequence for the festival week looks like this:
- Six to eight weeks before: Book trains (advance window) or flights home; lock in the lowest fares. Put the booking on the card with the best travel-earn rate and confirm the convenience fee line on IRCTC.
- Two to three weeks before: Do the apparel and vessel shopping during marketplace offer windows so instant discounts apply; pay in full on the best-earning card for each category.
- Festival week: Groceries and perishables on the grocery-optimised card; outings and dining on dining/entertainment cards; fuel with the surcharge-waiver card.
- Week after: Reconcile every statement, confirm discounts and EMI terms, and pay in full.
Households that run this calendar twice — once mentally, once on the statements — turn Pongal from the year's most chaotic spending week into its most rewarding one.
Timing purchases around January sales
Pongal coincides with January clearance and new-year sales on marketplaces and in retail stores, which creates a genuine overlap: festive shopping can ride the same bank-offer windows as clearance buying. The discipline required is to separate the two lists. Festival essentials — clothes, vessels, groceries — go on the cards with the best category earn rates. Clearance opportunism — the discounted mixer-grinder that was not on any list — deserves a 48-hour pause before buying. January is when retailers clear inventory precisely because shoppers are in a buying mood; the cardholder who buys only the plan still captures every discount the plan qualifies for.
Comments
No comments yet
Be the first to share your experience with this card.