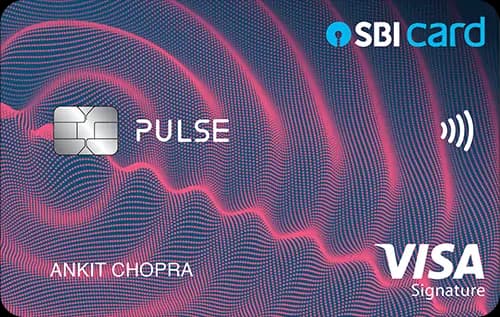
Quick Verdict
- For everyday spending, the Standard Chartered Rewards Credit Card ⓘ wins with a higher base reward rate of 1% versus 0.5% on the SBI Card Pulse Credit Card ⓘ.
- For dining and online categories, Standard Chartered Rewards Credit Card ⓘ also leads with 4% rewards compared to SBI Card Pulse Credit Card ⓘ offering 2.5% on dining and utilities.
- The SBI Card Pulse Credit Card ⓘ is more expensive with a Rs 1,499 annual fee and joining fee, while Standard Chartered Rewards Credit Card ⓘ has no joining fee and a lower annual fee of Rs 1,000.
- Choose SBI Card Pulse Credit Card ⓘ if you want a welcome gift, more domestic lounge visits, and premium benefits like a smartwatch and fitness memberships. Opt for Standard Chartered Rewards Credit Card ⓘ if you want higher rewards on everyday and online spends with a lower fee structure.
Side by Side
| Detail | SBI Card Pulse Credit Card ⓘ | Standard Chartered Rewards Credit Card ⓘ |
|---|---|---|
| Annual fee | Rs 1,499 | Rs 1,000 |
| Joining fee | Rs 1,499 | Nil (lifetime free) |
| Fee waiver on spend | Rs 2.00 lakh | Rs 1.00 lakh |
| Reward rate | 0.5% base | 1% base |
| Reward type | points | points |
| Domestic lounge | 8 per year | 4 per year |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | lounge, dining, rewards, travel, shopping | rewards, dining, first-card, shopping, lounge |
Rewards Compared
The SBI Card Pulse Credit Card ⓘ offers a base reward rate of 0.5%, which means you earn Rs 50 on Rs 10,000 spent. For dining and utilities, the rate increases to 2.5%, translating to Rs 250 back on Rs 10,000 spent in these categories. This card is beneficial if your spending is concentrated in dining and utility bills, where the rewards are significantly higher than the base rate.
On the other hand, the Standard Chartered Rewards Credit Card ⓘ provides a higher base reward rate of 1%, yielding Rs 100 on Rs 10,000 spent. It further enhances rewards on dining and online spends with a 4% rate, giving Rs 400 back on Rs 10,000 in these categories. This card is more rewarding for users who spend heavily on dining and online shopping, offering the best returns among the two for these categories.
Fees Compared
The SBI Card Pulse Credit Card ⓘ charges Rs 1,499 as both joining and annual fees. The fee is waived if you spend Rs 2.00 lakh annually, which breaks down to about Rs 16,667 per month. The break-even spend to cover the annual fee at the base reward rate is approximately Rs 2,99,800, which is quite high.
In contrast, the Standard Chartered Rewards Credit Card ⓘ has no joining fee and a lower annual fee of Rs 1,000. The fee waiver threshold is Rs 1.00 lakh annually or Rs 8,333 monthly, making it easier to avoid fees. The break-even spend to cover the annual fee at the base rate is about Rs 1,00,000, which is much more accessible for average users.
Which One Should You Pick
The SBI Card Pulse Credit Card ⓘ suits users looking for premium benefits like a smartwatch welcome gift, complimentary fitness and health memberships, and more domestic lounge visits. It is ideal for those who prioritize lifestyle perks and can meet the higher fee waiver threshold. However, if you do not spend enough to justify the fees or want better rewards on everyday spends, this card may not be the best choice.
The Standard Chartered Rewards Credit Card ⓘ is a better fit for first-time credit card users or those who want straightforward, higher rewards on dining and online shopping with a lower fee burden. Its lower fee waiver threshold and no joining fee make it more accessible for moderate spenders. However, it offers fewer lounge visits and lacks premium welcome gifts, so it may not appeal to lifestyle-focused users.
Overall, if you want higher rewards and lower fees, pick the Standard Chartered Rewards Credit Card ⓘ. If you want lifestyle benefits and can meet the higher spend requirements, the SBI Card Pulse Credit Card ⓘ is the better choice.
What to Check Before You Apply
- Confirm the exact categories eligible for higher rewards and any caps on those rewards.
- Check the redemption value and process for points to ensure you get good value.
- Understand the fee waiver calculations and ensure your monthly spend meets the threshold.
- Be aware of the 3.5% forex markup on foreign currency spends, which is standard but adds cost.
- Verify the domestic lounge access rules, including any quarterly spend requirements or visit limits.

Comments
No comments yet
Be the first to share your experience with this card.