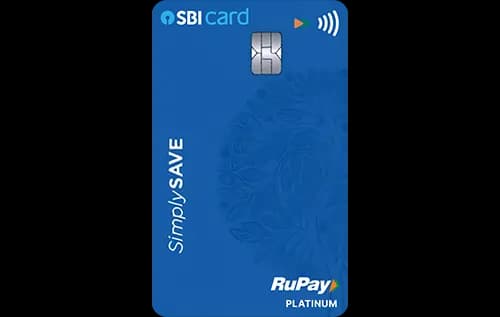
Quick Verdict
- For everyday spend, especially on dining and grocery, the Yes Bank Rupay Credit Cardⓘ offers a higher base reward rate and category returns, making it the better choice.
- The Yes Bank Rupay Credit Cardⓘ also wins for domestic lounge access, offering 4 free visits per year with a quarterly spend requirement, while the SBI Simplysave Credit Cardⓘ offers none.
- The SBI Simplysave Credit Cardⓘ has a joining and annual fee of Rs 499 each, which can be waived on Rs 1,00,000 annual spend, making it more expensive to hold than the lifetime free Yes Bank Rupay Credit Cardⓘ.
- Choose the SBI Simplysave Credit Cardⓘ if you want a simple, no-fuss card with moderate rewards and you can meet the higher waiver spend. Opt for the Yes Bank Rupay Credit Cardⓘ if you want better rewards, free lounge access, and zero fees.
Side by Side
| Detail | SBI Simplysave Credit Cardⓘ | Yes Bank Rupay Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 499 | Nil (lifetime free) |
| Joining fee | Rs 499 | Nil (lifetime free) |
| Fee waiver on spend | Rs 1.00 lakh | Rs 75,000 |
| Reward rate | 0.25% base | 1% base |
| Reward type | points | points |
| Domestic lounge | None | 4 per year (Rs 50,000 quarterly spend gate) |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | first-card, dining, grocery, rewards, shopping | upi-rupay, rewards, grocery, first-card, shopping |
Rewards Compared
On a Rs 10,000 spend, the SBI Simplysave Credit Cardⓘ returns Rs 25 as a base reward, reflecting its 0.25% base reward rate. However, for dining and grocery spends, it offers a significantly better 2.5% return, equating to Rs 250 on Rs 10,000 spent in these categories. This makes it attractive for users with focused spend in these areas, but less rewarding for general spending.
By contrast, the Yes Bank Rupay Credit Cardⓘ delivers a base reward rate of 1%, or Rs 100 on Rs 10,000 spent, which is four times higher than SBI Simplysave’s base rate. Moreover, it offers 3% returns on grocery and dining categories, yielding Rs 300 on Rs 10,000 spent, which is better than the Simplysave card’s category rate. Additionally, it gives 1% back on UPI transactions, making it a versatile card for digital payments.
Fees Compared
The SBI Simplysave Credit Cardⓘ charges a joining fee and an annual fee of Rs 499 each. Both fees can be waived if you spend Rs 1,00,000 annually, which breaks down to about Rs 8,333 per month. The card’s break-even point, where the base reward covers the fee, is approximately Rs 1,99,600 (around Rs 2 lakh) annually, which is quite high given the low base reward rate.
The Yes Bank Rupay Credit Cardⓘ is a lifetime free card with no joining or annual fees. It does have a fee waiver on spend threshold of Rs 75,000 annually (Rs 6,250 monthly), but since there are no fees, this is likely related to lounge access eligibility rather than fee waivers. This makes the Yes Bank Rupay card more affordable to hold, especially for lower spenders.
Which One Should You Pick
If you are a first-time cardholder who primarily spends on dining and groceries and can comfortably spend over Rs 8,333 per month, the SBI Simplysave Credit Cardⓘ can reward you well in these categories. However, you should be prepared to meet the fee waiver threshold to avoid paying Rs 499 annually.
The Yes Bank Rupay Credit Cardⓘ suits those who want a no-fee card with better base rewards and category returns, especially if you use UPI frequently. Its added benefit of 4 domestic lounge visits per year (with Rs 50,000 quarterly spend) is a bonus for occasional travelers or business users. It is ideal for users who prefer a simple, cost-effective card with solid rewards.
Overall, the Yes Bank Rupay Credit Cardⓘ is the better pick for most users due to its higher base reward rate, no fees, and lounge access. The SBI Simplysave Credit Cardⓘ is more niche and only worth considering if you can maximize dining and grocery spends and meet the higher fee waiver threshold.
What to Check Before You Apply
- Confirm if the category spend caps apply to the higher reward rates on dining and grocery.
- Check the exact redemption value and process for reward points, as the cards use points but the effective return varies.
- Understand the monthly spend required to waive fees on the SBI Simplysave Credit Cardⓘ and assess if you can meet it comfortably.
- For foreign travel, note that both cards charge a 3.5% forex markup, which is standard but costly on large forex spends.
- If lounge access matters, verify the Rs 50,000 quarterly spend gate on the Yes Bank Rupay Credit Cardⓘ and the number of allowed visits.

Comments
No comments yet
Be the first to share your experience with this card.