Quick Verdict
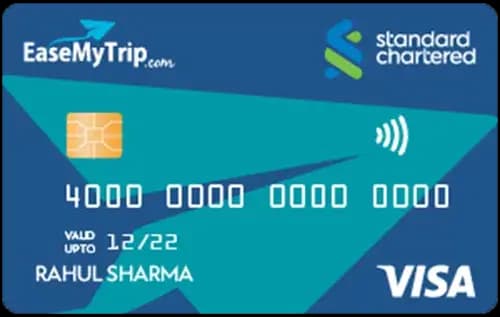
- For everyday spend, both the Standard Chartered Easemytrip Credit Card ⓘ and the Standard Chartered Smart Credit Card ⓘ offer a 1% base cashback, making them equally competitive.
- When it comes to travel and lounges, the Easemytrip card stands out with 4 domestic lounge visits per year and a 10% cashback rate on travel spends.
- The Easemytrip card is cheaper to hold with a lower annual fee of Rs 350 and a fee waiver at Rs 50,000 annual spend, compared to Rs 499 fee and a higher waiver threshold of Rs 1.20 lakh on the Smart card.
- Frequent travellers and lounge users should pick the Easemytrip card, while those looking for online cashback and longer interest-free credit periods may prefer the Smart card.
Side by Side
| Detail | Standard Chartered Easemytrip Credit Card ⓘ | Standard Chartered Smart Credit Card ⓘ |
|---|---|---|
| Annual fee | Rs 350 | Rs 499 |
| Joining fee | Rs 350 | Rs 499 |
| Fee waiver on spend | Rs 50,000 | Rs 1.20 lakh |
| Reward rate | 1% base, 10% on travel | 1% base, 2% on online |
| Reward type | Cashback | Cashback |
| Domestic lounge | 4 per year | None |
| International lounge | None | None |
| Forex markup | 3.5% | 3.5% |
| Best suited for | Travel, first-card, lounge | Cashback, shopping, first-card |
Rewards Compared
Spending Rs 10,000 on the Standard Chartered Easemytrip Credit Card ⓘ yields Rs 100 cashback at the base rate. However, if the spend is on travel, the return significantly increases to Rs 1,000, representing a 10% effective cashback. This makes the Easemytrip card highly rewarding for travel-related expenses such as flights, hotels, and bookings through EaseMyTrip.
On the other hand, the Standard Chartered Smart Credit Card ⓘ also offers Rs 100 cashback on a general Rs 10,000 spend at its 1% base rate. It enhances rewards to Rs 200 for online purchases, effectively doubling the cashback to 2% in this category. This card suits users who spend more on e-commerce, digital subscriptions, or online bill payments but do not gain extra benefits on travel.
Fees Compared
The Easemytrip card charges Rs 350 as both joining and annual fees. These fees are waived if the user spends Rs 50,000 annually, which breaks down to approximately Rs 4,167 per month. The break-even point for the base cashback rate to cover the fee is Rs 35,000 in annual spend.
The Smart card has a higher joining and annual fee of Rs 499 each. Fee waiver is more challenging to achieve with a Rs 1.20 lakh annual spend requirement, or Rs 10,000 monthly. The break-even spend for fee coverage at base rewards is Rs 49,900 annually. Therefore, the Easemytrip card offers a more cost-effective holding experience for moderate spenders.
Which One Should You Pick
If you are a frequent traveller or someone who values domestic lounge access, the Standard Chartered Easemytrip Credit Card ⓘ is the better choice. It offers exceptional value on travel spends and benefits that enhance your travel experience, including lounge visits and EaseMyTrip vouchers on joining. Beginners who want a travel-focused rewards card without heavy fees will find this card appealing.
Conversely, if your spending is predominantly online and you prefer cashback on digital purchases along with an extended interest-free credit period, the Standard Chartered Smart Credit Card ⓘ fits well. It is designed for online shoppers who want a straightforward cashback and a longer grace period on payments. However, this card is less suitable for travellers or lounge seekers due to no lounge access and minimal category rewards beyond online spends.
Final call: Choose the Easemytrip card for travel rewards and lounge perks at a lower cost, and pick the Smart card for online cashback and longer interest-free days. Avoid the Easemytrip card if you do not travel or use lounges, and skip the Smart card if you seek travel benefits or have lower monthly spends below Rs 10,000.
What to Check Before You Apply
- The Easemytrip card’s domestic lounge access requires a quarterly spend of Rs 50,000; verify if your travel frequency meets this.
- Redemption values and vouchers from EaseMyTrip may have restrictions or expiry; read terms carefully.
- Both cards require a substantial annual spend to waive fees; calculate if your spending can cover these thresholds.
- Forex markup is 3.5% on both cards, which is standard but costly for frequent international travellers.
- The Easemytrip card’s lounge access is limited to domestic lounges only; no international lounge privileges.

Comments
No comments yet
Be the first to share your experience with this card.