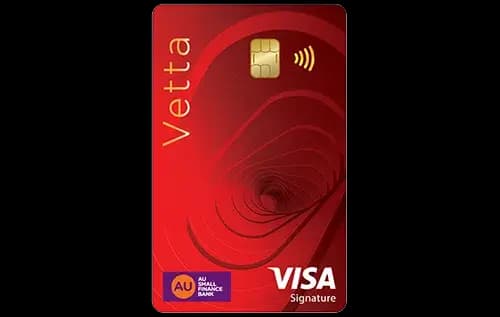
Quick Verdict
- For everyday spend, both the Vetta Credit Cardⓘ and the Axis Bank Select Credit Cardⓘ offer a similar base reward rate of 1%, making them evenly matched for general purchases.
- When it comes to category-specific rewards, Vetta excels on online and dining spends with a 4% return, whereas Axis Bank Select is better suited for grocery shopping with a 4% return, and also offers 2% on online spends.
- In terms of travel and lounge benefits, both cards provide 8 domestic and 4 international lounge visits annually, but Vetta requires quarterly spend gates for domestic lounges, while Axis Bank Select has an annual spend gate.
- The Vetta Credit Card is marginally cheaper to hold if you can spend Rs 5 lakh annually to waive fees, whereas Axis Bank Select demands double that at Rs 10 lakh.
- Pick Vetta if you prioritize dining, online shopping, and premium concierge services. Choose Axis Bank Select if grocery rewards and lower forex markup are your focus.
Side by Side
| Detail | Vetta Credit Cardⓘ | Axis Bank Select Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 2,999 | Rs 3,000 |
| Joining fee | Rs 2,999 | Rs 3,000 |
| Fee waiver on spend | Rs 5.00 lakh | Rs 10.00 lakh |
| Reward rate | 1% base | 1% base |
| Reward type | points | points |
| Domestic lounge | 8 per year | 8 per year |
| International lounge | 4 per year | 4 per year |
| Forex markup | 1.99% | 1.5% |
| Best suited for | premium, rewards, lounge, dining, travel, shopping | rewards, grocery, lounge, travel, shopping |
Rewards Compared
On a straightforward Rs 10,000 spend, both cards yield Rs 100 at the base reward rate of 1%. The Vetta Credit Cardⓘ significantly boosts reward rates to 4% in the online and dining categories, translating to Rs 400 back on Rs 10,000 spent in those segments. This makes it an attractive option for those who spend heavily on food delivery or e-commerce platforms.
By contrast, the Axis Bank Select Credit Cardⓘ shines primarily in grocery shopping, also offering a 4% return or Rs 400 on Rs 10,000 spent in that category. It further provides 2% back on online spends, which is half of Vetta’s category rate but still higher than the base rate. Thus, Axis Bank Select is more tailored for customers whose largest monthly expense is groceries, while Vetta rewards those with diverse premium spends in dining and online shopping.
Fees Compared
Both cards levy an annual fee close to Rs 3,000 with a similar joining fee. The Vetta Credit Cardⓘ requires Rs 5 lakh in annual spend to waive its fees, which breaks down to about Rs 41,667 monthly. On the other hand, the Axis Bank Select Credit Cardⓘ demands a steep Rs 10 lakh annual spend or Rs 83,333 monthly for fee waiver eligibility.
This means the Vetta card is easier to hold without paying fees, ideal for premium users with moderate to high spends. Axis Bank Select suits very high spenders or those who can concentrate spend on grocery and travel categories to maximize waiver benefits. The break-even for covering fees at base rates is very similar at around Rs 3 lakh spend annually.
Which One Should You Pick
Choose the Vetta Credit Cardⓘ if you are a premium spender who values dining and online shopping rewards with the convenience of quarterly lounge access gates. Its concierge services and curated Visa offers add further value for travelers and shoppers who want comprehensive benefits and protection covers.
Go with the Axis Bank Select Credit Cardⓘ if grocery shopping is a significant part of your monthly budget or if you want the lowest forex markup among the two. Golf access and an upfront welcome bonus enhance the appeal for lifestyle-focused customers. However, be prepared for a higher spend requirement to waive fees.
Skip the Vetta card if you do not frequently spend on dining or online categories or if the quarterly lounge spend gate is inconvenient. Avoid Axis Bank Select if you cannot meet the Rs 10 lakh annual spend or if you do not prioritize grocery rewards.
What to Check Before You Apply
- Verify the quarterly and annual spend thresholds carefully to ensure fee waiver eligibility fits your spending pattern.
- Understand how reward points are redeemed and the value you get per point beyond the stated return percentages.
- Confirm whether forex markup applies to all foreign transactions and how it affects your international spend.
- Check which airports the domestic and international lounge accesses cover and if there are any blackout dates or restrictions.

Comments
No comments yet
Be the first to share your experience with this card.