Quick Verdict
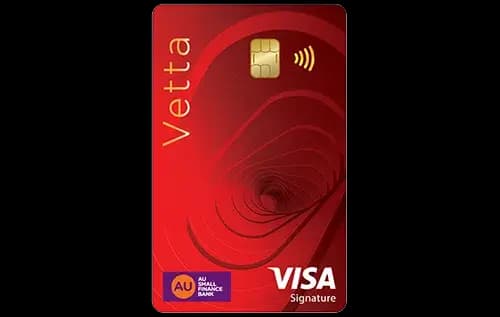
- The Marriott Bonvoy HDFC Bank Credit Cardⓘ wins for everyday spend with a higher base reward rate of 1.3% versus Vetta’s 1%.
- For travel and lounge access, Vetta Credit Cardⓘ offers more comprehensive benefits on domestic lounges and lower forex markup, making it better for frequent travelers.
- Vetta’s annual fee waiver threshold is higher at Rs 5 lakh compared to no waiver on Marriott Bonvoy, but both have similar joining and annual fees around Rs 3,000.
- Pick Vetta for premium dining, online shopping, and superior lounge access with lower forex charges. Choose Marriott Bonvoy for better base rewards and travel perks like golf access and elite hotel status.
Side by Side
| Detail | Vetta Credit Cardⓘ | Marriott Bonvoy HDFC Bank Credit Cardⓘ |
|---|---|---|
| Annual fee | Rs 2,999 | Rs 3,000 |
| Joining fee | Rs 2,999 | Rs 3,000 |
| Fee waiver on spend | Rs 5.00 lakh | |
| Reward rate | 1% base, 4% online & dining | 1.3% base, 2.6% travel & dining |
| Reward type | points | points |
| Domestic lounge | 8 per year | 12 per year |
| International lounge | 4 per year | 12 per year |
| Forex markup | 1.99% | 3.5% |
| Best suited for | premium, rewards, lounge, dining, travel, shopping | travel, premium, lounge, rewards, shopping |
| Concierge | yes | yes |
Rewards Compared
Spending Rs 10,000 on the Vetta Credit Cardⓘ earns Rs 100 back at the base rate. However, for online and dining categories, the return jumps to Rs 400 per Rs 10,000, which is a substantial uplift. This makes Vetta highly rewarding for premium dining and online shopping where the 4% effective return rate is one of the highest available.
In contrast, the Marriott Bonvoy HDFC Bank Credit Cardⓘ offers a higher base reward rate of 1.3%, which translates to Rs 130 on Rs 10,000 spent. For its travel and dining categories, it provides Rs 260 per Rs 10,000, exactly double the base rate but still below Vetta’s 4% in those categories. The Marriott card’s emphasis is clearly on travel and dining, with moderate returns elsewhere.
Fees Compared
Both cards charge roughly Rs 3,000 for joining and annual fees, with Vetta at Rs 2,999 and Marriott Bonvoy at Rs 3,000. Vetta offers a fee waiver if you spend Rs 5 lakh annually, which breaks down to about Rs 41,667 per month. Marriott Bonvoy does not specify any fee waiver, meaning the Rs 3,000 annual fee is unavoidable.
To offset the annual fee through base reward earnings alone, Vetta requires spending of about Rs 3 lakh, while Marriott Bonvoy needs about Rs 2.31 lakh. The Marriott Bonvoy card’s higher base rate means a lower spend threshold to cover fees, making it more accessible for moderate spenders.
Which One Should You Pick
Choose the Vetta Credit Cardⓘ if you are a premium spender who frequents online platforms and dining establishments, and if you travel internationally with priority on lounge access and lower forex fees. Its quarterly domestic lounge access gate at Rs 50,000 spend is a consideration but manageable for a regular traveler. The concierge and comprehensive protection cover add significant value for high-net-worth individuals.
Opt for the Marriott Bonvoy HDFC Bank Credit Cardⓘ if your spending is travel-heavy and you want the additional perks like Marriott Bonvoy Silver Elite status and golf privileges. The higher number of lounge accesses per year and the simpler fee structure with no waiver threshold suits those who want straightforward benefits and are moderately premium spenders.
Skip Vetta if you do not spend enough to justify the high waiver threshold, or if you rarely use lounges or travel internationally. Skip Marriott Bonvoy if you prefer better returns on online and dining spends or are sensitive to forex markup costs.
What to Check Before You Apply
- Confirm the quarterly Rs 50,000 spend gate to unlock domestic lounges on Vetta to ensure you can meet it comfortably.
- Understand the real redemption value of points on both cards, as points-only rewards can vary widely in utility.
- Calculate your monthly spend against the waiver threshold on Vetta to determine if the fee waiver is realistic.
- Factor in the forex markup differences: 1.99% on Vetta versus 3.5% on Marriott Bonvoy can impact international spending costs.
- Verify which airports and lounges are accessible under each card’s lounge access program to avoid disappointment.

Comments
No comments yet
Be the first to share your experience with this card.